Small Cap Value Report (2 Jun 2014) - ARL, TRB, DQE

Good morning!
Atlantis Resources (LON:ARL)
This company is on my watchlist, after an interesting presentation by the CEO at a Mello investor evening a few months ago. It's a tidal power (from submerged turbines) company building an offshore project in Scotland.
Results for the year ended 31 Dec 2013 have been issued this morning. I was initially confused by these results, as the company appears to be heavily loss-making, and to have negligible cash, and a lot of debt, so from these figures it doesn't look viable. However I've just realised the company only floated in Feb 2014, i.e. after the reporting date in these results, so it must have raised fresh cash at that time.
Sure enough the Admission to AIM announcement from 20 Feb 2014 indicates that £12m in new equity, and £8m in "non-dilutive funding" (presumably loans or grants?) was raised. It generated a $13.7m operating loss in 2013, on $6.2m of turnover. So it's not possible to value the company based on these accounts. Instead one would have to get more information about the capex needed to complete the tidal energy project, future operating cash burn, and then look at forecasts for what profit it is likely to generate in the future.
One to watch, but I've not got any idea how much it's worth. Tidal energy seems conceptually a good idea - in that, unlike wind turbines, the amount & timing of electricity generation is entirely reliable & predictable. The only thing that could change it, is if the moon suddenly deviated from its orbit around the earth, changing tidal patterns.
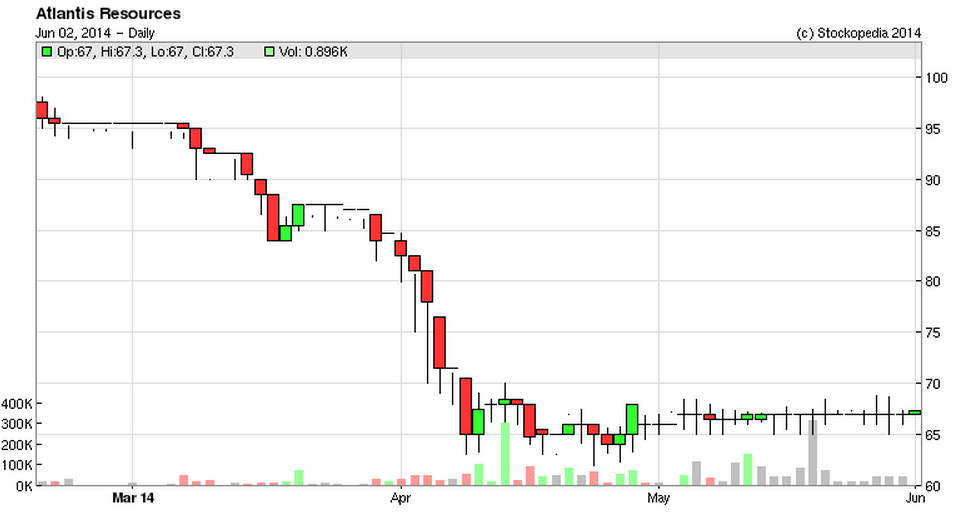
The share price began falling soon after it floated, but has since stabilised at a lower level.
Tribal (LON:TRB)
Tribal describes itself grandiosely as, "a leading provider of technology enabled management solutions to the international education, learning and training markets" - what on earth does that mean? I know they do the OFSTED inspections for schools. So I am awarding them a grade D- for ability to explain what the company actually does.
It announces an acquisition of an Australian company, for A$15.2m, which at the current exchange rate of £1 = A$1.81 converts to £8.4m, so small beer relative to Tribal's market cap of £165m (at 178p per share).
The company describes this acquisition as earnings accretive, which obviously it will be, since no new shares are being issued, and the company being acquired is profitable. It made A$2m of normalised operating profit on A$7.3m turnover in 2013, so a good % profit margin there.
I was going to dismiss this deal as immaterial, but actually with forecast net profit of £11.8m this year, adding on another £1.1m of profit is almost a 10% hike in group profitability. So that is likely to drive forecast EPS up to about 14p by my calculations. Therefore the PER seems reasonable at 12.7, based on 178p per share.
Tribal shares have been under pressure lately, with the drop on 16 May coinciding with an IMS issued on that day which said that profits are expected to be more H2 weighted in 2014 - which introduces additional risk that a profit warning might possibly be on the cards later this year? Companies often hope to recoup a shortfall in H2, but such a pattern often turns out to be a deferred profit warning. So I would treat this one with caution, which the market seems to be doing of late;

DQ Entertainment (LON:DQE)
It's difficult to thnk of a better example of why I don't ever invest in Chinese or Indian companies, than this company. Its accounts are just ludicrous. It reports good profits every year, but negative cashflow, and the telltale signs are always to be found on the Balance Sheet - over-sized debit balances in fixed assets and current assets are the giveaways that things may not be as positive as the P&L suggests.
The point is that debits can either be put through the P&L as costs, or put onto the Balance Sheet as assets (which therefore boosts reported profit). However, if that asset has little to no value, then it shouldn't be on the Balance Sheet at all.
So capitalising costs onto the Balance Sheet is the time-honoured way to boost profit in the short term, but of course you can't keep doing it forever, as the whole thing will eventually implode once people realise that the Balance Sheet has been stuffed with costs that should have gone through the P&L.
Indian accounts are easy to interpret, as there are 99 Rupees to £1. So just divide all figures by 100, to get the corresponding sterling amount. So in this case turnover for the year ended 23 Mar 2014 was about £24m, and a healthy profit before tax of £4.6m is reported. After tax that is £4.3m.
Given that the market cap is only £ 10m at 17p, this company looks amazingly cheap, that's a PER of only 2.3, what a bargain! However, it falls apart completely when you look at the Balance Sheet, an extract of which is below. Note how Trade Receivables of £30.5m is more than the entire year's turnover! In fact debtor days works out at no less than 464 days!! That's just ridiculous. Normal debtor days is about 60 days, and 90 days would worry me, but 464 days is beyond madness in my opinion, you just can't take the figures seriously at that level.

Also note that about £ 10m has been capitalised into "intangible assets under construction", so presumably that is the costs of making films. That's fine providing that the films can then be sold for a profit. Although given that customers don't seem to like paying the company's invoices, then that has to be questioned.

The Stockopedia graphics show how cheap these shares appear on conventional measures.
However, I need to keep nagging Stockopedia to include some warning flags for companies with growing intangibles, and in particular excessive debtors - since it's the excessive debtors that is usually the giveaway of dubious profitability in my opinion.
The same issue of excessive debtors exists at two of my other least favourite companies - Globo (LON:GBO) and Quindell (LON:QPP) (incidentally, I closed my shorts on these, so am able to discuss them here now).
There are some serious warning signals in the narrative - the worst one by far being that they are now seeking additional financing. The plans for a maiden dividend have gone by the board;
The total outstanding Trade Receivables of the Company at 31 March 2014 was INR 2,599m, out of which INR 1,322m was outstanding for more than 180 days. The Company has confirmations from its customers of their dues to the Company. The monies are being received on a regular basis from most of the customers, though in small values, thus confirming their commitment to pay and honour their liabilities.
The debtor position has inevitably put pressure on our cash flow and working capital which of course we are monitoring closely and our banks have been supportive. However, whilst debtors are gradually repaying, it has not come at a rate we expected and so we have been exploring options for a longer term funding solution for the Company to crystalize the large and growing pipeline of orders as quickly as possible. In this regard we are in active discussions with strategic / financial investors to refinance the business.
In view of our cash position, which as on 31st March 2014 stood at negative INR 844m, and the pressure on working capital, the Board is reviewing the Company's dividend policy and whilst it is not recommending a dividend at this time it will seek to pay dividends to shareholders as soon as financially and commercially viable.
So not a happy situation, and entirely predictable that the wheels would come off here - the accounts have been screaming that for a long time, in the excessive debtors, and the capitalising of costs. I see that the shares are down 26% already this morning, unsurprisingly, as there's now a significant risk that the company could go bust.
I hope no readers here are in this stock - I've warned here about its weak accounts numerous times.
Other than that it's extremely quiet for results & trading statements today, so I shall sign off and have an early lunch. More results are expected tomorrow, so see you then.
Regards, Paul.
(of the companies mentioned today. Paul has no long or short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
No argument from me - the amount of companies you cover is far too large for you to be expected to know every detail of their business. Was just trying to fill in the information James chose not to add.
I'm surprised about the whole ofsted thing, I'd assumed that contract was over by now. As you can tell I haven't really been following the company, but know them from encounters with their software at various points over the years.
Thanks oLTo, useful pointers. I'll emphasise their software more next time it's mentioned.
Cheers, Paul.
Regarding Tribal (LON:TRB) their main products are software for education providers - ways to record who your students are, what courses they are enrolled in, etc. Some of these products are very well established and there is probably a bit of a moat there as this kind of software seems to become deeply embedded. Not sure they still do ofsted inspections and even if they do I wouldn't describe it as their core business.
Hi oLTo,
Thanks. I'm pretty sure Tribal (LON:TRB) do still do the OFSTED inspections, as they refer to this contract maturing as being the reason why their order book is shrinking - see their announcement from 16 May 2014 to confirm this.
Looking quickly at their 2013 Annual Report, I see they capitalised £6.9m of software development spending, which I'm not keen on.
£64.2m turnover in 2013 was from their Systems division, and made an adjusted operating profit of £14.8m.
Their Solutions divison delivered £61.6m in turnover, and made a £6.1m adj operating profit in 2013.
There is a breakdown from their 2013 Annual Report, but the terminology is too vague. The OFSTED thing is clearly a significant part of their business, but I don't know whether it's in systems or solutions?
If a company isn't capable of clearly explaining what it actually does, then it's not really my fault if I describe it wrongly! Although going forwards maybe I'll just describe it as a systems & solutions provider in the educational sector, and let people decide for themselves what they actually do!
Regards, Paul.
@FREng
Atlantis have had a 1MW unit exporting to the grid for three years, and there's several other companies that have had similar 200kW-1MW units in the water for a year or more. So the basic technology is proven - they've adapted a lot of wind turbine technology for marine use. The last few years have seen a lot of the small engineering companies taken over by multinationals - you mentioned SeaGen by Marine Current Turbines, who are now part of Siemens. Alstom bought Tidal Generation Ltd from RR for ~£50m, OpenHydro is perhaps the closest match to Atlantis but a bit behind them, even so the French shipbuilder DCNS took a majority stake last year in a deal valuing OpenHydro at ~£100m. That interest reflects the technology now being mature enough for the multinationals to consider it - and now that the UK has guaranteed generous subsidies for installations commissioning in the next 5 years, capital is going to start chasing IRR's which Atlantis claim are over 30% ungeared.
There's an argument that the current price of electricity is too low at around £50/MWh wholesale, just about every form of generation needs a "subsidy" to enable new capacity to be built. Witness the Hinkley Point deal for new nuclear - 35 years at £92.50/MWh. Atlantis reckon they can get tidal stream down to ~£130/MWh by 2020, and in the £70-100/MWh range by 2030. At which point it's cheaper than nuclear, and if you have two projects half a tide apart, it provides steady baseload power that's more reliable than nuclear (there's no 6-week refuelling periods and any maintenance doesn't need the entire "power station" offline, just individual 1.5MW units). In a way Atlantis don't care too much as the politicians love them, the first phase will have a 20-year contract for 5 ROCs, under CfDs they get 15 years at £305/MWh. House broker talks of £70m/year free cash flow and NPV £722m from 245MW - obviously they're going to farm it out, but you can see the attraction for investors.
Yes they have the grid connections planned and booked (in fact that is a major asset for them although they don't like to talk about it much), they've got enough for the initial phase although under current published plans a big batch of their grid doesn't arrive until 2018. Other people are having to wait 7 years for their grid.
As Paul said, I've posted at length in the Pub:
http://boards.fool.co.uk/atlantis-resources-arl-at-mello-april-2014-13010169.aspx?sort=whole
@Paul
Per the handout we got, the phase 1A (a 86MW substation and 6MW of turbines) will cost £41m, although the recent Sunday Times article talked about £50m. Whether that means budget overruns or adding turbines of a different type, we'll have to wait and see. They've had ~GBP16m of free money in government grants and ~ £20m in government loans so it's nearly all paid for, they should announce the remaining wedge of funding imminently (they were talking about June 2014 from way back, so we'll see).
does anyone else have constant problems trying to log into this site? i gave up subscribing becasue of this. (Twelth attempt today)
Beginner,
No - I find it extremely rare to have any problems at all with this site. Works perfectly virtually all the time. No issues whatsoever today. Sounds like you need to upgrade your computer or broadband!
Regards, Paul.
Works for me too at the moment. It's very hard to diagnose intermittent problems but I had frequent issues before I upgraded my networking kit with various sites (though this one wasn't too bad). If you have an old router, upgrading may help, the web now works very differently from how it did 5 years ago and old routers often don't cope as they were not designed for this.
As a quick hack, an ad/web bugs blocker may help, as it greatly reduces the number of connections to the world a site makes.
Stocko could help make it more robust by making the site less of a denial of service attack (nearly 100 TCP sessions per page is really overkill when only 1 of them has actual user-useful content) which would also make it swifter and more reliable for people in distressed conditions, say overloaded office, mobile or hotel networks.
Stocko is not unusually bad (almost all web 2.0 sites suffer from junk overload) but still it could be improved, some suggestions:
- first reload your pages with network monitoring enabled, and see if it does more than you thought...
- configure HTTP cache setting correctly so that the browser doesn't need to ask "has this changed?" for every single page load for content that hardly ever changes (logos, icons, scripts, etc)
- move analytics to the server side (feed the logs to your analytics provider)
- or at least use the less antisocial analytics packages that minimise connections/traffic
- package icons in one file (e.g. pseudo-font)
- make links to third parties, e.g. twitter button,passive where you just have a static button and a link or popup that's triggered on a click, not for every page load (good for privacy as well as active buttons enable surveillance, giving away your subscribers financial interests to people who should not know)
- test the site every so often behind a crap connection emulator
Paul
You last commented on Concurrent Technologies (LON:CNC) last Christmas and put it on your watch list. I see that there was an AGM statement on May 27 suggesting that things might change this month. Here it is:
RNS Number : 1344I
Concurrent Technologies PLC
27 May 2014
27 May 2014
Concurrent Technologies Plc
AGM Statement
At today's Annual General Meeting of Concurrent Technologies Plc (the "Company"), a world leading specialist in the design and manufacture of high-end embedded computer products for critical applications in the defence, aerospace, telecommunications, transportation, scientific and industrial markets, Michael Collins, Chairman, will make the following statement:
"I am pleased to report that the Company's performance in 2014 has been in line with the Board's expectations. Our investment in developing single board computers with AMC architecture is producing good revenues, particularly from product applications in telecommunications. These revenues have helped to offset the UK Government export licencing issues that the Company expects to be relaxed during June 2014.
Our Engineering skill set has been expanding since we began recruiting for our new R&D facility in Massachusetts, USA, and our financial position remains strong after paying an increased second interim dividend. The Board remains positive about the outlook for the rest of the year."
I read these reports every day, but.....
I get a bit disturbed when I read supposed (and somewhat misleading) background information about a company I know something about (Tribal).
Of course, this won't invalidate anytjing written about other stocks.
James1314,
Please could you explain what you think was wrong about Tribal (LON:TRB) in today's (or previous) reports.
I'm always more than happy to correct any factual errors or misconceptions.
Thanks, Paul.
Hi Paul. Re' Tribal. The acquisition is likely to contribute £1.1m in operating profits. RNS doesn't say what the net profit is likely to be. Could even be negative?
Regards, Ram
Yes, tidal - I apologise for the slip.
I believe there were a number of planned prototypes for tidal stream energy:
Seagen had a 1MW marine current turbine approved for Strangford Lough in
Northern Ireland around 2006.
Hydrovision had a mid-water system prototype.
Lunar Energy had a seabed system (again 1MW) planned for around 2007.
Anyone know what happened about these?
There's also the cost of connecting to the Grid, as the best tidal power streams tend to be in remote locations.
The corrosion/maintenance and connection issues also apply to offshore wind, of course, which is one reason why there's more investment in onshore wind than offshore (around 7GW onshore against less than 4GW offshore currently; if you add in the amount under construction and with planning consent, the figures are 12.7GW onshore (6,694 turbines) and 8GW offshore (2,117 turbines)). Offshore wind is now a mature technology with higher subsidies than onshore wind gets. Over the next five years, onshore wind will receive £95 –£90/MWh and offshore wind will receive £155 –£140/MWh on contracts that will last 15 years.
An important factor in justifying significant capital investment in tidal power will be the ’strike prices’ for tidal power "Contracts for Difference" feed-in tariff subsidies. Do we know what these will be, and for what period?
If you are looking at the prospects for tidal energy production you might want to look at what this company are doing in West Wales. They plan to deploy their equipment in Ramsey Sound this Summer.
http://www.tidalenergyltd.com/
its not wave power its tidal power
Wave power seems inherently problematic. The sea is a very hostile environment, maintenance is likely to be an issue, and corrosion and marine encrustation make it hard to predict the long-term return on investment. Has anyone made a commercial success of it yet without continuing subsidies, over even a five-year period?
As Ericb says, Atlantis Resources (LON:ARL) is tidal power, not wave power. So its turbines are submerged in carefully chosen places where there is a strong tidal flow, which makes the turbines spin & generate electricity at predictable times of the day.
I asked the CEO about maintenance, and (from memory) he said that they have a plan for rolling 5-yearly maintenance - in that the turbines can be relatively easily removed & then serviced on land, then put back.
I also asked about build up of barnacles, etc, but he said they run a small electrical current through the outer casing, and this prevents anything from attaching itself to the turbines.
I don't know whether anyone has made a commercial success of tidal power without Govt subsidies. There are generous feed in tariffs for tidal power in the UK up to about 2019, if my memory serves me correctly. There was a thread over on TMF at my Pub, discussing this company a few months ago, so that would be a good place to go for further details. Hallucigenia gave them a hard time at the meeting, but seemed to be very positive about the company afterwards.
Regards, Paul.