Small Cap Value Report (2 Sep 2014) - VLK, JSG

Good morning!
EDIT: Apologies, I had technical problems with today's article, and some of it vanished, so I've recreated the lost bits as best I can remember!
Vislink (LON:VLK)
Share price: 45.25p
No. shares: 118.6m
Market Cap: £53.7m
There are two announcements today from Vislink, which is a maker of microwave cameras for outside broadcasting, and surveillance equipment. It has also expanded through acquisition into other related areas, such as broadcast software.
Strategic partnership - is announced today with Harmonic Inc. (NASDAQ:HLIT) which appears to have two elements - an order for £2m for product from Vislink, and a £2m injection of new share capital into Vislink, priced at 50p per share. I particularly like the second element, since it suggests the partnership is meaningful because the larger company is prepared to stump up equity funding, and of course it helps Vislink's balance sheet. Maybe it could even be a precursor to a takeover bid for Vislink at a later date, if the two companies work well together? Harmonic has a market cap of $602m, and a strong Balance Sheet.
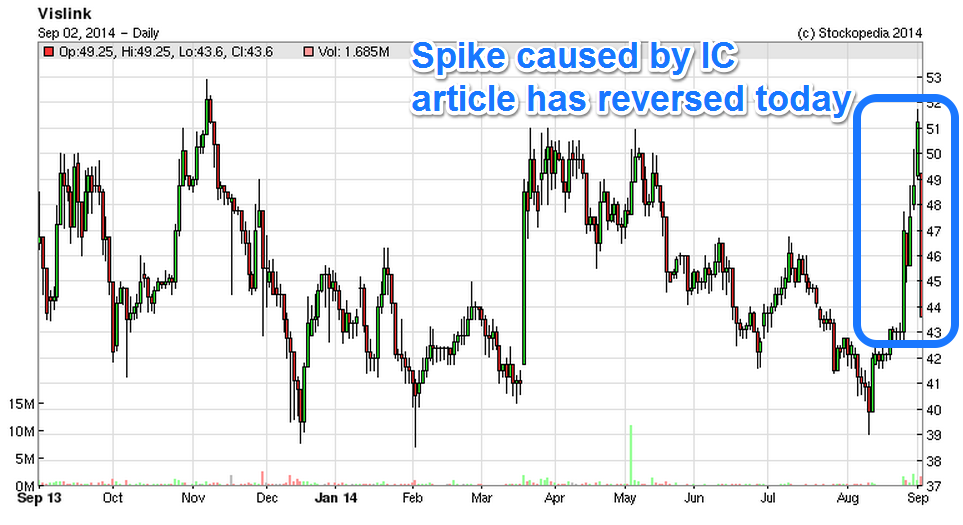
Interim results - a complicating factor here is that Simon Thompson of Investors Chronicle wrote an article last week which caused a significant but short-lived spike in the share price, in which he seemed to suggest that the company was about to publish strong interim results. As it turns out, the results published today are not particularly good, so it's all rather perplexing. It's never a good idea to try to second guess what results will be like, as you usually end up with egg on your face, as has happened in this case.
Profitability - adjusted operating profit fell from £2.0m in H1 last year, to £1.7m in H1 this year (the six months to 30 Jun 2014), although the company says that currency movements are to blame, without with profit would have been up 3.4%.
Reading the narrative, it sounds as if the core broadcasting part of the group (which makes specialist cameras such as the ones fitted to Formula One cars) has struggled in H1, but has been bailed out by a good performance from the software part of the group. That's encouraging to my mind, as it suggests that the acquisition of Pebble Beach has been a success, and increases the predictability of earnings in future - a stated aim of management in the company's growth plans.
Outlook - whilst the headline interim figures look somewhat disappointing, the outlook for the full year sounds a lot more encouraging;
Whilst the broadcast market has been challenging for our hardware business, overall, we are encouraged with these results. We have taken timely action to reduce costs in our Hardware Division and we have seen an improved trading trend, the order book strengthened in Q2 and the orders to sales ratio is better than 1.
We are delivering on our software strategy with Pebble Beach Systems performing ahead of expectations. The Group's revenue has benefitted from the change in revenue balance, with software providing longer term visibility. The partnership with Harmonic Inc, which is being announced later today, represents further excellent opportunities for the Group.
2014 represents a transitional and transformational year for the Group and with the increasing focus on our software division, we believe that this will enhance the Group's overall quality of earnings in 2014 and beyond.
The Group continues to trade in line with market expectations and the Board remains confident for the future prospects for the Group.
Valuation - the all-important "in line with market expectations" comment above means that we should be able to rely on broker forecasts, which suggests normalised EPS of 4.13p this year, and 4.77p next year. So at 45.5p per share, that represents a PER of 11 this year, falling to 9.5 next year - which looks good value.
R&D spending - I note that the company is capitalising a hefty amount of development spend, of £2.0m in H1 (same as prior year H1), so that's worth bearing in mind.
Balance Sheet - looks alright to me. There is £8m of new debt in H1, but that is almost completely offset by cash of £7.7m. There doesn't seem to be a pension fund, which is good.
Dividends - as in prior years, there is no interim divi. The company has consistently paid a 1.25p divi for the last six years, giving a current yield of about 2.7%.
Director Buys - Note that both the Executive Chairman, and Finance Director, have announced personal share purchases today, of £45k, and £22.7k, which are meaningful amounts for a small cap, and certainly seem positive.
My opinion - Today's interim results are not particularly good, but the outlook for H2 sounds sufficiently positive that I'm happy to continue holding for another six months. Although ambitious management have not yet been able to deliver the sort of step change in profitability that they've been targeting. Still, Rome wasn't built in a day, and it is pleasing to see that the acquisitions they have made appear to have been successful.
Furthermore, the partnership with Harmonic Inc looks intriguing.
Johnson Service (LON:JSG)
Share price: 62.25p
No. shares: 299m
Market Cap: £186.1m
Interim results - these look good, although I'm not sure how much of the growth is organic, and how much due to the acquisition of Bourne Services in Mar 2014. Adjusted operating profit is up an impressive 25.3%, and with debt now under control, interest cost in H1 has halved against last year, thus boosting profit before tax up 54.5% to £8.5m, very impressive.
There seems to be an H2 weighting to the results, judging from the prior year comparatives.
Outlook - a nice clear, and positive statement today;
I am very pleased with the strong performance of the Group in the first half of the year and expect the result for 2014 to be slightly ahead of current market expectations. The Board is continuing to seek further acquisitions in Textile Rental and to invest in additional capacity at existing locations. The significant increase in the interim dividend reflects the Board's confidence in the business going forward.
Sounds good to me.
Balance Sheet - Although this has been greatly improved, it fails my testing, with a rather weak working capital position, somewhat inadequate net tangible assets of only £13.4m, and net debt still a little higher than I'm comfortable with, at £31.7m. Also note that there is a;
Pension Deficit - although not a huge figure on the Balance Sheet at £9.0m, I note from the narrative that the company is required to make cash payments of £1.9m in 2014, so that's a material factor in valuing the company - as that's cash which could otherwise be paid out in dividends. The cashflow statement shows that the divis cost £2.9m last year, so the pension deficit payments represent 65.5% of the total cost of the divis. Quite material then.
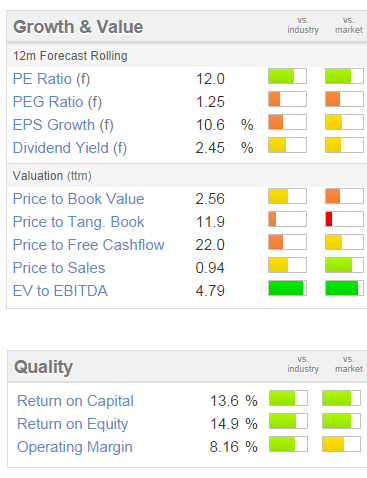
Valuation - looking at the usual Stockopedia graphics below, the price seems about right to me. Stripping out the net debt, and the pension deficit, would adjust the PER up to about 15-16 I reckon, which seems a sensible price. Note that the quality measures are upper medium, which is somewhat surprising, as I've always thought of this as being a low quality business, but actually it's quite good quality. It scores a very high StockRank of 95, so the algorithms on Stockopedia like this share!
My opinion - this seems a good company, and is probably priced about right in my opinion. Although the Balance Sheet puts me off from investing. It's not dire, but it's a tad too weak for my personal taste. Also it's worth bearing in mind that the company got into a mess before, with losses in 2008 and 2012, so I'd want to ask some tough questions about what they have done differently this time to prevent big problems recurring?
Regards, Paul.
(of the companies mentioned today, Paul has a long position in VLK)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Thanks for the replies guys.
Felt a bit like one of my other holdings, NTG LN where someone seemed to be selling them regardless of fundamentals/newsflow. Patience finally rewarded yesterday and today. It feels like a lot of these stocks have departed from normality on the back of forced selling/lack of appetite.
I don't think you are missing anything. Bought back into the stock today. Valuation looks attractive, although first half results were a little disappointing, cash flow was strong and its new acquisition Pebble Beach performed well in the two months that they owned it in the first half. Currency was also a factor but sterling has weakened significantly since then against the $; was about $1.70 in June, now 1.56. As you point out the dividend yield of 3.0% is not to be sniffed at.
Ahah, that's whats moved the price today :)
There isn't much news about this one other than ED producing a piece at the start of the week....that seemed to move the price down. I topped up after the results and am at my target holding. I think patience will be needed....in buckets :|
Regards,
Sully.
Another example of how smallcaps have fallen out of favour this year. Decent company with good prospects and a management team that have turned things around but has taken part in the big derating of smallcaps.
Trading on 9x p/e, no debt, pays a dividend and has earnings growth - what am I missing?
Intrigued to discover my sell order for VLK is not going through. As a novice investor I'm not used to trading small cap/AIM stock. Is there a specific reason why these shares are not shifting on LSE even though I can see trade volume? (You can assume my order is correctly placed, this is a question about whether some shares trade differently to others)
Hi Anne
Don't know what platform you are using - is it one that gives you a quote open for 10/20 seconds? If so, can't think of any reason for it not going through if you accept the quote within the time it's open.
Otherwise, are you specifying a sell price which is too high? Some small caps have appallingly wide bid/offer spreads. Have just got quotes via Share Centre for 5,000 shares :
Buy 48.770p
Sell 48.265p
In my experience, it can be difficult to buy/sell some small caps - and spreads can be v high. But would not expect this of VLK.
Many thanks for responding to my question, garbetklb.
I've not got to the bottom of what is going on today. The spread was pretty narrow and, as you describe the bid was actually higher than the ask price at one point! I only had 3000 shares to sell, so I'm wondering if there was a minimum order size in effect. I use Interactive Brokers for my dealing and was able to shift the shares eventually.
I'll carry on reading about the AIM market and see if there is some specific sell criteria that I'm not aware of.
IB is unusual for UK small caps in that it does on-exchange trades. If you put VLK.L in the Fragulator you'll see that the bulk of VLK trading is off market (probably mostly UK retail quote-based system) so you need one of those retail market makers to wake up and match your LSE on-exchange order.
Brilliant - thanks cig!
Back from Holiday. If I was a Director of VLK then I would be extremely Bullish, especially with the vast amount of earnings that are spent on my remuneration (can they justify it?).
I was deeply sceptical with tHE move to AIM and the following change of communication strategy from CEO (i.e. it stopped). Before he had been eager to speak with PI's.
Lack of quarterly updates also was a worry, hence why I bailed at the time.
IMO the published targets were an indicator VLK is up for Sale. It is still up for Sale IMO.
Sat on the fence!
Did anyone manage to see the Webinar? Did they manage to reassure on how they will turn things around in H2?
I listened to the webinar and was impressed with a) the cash flow in the first half and b) by how quickly they have reacted to the slowdown in hardware by cutting costs. I think that along with a Q2 improvement in orders is what gives them the confidence on H2. The acquisition of Pebble Beach Systems was clearly an inspired move given its margin characteristics and visibility of earnings. I asked whether we could extrapolate the results from Pebble Beach for the 3.5 months they owned it in H1 over the year as whole but was told not; it is a seasonal business with a slowdown over the summer months. So do I regret selling on Tuesday? A little but I did book a nice profit; I will be looking to get back in at some stage - hopefully in the low 40's.
Hi Paul
Maybe I am being overly cynical with VLK but:
- I always disliked their use of adventurous targets for revenue and profits growth as a way IMHO of pumping up the SP
- I don't like software companies capitalising development spend as there is massive potential for using this to help overstate earnings
- It seems very fortunate that they miss H1 targets but find everything will be great for the FY.
All IMHO DYOR . Apologies for the poor way this is written but I am using an iPad and have already lost by first more eloquent version at this post.
Regards, Martin
Interesting piece from interactive investor http://www.iii.co.uk/articles/189854/us-techies-take-stake-undervalued-vislink
Paul
The company has basically stated that they missed their H1 targets but will now (magically?) meet FY forecasts by becoming H2 weighted. Normally you would view this negatively. I am really not sure what is different here.
Cheers, Martin
Hi Martin,
The article surely made it very clear that I wasn't impressed with the interim results from Vislink (LON:VLK).
However, the company also specifically reaffirmed that it is on track to meet full year market expectations, and in evidence explained that they had taken cost cutting measures, and that the order book had picked up in Q2.
So I'm taking that at face value, although any company that misses its H1 numbers is more likely to warn on profit in H2.
Regards, Paul.
Have I been too hasty? I sold out of my Vislink this morning booking a 36% gain on purchase price, as I was pretty underwhelmed by the interim results. If it had not been for Pebble Beach it looks like the first half would have been pretty poor; the management must be given credit for the Pebble Beach acquisition which has improved both the profitability and visibility of the overall business. I also note the purchases of 95,000 and 50,000 shares by the Executive Chairman and Finance Director today. Have I been to hasty? I was starting to think yes but then I thought the shares were 40p only a few weeks ago and more importantly had I been fortuitous enough to have sold yesterday would I have bought back today? The answer to that is definitely no. I do not think there was enough in the outlook statement to suggest that they are in anything but a tough environment. I look forward to the conference call tomorrow, with an open mind to be convinced that my sale was premature!
The Finance Director of Vislink (LON:VLK) has picked up 50,000 shares at 45p
You could try sending an email to
hannah@equitydevelopment.co.uk
Interesting to see the picture painted tomorrow by management.
I for one want to know specific goals and dates and how they plan to get there.
Hi, if you'd like to register for the Vislink Webinar follow this link: https://attendee.gotowebinar.com/register/507908761766078977
all this talk of 8M profit at 80M turnover is pretty meaninless if you go on to say that you'll do it through organic growth and takeovers, when takeovers will inevitably lead to more equity being created. I would much rather a target based on eps, which might tell us something about what our shares would be worth rather than how big the group will be in the future (but not how much of it we will own !)
K
Agreed kenobi, although the Pebble Beach acquisition was funded with only 4% dilution if I remember rightly and is now generating a lions share of profits. The dilution was £2m which equates to just 6 months of profits at Pebble Beach if it continues to perform as it has done in the last 3 months. It's certainly looking like a shrewd move today given that it had a major contribution to profit but is only reporting 3 months of figures for that part of the business.
VTU had a number of 'big director buys' in July and the start of August for such a small company. Share price has drifted down since then.
Spaceandpeople (LON:SAL) SP taking a real hammering in the run up to the half year results expected in about a week. I'm tempted to buy some at the current 50p level but it's more a gamble at this point. Can management mend their credibility since the last profit warning?
Anyway, volume has been picking up in the last few days with the SP falling against complete radio silence from the company since the profit warning. A reassuring update could easily have 50% near term upside IMO. That versus a 25-30% potential drop for a lacklustre one. 52 wk high = 155 / 52 wk low 50.50. Strangely enough 50 50 is an apt number and precisely why I still can't push the buy button on this one at the moment.
Hi billytk,
I agree that the situation with Spaceandpeople (LON:SAL) is very frustrating - there's been a complete lack of information on trading since April, so it's terribly difficult to decide whether to make a leap of faith and buy more (I tried to buy some more today in my trading account, but found that IG are only taking closing bets now).
I remain of the view that management should recover from the setbacks earlier this year, but inevitably the market will take a cautious view in the absence of any further information. The market cap is only about £ 10m now, so given the good 5-year track record (prior to April this year), that does seem to already be discounting a lot of bad news.
I think we probably need to be braced for another profit warning, just in case.
Regards, Paul.
Good to see John Hawkins buy 95,157 ordinary shares in Vislink (LON:VLK) today @ 47p
Vislink (LON:VLK) 's Exec.Chairman is obviously still bullish about prospects. He has just bought over 95k at 47p (increasing his shareholding by almost 50%).
Not the moment to sell I feel.
Paul,
I agree with forecasting just before results. Simon has done that poorly on both Molins and Vislink now. Many investors out of pocked in short time
I2015
Paul
I thought exactly the same about Harmonic's investment - think there could be a good prospect of takeover. They have the cash to buy the company already. Also they have paid 10% more than the current SP for their interest.
Happy to hold as the market is hammering trading statements which do not smash expectations.
Hi Paul,
What struck me about the results was that the interim operating profits were broadly equal to last year despite a £1.1m contribution from Pebble Beach Systems since acquisition.
Peter
Hi Paul. Having read the report bleary eyed on the commute to work this morning I notice that there is no longer mention their plan of "achieving revenues of GBP80m and adjusted operating profit of GBP8m" by the end of 2014. The language has changed to meeting market expectations. I do not rate Simon Thompson as much as I used to and quite a few of his recommendations have been badly timed and have disappointed - not to mention his love of Chinese stocks (in his top shares for 2014)! I will tune in tomorrow for the Vislink (LON:VLK) webinar.
There is mention of that target here:
'As the proportion of our business coming from higher margin software becomes more significant, the target revenue needed to generate our long stated operating profit target will change. The Company remains committed to its target operating profit of £8.0m through both organic growth and bolt-on acquisitions.'
I read that as - "we're still aiming for £8m profit but we won't need £80m turnover to achieve that because the software services through Pebble Beach are much higher margin than our hardware business.". Just my opinion of course - do you think this is right?
I agree that this is positive in that the software business is higher margin and therefore as this segment grows the impact on profit will be greater than the hardware sales. I take it therefore that they will need a lower turnover to meet the £8m profit target. I can't see them meeting this target by the end of FY 2014 however, which was their original headline strategic target. They should never have been so forthright with their targets (or maybe have kept them internal) because this only leads to disappointment. Perhaps they should have set a £60m / £6m target and surprised the market on the upside!
Hi Paul,
Here's the sign-up link for the Vislink results webinar:
[EDIT: Sorry, have just re-read the email I received from Equity Development and it forbids distributing the link...]
Will be joining myself as VLK is my biggest holding.
This sounds positive:
'The Company remains committed to its target operating profit of £8.0m through both organic growth and bolt-on acquisitions.' However, I do wonder whether 'remains committed' is too vague a phrase to be using at this stage, 6 months before the end of the target time frame. Some would argue that they should never have set a specific target which can disappoint if not met...
Cycle
Is webinar only for pros as I can not find link even though I have registered with their site?
Thanks
The Vislink (LON:VLK) webinar is for private investors too (like me). Sorry, can't remember how I got my invitation by email to the webinar...
Thanks anyway
No, you don't need to be a Pro, as I've registered for the Webinar without a problem. I just clicked on the link that they emailed to me. I am registered on their site and also received the email for Kromek.