Small Cap Value Report (20 Sep 2016) - FCCN, JDG, FJET, PTD

Good morning!
I so enjoyed the documentary on TV last night about the problems within the Labour Party. It's even worse than the militant tendency infiltration of the 1980s. Much, much worse. The resulting schadenfreude gave me a surge of energy, which I put to good use by writing up 6 new company sections in yesterday's SCVR.
Here is the link to yesterday's full report.
These are the companies I commented on yesterday evening;
SKIL Ports & Logistics (LON:SPL) - total car crash - yet another overseas AIM company craps out. Foolishly, I got caught on this one, breaking my own rule on not buying overseas AIM stocks.
7Digital (LON:7DIG) - poor results, and running out of cash. Fundraising coming, probably.
DP Poland (LON:DPP) - poor interims. Still loss-making. Painfully slow progress. But good LFL sales growth. Bonkers market cap, for such a poor roll-out. Forecast to reach breakeven in 2018!
Adgorithms (LON:ADGO) - awful interim results, but pots of net cash. Shares at a discount to net cash, but beware - it's overseas & AIM.
Styles and Wood (LON:STY) - interims are nothing special, but it has heavy H2-weighting to trading. Shares have had a great run, but price looks up with events now.
Spectra Systems (LON:SPSY) - strange little company. Lacklustre interims, but optimistic noises about future potential. Cash-backed balance sheet. Has delivered nothing in last 5 years, so could just be more of the same?
Right, on to today's news.
French Connection (LON:FCCN)
Share price: 40.5p (down 7.2% today)
No. shares: 96.3m
Market cap: £39.0m
(at the time of writing, I hold a long position in this share)
Interim results, 6m to 31 Jul 2016 - bit of a mixed bag here, there's something for both bulls and bears. This is a strongly H2-weighted business (relying on big sales of party dresses for Xmas), so the interims are always ropey.
This time the loss before tax is flat against last year, at £7.9m, on turnover down 8.7% to £69.2m. Falling turnover is not necessarily a problem here, because it's a special situation where a massively loss-making retail division needs to be down-sized, to eliminate the losses.
Whilst licensing & wholesale divisions are good, profitable businesses. Therefore understanding FCCN means realising that it is 3 connected, but distinctly different divisions.
I've written mountains of stuff on this company, so if you want all the background, here is the archive.
I recommend having a look at an excellent open letter published recently by an 8% shareholder in FCCN, called Gatemore. This nicely summarises what's wrong with the business, and how to fix it. This echoes some of the points I've made about the substantial underlying value locked up within this company.
Stephen Marks, FCCN's founder CEO/Chairman has reinforced his reputation for pig-headedness by apparently refusing to meet with Gatemore. Trouble is, he owns 41.7% of the company, making it almost impossible to get rid of him. That size shareholding allows him to treat the company like a private company unfortunately.
I don't like arrogance in business leaders, but it can be tolerated if they perform outstandingly well. The problem here is that we've got stand out hubris, combined with dismal performance. This is only possible by virtue of a near-controlling shareholding. It's not good enough.
Retail division
You may ask, why can't FCCN just close down its loss-making shops? It would, if it could. The problem is that typically 15-year (from inception) leases often cannot just be surrendered or assigned. FCCN's financial strength has been its achilles heel, as landlords would rather keep FCCN as a tenant, and know they're going to get the rent, than allow FCCN to assign the shop to someone else with a weaker covenant.
However, over time leases expire and can be handed back to the landlord. Some leases can be sold or surrendered for a nice premium, e.g. FCCN's Regent Street shop was surrendered for a cracking premium - FCCN were paid £2.4m to get out of what was almost certainly a heavily loss-making shop. I think its Oxford Street shop (which is probably haemorrhaging cashflow due to massive rent & rates costs) could be worth millions, as it's on the other corner from Selfridges.
The good news is that there are signs of life in the problem retail division. Losses have been stemmed by £2.9m compared with H1 of last year;
The loss of £8.2m in retail was an improvement of £2.9m compared to prior year. This was made up of positive LFL sales of £1.9m, store closures of £1.1m and offset by a £0.1m currency impact.
Positive LFL sales of 6.5% in H1 is very good, but is flattered by very weak comparatives in H1 of 2015 at -10.7%. So at least some progress is being made here, which I find encouraging.
Ecommerce is included within the retail division, and it's doing well, rising from 22.3% to 26.5% of total retail revenue. I think that's good news.
To my mind, the future for this company is clearly to sell mainly online, and through third parties (via wholesaling), as it's really not very good at conventional retailing. I think the brand is too expensive & niche to work generally as standalone High Street shops. But it clearly does work online & within department stores.
Note that one of the relatively new NEDs is formerly from Asos, so should be having useful input in helping FCCN develop its online strategy. Another recent NED was a top product sourcing person from Next. So, for all his faults, at least Stephen Marks does seem to be bringing in people with the right experience.
Wholesaling
This division performed very poorly in H1.
Operating profit from this division dropped from £5.5m in H1 of 2015, to £3.0m this year.
However, all is not, as some credible reasons are given;
- Poor performance from USA Dept stores (a large part of this division's business)
- Difficult UK High Street environment (so why did FCCN's own retail division do OK then?)
- Lower level of in-season (i.e. repeat) orders.
- Knock-on impact on gross margins, with more discounting required to clear excess stock.
- Change of phasing of deliveries, with some moving from H1 to H2. This makes sense to me, as warmer late summer, early autumns in recent years means that autumn ranges may well be pushed out into Aug or Sep, rather than the July interim period end.
Encouraging noises are made about current wholesale trading;
Historically we have seen the wholesale business lag behind the performance of retail given the buying cycle, and this is reflected in an improvement now being seen in our wholesale performance in recent weeks.
Overall then, a rather disappointing H1 for wholesale, but based on the above, I think they should catch up to some extent in H2.
Licence income
This is the part of the business which demonstrates the considerable hidden value in the brand name. People pay FCCN to stamp their name & logo on various products, including perfumes, spectacles, accessories (e.g. handbags/purses), even sofas (through DFS).
There have been a few hiccups in H1 in this division too;
Licence income of £2.4m was generated during the period, a reduction of 20.0%.
Newer licensees again performed strongly, particularly the furniture licence with DFS.
We have moved our global fragrance licence to Inter Parfums in the period and while this is a significant move for the future it has caused a short term shortfall in income.
Also in the period our US based shoe licensee filed for bankruptcy, which required us to be conservative in our income recognition.
A mixed bag there, so you can either see it half full, or half empty.
The way I look at things, the licensing revenue is proof of the brand value, and even at H1's lower level, it still covered the costs of about half the group's central overhead. Last full year, at £7.3m (profit) it covered the bulk of the central overhead of £9.3m. That's a very nice position to be in. If they can just make wholesaling work better, and retail work at all, then the shares would multibag.
Dividends - there aren't any. Last one was paid in Jul 2012. So management keep getting paid their salaries, but shareholders get nothing. Hmmmm.
Balance sheet - remains very strong, although one has to keep an eye on that depleting cash pile - down to £7.7m at 31 Jul 2016. Although that will be a seasonal low, and exacerbated by the slower wholesale deliveries pushing into H2, mentioned above.
Bottom line, as things stand now, there are no solvency issues. That could change though, if trading falls off a cliff, but for now it looks fine.
Outlook - sounds OK, although I think the choice of works isn't quite right. You can hardly call a £7.9m loss in H1 a strong performance as a starting point;
Continued strong performance in the first six weeks of the second half
The Chairman/CEO sounds upbeat in his comments, and in my view he generally tends to tell it how it is in the results statements, so this can be relied upon to some extent (although obviously the future is always uncertain);
"Although the overall performance for the first half has been disappointing, the retail result has been particularly pleasing when compared to last year in what has been a difficult retail environment. Performance in wholesale and licensing has been more challenging but we have started to see an improvement recently and expect to see a recovery in the second half.
There is still much work to do in the rest of the year to move the business forward significantly but we believe the team we have in place and momentum we are seeing will help us to achieve this. As ever, the overall result will be dependent on the Christmas trading period but the second half of the year has started well."
My opinion - it's a given that performance is poor, and needs to dramatically improve to make this share go up a lot. However, it's a special situation, which requires deeper analysis.
It sounds as if there are good reasons to expect H2 to be better than last year, which should mean that the overall loss for 2016/17 seems to be heading for around the £2-4m loss level, I reckon. That's bad, but doesn't put the group under any solvency pressure. It gives the company more time to eliminate more loss-making shops, which is the key to unlocking value here.
I think risk:reward here remains good. The downside is protected by the balance sheet, and the brand value. Retail losses are at long last reducing, and the glitches in the wholesale & licensing divisions in H1 of 2016/17 don't look serious to me.
Overall then, I'm happy to hold, and remain of the view that, at some point shareholders might get a big payday here. Although we may have to be patient, and it does tie up money that could be put to use elsewhere.
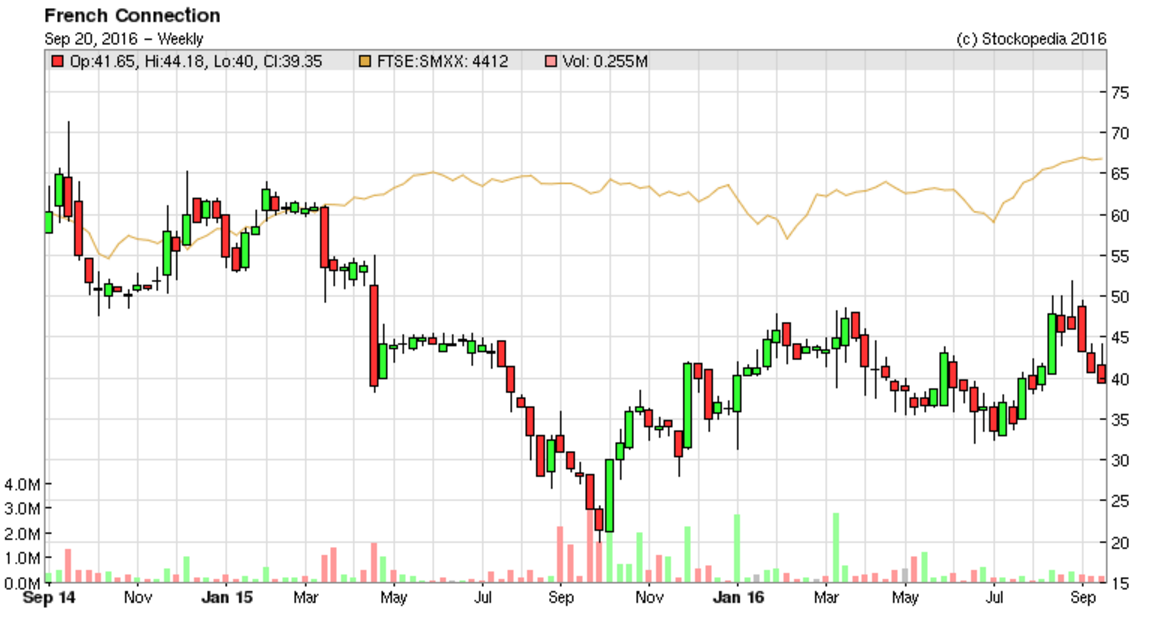
This share tends to polarise views, which is fine, that's what makes a market! Shareholders have to be ready to tolerate a bumpy ride too, as you can see from the 2-year chart below. That dip to 22p in Sep/Oct 2015 was a fabulous buying opportunity! I flagged up this opportunity in my report of 21 Sep 2015, concluding that it was worth buying more at 25.75p, which I did. Although as with a lot of bargain buys, it's very difficult to do at the time, because everyone keeps telling you what an awful thing averaging down is.
Judges Scientific (LON:JDG)
Share price: 1285p (down 9.5% today)
No. shares: 6.1m
Market cap: £78.4m
Interim results, 6m to 30 Jun 2016 - Judges last updated the market in July, which I reported on here, with a puzzling update which seemed to be a full year profit warning, and also mentioned disappointing Q1 order intake. So we've already been warned that H1 2016 results will be below H1 2015.
In that context, the H1 figures announced today don't look to bad to me, if you accept the adjusted figures;
- Adjusted pre-tax profit down 11.4% to £3.0m for the half year.
- Adjusted basic EPS down 19.2% to 33.2p.
Clearly not very good, but not a disaster either, and we had been previously warned to expect a weak H1.
Profit warning - however, there's another full year profit warning;
"This has been a period of contrast, with success in the pursuit of earnings-enhancing acquisitions and frustration in respect of short-term trading performance.
At this stage, the Board therefore believes that the full year results will be significantly below market expectations."
Looking at Stockopedia's terrific little graph that shows the last 12 month movement in broker EPS consensus forecasts, you can see that there have already been a series of reductions. So today's update means a further reduction in forecasts is on the way;
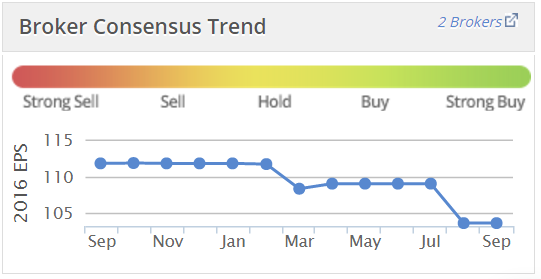
Broker update - W H Ireland has reduced its earnings forecasts quite considerably today. 2016 EPS is now forecast to be 82.8p - that's a 17% reduction from its previous forecast of 100p EPS. Quite a big drop.
WHI has also reduced its 2017 EPS forecast by a similar percentage.
I wonder why the market has been so unperturbed to only reduce the share price by 9.5% today? It seems to me that a 20-30% share price fall would have been more appropriate.
Order book - is down on last year, closing at 10.7 weeks, versus 11.7 weeks last year. This doesn't exactly suggest a bumper H2 is on the cards.
Dividends - the interim divi is up from 8.1p in 2015, to 9.0p this year, so that's good. Although note that the divi yield is quite modest, at c.2%.
Outlook - ah, this looks to be the reason that the market is giving the company the benefit of the doubt - there are some quite positive outlook comments. Although once again, as with the 20 July 2016 update, it ends with a bombshell in the last sentence;
The Group's business environment remains uneven.
The long term effect of Brexit is difficult to gauge but, in the short term, the Group benefits from the most favourable global exchange rates since 2009.
Although exports represent a vast majority of the Group's sales, the UK is not an insignificant market and it may remain adverse until the Brexit negotiations are concluded.
China has been an important source of growth and its continued appetite for education and research investment remains an important factor in the Group's development.
The Group remains convinced of the long term growth of the sector, however the Board believes that medium term growth is dampened by its dependence on public funds. As a result the Group is currently more vulnerable to short-term performance fluctuations.
Positively, this has not affected the pursuit of our business model as seen through our continued completion of value enhancing acquisitions.
Order intake in the third quarter continued the more positive trend observed in June and organic order intake since the beginning of the year is now ahead of the comparative period in the prior year.
A satisfactory outcome for the year still depends on this improvement being sustained and on a continued revival of Armfield's market and on the resolution of the aforementioned production issues. At this stage, the Board therefore believes that the full year results will be significantly below market expectations.
Overall then, I find that somewhat confusing. It sounds as if things are improving, so why does the narrative then conclude by saying full year results will be significantly below market expectations (which have already been lowered in July)?
Balance sheet - not great, but probably OK overall, providing profits don't slip any further, is my overall view.
NAV of £21.9m becomes negative NTAV of -£1.7m when you write-off intangible assets.
I wouldn't want to see the company take on much more debt.
My opinion - earnings expectations for this have fallen a lot - starting at 111.9p a year ago, to 82.8p today. Therefore, my inclination would be to steer clear. Or not pay more than a PER of say 10.
So for me, this share would only start to get interesting if the price fell by about another 35%.
As WH Ireland concluded today, the company needs to earn back the right to have a premium rating, after a series of disappointing updates this year.
A few quickies to round off with:
Fastjet (LON:FJET) - the new CEO is desperately trying to salvage something from this mess. Fleet size is to be downsized from 5 to 3 aircraft, which are then going to be replaced with 3 smaller, leased aircraft. That's presumably in order to realise the cash from selling owned aircraft in order to burn up that cash too.
Amazingly, "investors" put another $20m into this crock in Aug 2016.
The H1 2016 figures are just a joke;
- Revenue $33.1m
- Operating loss (continuing activites) $31.0m.
Balance sheet - NAV of minus $10.7m at 30 Jun 2016. This will have been helped (temporarily) back into surplus with the c.$20m raised in Jul/Aug 2016.
My opinion - this company has been a gigantic value destruction machine - it's cumulative losses are a staggering $280.2m (retained earnings, on the reserves section of the balance sheet).
I simply cannot understand why any fund manager would have thrown their investors' money away, by participating in the various placings. I bet few (if any) put their own personal money into FJET shares. It's been obvious for several years that this company was going nowhere fast. If simple bloggers like me (and others) can spot the obvious flaws, why can't the fund managers?
I'd be amazed if this company still exists in a year's time. It's going to zero in my view.
Pittards (LON:PTD) - confident for full year, but interims unremarkable.
All done for today. See you in the morning!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Industry comment regarding the failure of Fastjet (LON:FJET) to gain traction
http://aviationweek.com/commercial-aviation/fastjet-s-failure-missed-opportunity-african-air-transport
I have found over many years that companies making lots of acquisitions usually go wrong. Trouble is these acquisitions obfuscate the progress of the underlying and results can flatter for quite a while. But sooner or later it all starts to unravel. But there are a few exceptions.
Thanks for the presentation/video it was interesting but I found the net effect was to make me rather glad not to be a shareholder, I'm not sure they've really got a grip on the factors impacting their sales pipeline and frankly as the number of businesses they've got has increased their earnings should have become more predictable not less imho.
Further to the H1 results, here's a subsequent video of Judges presenting at Mello 26.9.16
Length: 20 minutes
http://www.piworld.co.uk/videos/2016/10/1/judges-scientific-jdg-an-update-at-mello-26916
Brad Ormsby, FD. Talks through the H1 results, where trading has been difficult, and how things have been going since.
David Cicurel, CEO. Talks through the acquisitions, particularly Dia-Stron, and the general market place, and the outlook.
Re DP Poland (LON:DPP) I think the argument that delivered pizzas are too expensive in Poland assumes that the prices being charged are UK ones whereas looking at their website they are considerably lower. The ingredients for a pizza are very cheap in any case and if wages are lower in Poland then so are costs. It doesn't prevent them making a profit there. I'm tempted to order up a small slice.
John,
Yes, agreed. I also think the sales growth of the business suggests their pricing is OK.
For me the problem is that the market cap is now £50m plus, yet they are still loss making and have some considerable way to go to even get to a 20x multiple... especially when you consider there may well be another round of dilution before they become self funding.
The current valuation really bakes in that they will get to a quite large number of stores doing material sales. That is certainly possible (hence why I invested earlier this is year) but by no means a given - after all the scope for large numbers of stores outside the major metropolitan areas) must be more limited than in the UK. They really need both continued like for like growth (which I do think they'll achieve) and a large rolloutb(which I think they might achieve, but it's more questionable) to justify the current price, IMO.
Regarding leases, I presume the contracts have terms to prevent FCCN selling leases onto some company that could even be set up to fold in a couple of years. If such lease transactions were allowed, well even BHS could have just exited it's unprofitable stores via such a mechanism.
Regarding DPP, I think Paul's previous argument that delivered pizzas are too expensive in Poland must be a big factor. If people are getting well under half UK salaries, they will be less inclined to order delivered pizzas. Although, of course Polish salaries should grow faster than those here, so it might work in the long term.
sounds interesting rh, is there any debt ?
what's the back ground, I see that the share price fell pretty sharply from about 300 to about 220 in may, what was behind that ?
K
Sorry Kenobi missed your post earlier!
No debt , except for a £2.375m mortgage on the Shafton freehold which was put in place on acquisition , 6.2m cash, thinly traded as c.73% is held by insiders so has tended to drift between RNS's , the CEO is relatively new, been there since June 2014 and I think he's done a great job of revitalising what was a fairly moribund business . The key is being an added value supplier rather than just moving big lumps of metal around the place , and that is where the business is transforming itsel in my view.
Cheers
Hi Paul Billington Holdings (LON:BILN) reported its Interims this morning , just over £30m market cap buys you £6.24m of cash, full year profits knocking on £4m* and a business trading well on all fronts. Also the game changer is that's bought a humungous steel facility from administrators at a knockdown price which gives capacity to grow in the future. the EBT has been selling shares which has suppressed the price but this looks like quality earnings at a very attractive price imho
I bought shed loads before today so I'm talking my own book.
Cheers
*denotes my guess, it did 1.74m in the first half
Hi rhomb. I used to own Billington years back when they were called Amco and Lenny Licht, remember him?, had a stake. Still got a butt end of Billington hanging around and I like the cut of their jib so going to retain. As you say it is cheap but they do need to maintain a strong balance sheet in my opinion to see them through the cycle. For choice though I prefer SFR which has Indian market upside in for nothing and a very dominant UK market position.
Hi fanmail
I hold SFR as well but BILN seem to have a few cute ways of adding value, I like the Architect specified stuff that http://www.tubecon.co.uk does and the http://www.marshallstairs.com stairs business is a good one. Finally http://www.easi-edge.co.uk is great HSE driven niche that is growing fast and Billington Holdings (LON:BILN) has a leading position in the market.
I agree re balance sheet but they're generating huge cashflow, near £4m in the first half alone after accounting for the Shafton acq.!
I tried to buy some Billington Holdings (LON:BILN) shares ages ago, spotting the value in them when they were about 100p. But sadly the stock was so illiquid, that it proved impossible to buy, so I gave up trying.
Did a similar thing with Trakm8 Holdings (LON:TRAK) when it was 20p a few years ago (since 10-bagged).
Just goes to show, that if you find a winner, then it's best to just pay up to get the stock. That's what I tend to do now, if I find something really good.
Regards, Paul.
Just on the state of the labour party, it's nothing to be pleased about, governments need strong opposition to keep them on their toes, when a government thinks they will get in regardless of what they do, they start doing things that are unpopular and ill advised, and like the start of this governments term, things like planning to sell off the land registry, cuts to disability benefit etc, which often they end up back tracking from,
If the opposition are strong they do their jobs, they propose amendments to bills, which improve things, when they are weak and divided, it's not good for government either.
K
My remark on the Labour Party was only intended as a tongue in cheek reason for me having a sudden burst of energy last night. Wasn't intended to be taken too seriously!
Regards, Paul.
There is an important issue in the current Labour Party turmoil, IMHO: the PLP have lost the support of many of the LP members who selected them as parliamentary candidates. The members are significantly to the left of the PLP it seems, which (if it stays that way) implies that more left-wing candidates will be selected over coming years, giving a stronger parliamentary voice to the left wing just at the time when the economic hit from Brexit reaches a lot of the electorate.
So far, the comments about inflation have focused on the fall in Sterling, but the bigger hit (again IMHO) will be the increase in wages from, firstly, the Living Wage and then from the removal of a million or more low-wage workers from the economy. In a competitive market, it is the price at the margin that sets the prices throughout the market, and the UK just voted to eliminate a large number of workers earning marginal wages. That doesn't seem to be in the inflation forecasts yet.
sorry Paul , sense of humour failure there then ! (on my part)
Re FCCN, I appreciate the landlords preferring to keep them as tenants, not least because they are a prestigious name, but aren't their clauses where they can either sell on the lease or sub lease the stores ? Recognising that if something happenened to the tenant during the leasing period FCN would be in hock to cover rental payments ? but then surely that just becomes an issue of who you sublet or sell the leases on to ?
I would be worried that the reason they can't do this is because they can't find anyone to sell on to, perhaps even at a lower rent with fcn subsidising it, so long as they pay more than rent - losses for that store that would still make sense. Of course then you get the problem that overheads on each store are higher because they are spread across less stores.
K
Hi Paul,
DP Poland (LON:DPP) yes, the valuation is crazy, sold 40% of holding at 46.66 but hanging on to the rest. I had exactly the same fears about Domino's Pizza (LON:DOM) on AIM but did buy soon after it came to the main market. My total return on Domino's Pizza (LON:DOM) of 591% and annualised over nearly 10 years at 29.7% For DP Poland (LON:DPP) I am showing annualized of 83% and total return is meaningless at I have taken out more than I put in. I did, unusually for me, top-up (big-time) within 25% of the nadir. So totally agree with your assessment of share price but might challenge your view of the long term prospects of the company. Dominos is not actually a food outlet but rather a software company enabling you, parked on the sofa, to sate your inner craving with a couple of taps on your mobile. Search for latest ads on line, last one I saw on TV was the girls turn up and greet the boys, caught beers in hand on sofa. "Oh! Pizza" and a surreptitious tap on phone maintains expectations all round.
Regards,
Seadoc.
PS Bought Dominos as son told me they were the tastiest pizzas. Daughter have a Polish friend who is adamant that Dominos is best fast food in Poland. .
Seadoc,
Yes I agree with you re DP Poland (LON:DPP). I did hold but sold out recently (for a near 100% gain in short order, if only all my picks were that successful....) as felt the share price had got ahead of itself, sales growth is good but there are still significant operational and financial risks which I felt weren't reflected at current levels.
But I absolutely agree with your assessment of the business and am very cognisant of the Domino's Pizza (LON:DOM) precedent (not coincidentally I also hold £DOM). I am keeping a close eye on DP Poland (LON:DPP) and expect to reinvest in it at some point in future when risk: reward is more favourable. The franchising model DPP is using means that the profitability of the rollout will take longer to come through but it is the right approach IMO as means they can roll out a more capital light business and the incentivisation of the franchise model (with ownership pushed down to franchisees) works well I feel.
Rgds,
Phil
It would be interesting to go back to the early days of Domino's Pizza (LON:DOM) and compare its figures, growth, etc, with that of DP Poland (LON:DPP) to see if they are similar, or different.
Also, I wonder what DPP pays to licence the Dominos brand?
Broker forecast is for DPP to only reach breakeven in 2018.
A decent retail roll out should be thundering into profitability quite early on, and then generating all the cashlow it needs to expand. DPP isn't anywhere near that stage. Repeat placings, with very little to show for it. The figures remain dismal. The market cap is factoring in 4-5 years of continued growth, which is bonkers I think.
I prefer online growth companies, as they're not constrained so much with having to open dozens of new sites. £G4M is my current favourite online growth stock. It has a lower market cap than DPP, but recently announced 73% organic sales growth in H1, and profits ahead of forecasts. Doesn't need to raise any cash, and is expanding even more rapidly in Europe now. It's just a vastly better investment proposition than DPP, in my view.
Regards, Paul.
Paul,
Yes you make some fair points. In fact your sober analysis helped stop me getting carried away here - so thanks for that!
My recollection is that Domino's Pizza (LON:DOM) 's expansion was slow and took a while to reach critical mass. However, that is ling before I became a Domino's Pizza (LON:DOM) shareholder (more 's the pity...) so I may well be wrong. Hopefully I will get time to look at that this weekend, if I do I'll write up my findings in a post here.
On the topic of rollouts, it's not a small cap, and is eye wateringly expensive, but one of the most interesting ones around at the moment IMO is Metro Bank (LON:MTRO). Again, I'm hoping to put my thoughts together on that one on here in the near future, as I've not seen much discussion of it, here or elsewhere.
Rgds,
Phil
Paul,
For DP Poland (LON:DPP) The Master Franchise Agreement runs for 15 years from June 2010. It is amortised in straight line over this life with currency adjustments each year, and is usually just under £40K a year. So my best guess is that it is $500,000 for the fifteen years. They are also buying software, I think from Domino's Pizza (LON:DOM). Last year about half the new staff taken on by Domino's Pizza (LON:DOM) were IT related. 70% sales in Poland are ordered on-line.
Regards, Seadoc
Mark, later rather than sooner, should militant consolidate their hold. Corbyn is their useful idiot.
B2V
I used to hold these shares, but sold out at 80p, for all the reasons you have mentioned I think it is worth watching these shares I may dip my toe again sub 35p.
"The resulting schadenfreude gave me a surge of energy,"
Don't get too excited, Paul. Labour are bound to win an election sooner or later, and then where will we be?
Did anyone listen to the Fairpoint (LON:FRP) webinar yesterday? i noticed the SP fell in the afternoon which suggests maybe there were some bad indicators? I might email the organisers to see if there is a recorded copy.
I sold out of French Connection (LON:FCCN) this morning as I am concerned by the rapidly reducing cash, the fall in wholesaling and licensing, and the CEO's refusal to engage with sensible shareholder concerns. They really should have improved on last year's overall loss figure following the store closures during the period. The reluctance to refresh the brand and store closures might also continue to impact on licensing and wholesaling. The only time I notice French Connection is when I pass a store so while store closures are necessary for the survival of the business they might also have a detrimental impact on the licensing and wholesaling by reducing the visibility of the brand. I might come back in if the SP falls low enough though and appreciate hearing different views on the company as it's an interesting play.
I believe Fairpoint (LON:FRP) dropped yesterday as full year forecasts were trimmed a little more and Simon Thompson at the Investors Chronicle issued a sell note on the stock.
Thanks. I'll have to read what he said.
You can listen to the webinar here: http://www.directorstalk.com/fairpoint-webinar-equ...
paralc
I listened to it. The directors sounded confident and in control of the business but they said nothing of any significance. Someone called "Paul" (!) asked about the poor online reviews and got a bland response. That was the weakest point in the webinar, IMO.
Hi FREng,
Re Fairpoint (LON:FRP) webinar yesterday, you commented;
Someone called "Paul" (!) asked about the poor online reviews and got a bland response. That was the weakest point in the webinar, IMO.
Haha, you've rumbled me! Yes, I submitted a question as to why the reviews mentioned here on Solicitor.info were so terrible, and what are they doing about it? My question was sanitised by the moderator!
I agree that their answer was weak. They mentioned TrustPilot reviews - so I checked, and there are only 2 for Simpson Millar, although more flattering that on the other site.
The rest of the webinar went well I think. I like the strategy, and have bought some stock in it. With a PER of 7, and a 7% divi yield, it looks good value to me. Especially as running down the IVA book should clear all debt.
Did you noticed also that mgt comment on dividends was encouraging - suggesting that the direction of travel for divis is only upwards. I liked that bit.
Regards, Paul.
Paul,
Yes, I guessed the question had been sanitised. I had asked whether they were concerned about the terrible reviews too, so the management will have received a hint about investors' concerns, which can't be a bad thing. The didvidend reply was helpful, so I'm a relaxed holder for now.
Did you see the acquisition RNS from Styles and Wood (LON:STY) this morning? The vendors drove a hard bargain, but it looks strategic to me and should enhance earnings from 2017 (and earlier if Styles and Wood (LON:STY) manages its allocation of overheads between divisions well :-).
FCCN story tells it all, not a clever business, not a clever owner, story says will stay that way. I generally avoid retail which is all about the detail, here all I hear is "and they are useless at the detail". Lots of nice easy sucesfull and improving businesses out there to spend your money on