Small Cap Value Report (21 Jan 2016) - SOM, MCO, ANCR, ECK, QXT, EMR, ESCH, FOUR, IGR

Good morning!
Somero Enterprises Inc (LON:SOM)
(at the time of writing, I hold a long position in this share)
I recorded a fascinating interview yesterday afternoon with the CEO & CFO of Somero Enterprises Inc., listed on AIM since 2006. This is a highly cyclical specialist maker of laser-guided concrete screeding machines, which claims to be (by far) the world leader in this niche. The company is based in the USA, where it does most of its business, but is also expanding into China, and has smaller sales in many other countries.
Why it was particularly interesting to interview this company's management, is for their insights on the economic outlook in USA & China in particular, which I focussed on. I was expecting to hear caution, but not a bit of it! They were very bullish about the economy in America right now, and the pipeline for the next 1-2 years.
With regard to China, their feeling is that the market opportunity there is enormous, and so far they have only scratched the surface, that even in more depressed conditions there is still plenty to go for.
This interview has added to my general sense that things are perhaps not as bad as the markets seem to be thinking. For that reason, I closed nearly all my large cap shorts yesterday, and went long of a basket of US large caps with Stockopedia StockRanks in the high 90's. I'm lucky enough to have the US subscription service here, and it's very helpful to see all the key numbers in a format with which I am familiar. Just one successful trade would easily cover the cost of a subscription - it amazes me how people will cheerfully punt on the markets and lose thousands without a qualm, yet baulk at paying a few hundred quid for quality information sources - false economy if ever I've seen it.
This sanguine view is confirmed by a deluge of trading updates in the UK in recent weeks, most of which seem to have been fine, both in terms of 2015 results, but also outlook. I'm seeing a generally fairly confident tone in the outlook comments that UK small caps are putting out at the moment, with obvious exceptions such as embattled sectors like resources & associated service providers.
Therefore, for what it's worth, I'm more a buyer than a seller at the moment, for reasonably-priced, financially sound UK small caps. There are some nice discounts on offer today, for things that have seen purely sentiment-driven selling in the last 3 weeks, but where fundamentals are fine.
EBITDA
I questioned mgt of Somero about this in my audiocast yesterday. Why did they quote adjusted EBITDA in their trading update? Investors generally want to know about real profit, not "bullsh** earnings", as Charlie Munger famously described EBITDA.
I know a lot of PR people & brokers read my articles, and are the people who often write, or at least edit trading updates for their clients. More and more updates are using EBITDA as the benchmark performance figure. I can't talk for everyone, but the overwhelming view in my investor network sees this extremely negatively! So you're not doing your clients any favours at all by quoting EBITDA in announcements, instead of what you should be quoting - profit before tax (it's fine to adjust out acquisition-related intangibles, and genuinely exceptional items).
By quoting EBITDA in a trading update, I immediately think they're trying to pull the wool over my eyes - since many companies (especially in tech) aggressively capitalise development spend, thus producing a wildly inflated EBITDA figure which bears no relation at all to the genuine profits (if any) being generated.
(Some people always point out at this stage that accounting standards require companies to capitalise development spend. That may be true in theory, but in practice, is untrue. Companies effectively have carte blanche to do whatever they want, within reason. Some companies write off everything, others capitalise as much as they can. It's a policy decision, and can get past the auditors either way, providing it is reasonable & defensible. There is no single correct profit figure - there is a sliding scale, often surprisingly wide, of available profit figures which management can choose from, by adjusting their accounting assumptions, levels of prudence with provisions, etc.).
So quoting EBITDA in announcements is extremely negative. Stop it! I want to know what the genuine profits are, not an inflated EBITDA figure.
Oil sector
Sometimes you hear something which you know makes sense, and will probably make you a lot of money. I got that feeling yesterday, when an analyst said that the current depressed oil price presents a "generational opportunity" to make money from oil company shares.
Obviously you have to be very selective, and balance sheet strength is key - more than that, cash is key - as we're likely to see a wave of insolvencies in the sector if low prices persist. The analyst went on to say that c.80% of the world's oil production is now below cost, therefore it's inevitable that supply will eventually contract, and demand increase, such that the imbalance will switch from a glut, to a shortage. That will inevitably lead to higher oil prices, and a geared effect on the share prices of oil producers which survive the downturn. Nobody knows when, mind you.
This very much struck a chord with me, so I've started building up positions in cash-rich, low cost oil producers. It's not my area of specialism, and it's a complex area to research and invest in, since there are many more factors to consider. Looking at historic and forecast data is fraught with risk. So I'm relying on sector experts with a proven long-term record of success to guide me. Don't ask me for any tips please, and I won't be including oil shares in these reports, unless something really exceptional crops up.
For now, I prefer to just pick up a basket of stable, financially strong, low cost oil producers, and am prepared for potentially large short term losses - nobody knows when or where the low will be, but I think we're getting close to the point where it's just a question of starting to buy, and then adding to positions as they drop further. I usually buy (and sell) too early, so it might be sensible to ignore me, and wait a bit longer.
All food for thought anyway!
MartinCo (LON:MCO)
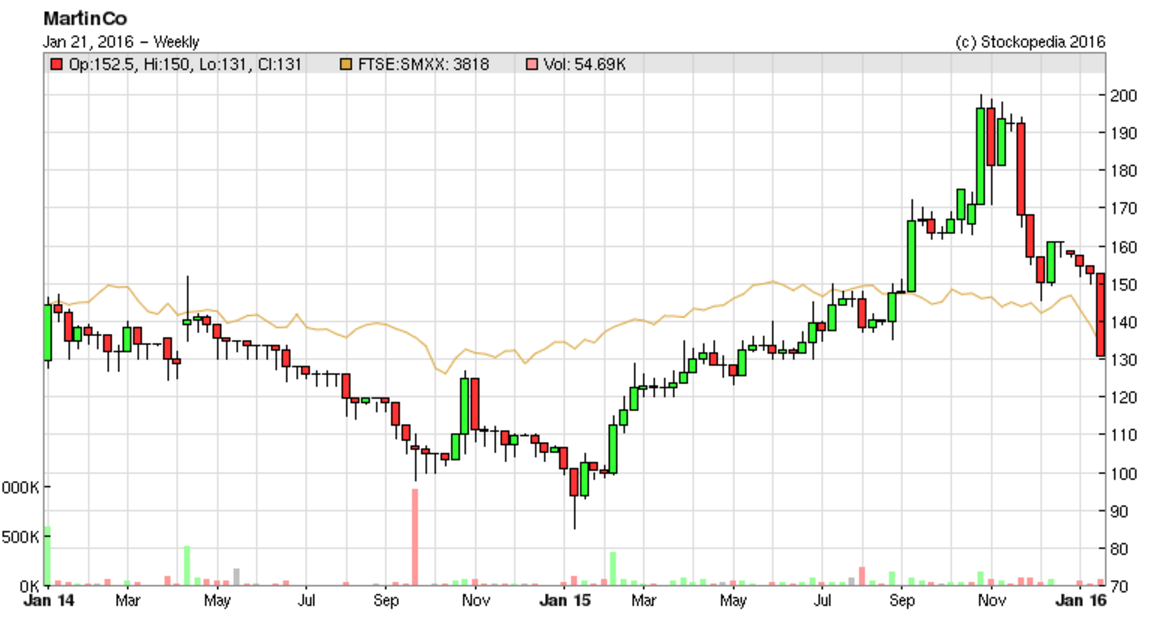
Share price: 131p
No. shares: 22.0m
Market cap: £28.8m
Trading update - this announcement came out yesterday, but I missed it in the blizzard of things going on.
The summary is that 2015 was in line with expectations, and so is current trading. Unfortunately, I can't see any broker estimates, so can't quantify this.
It looks potentially interesting though, as group revenue rose 38% in 2015, and the balance sheet contained £2.3m of net cash. The business seems to be franchised property management, focussed mainly on residential lettings.
Note that the shares have drifted down heavily, from a peak of nearly 200p last autumn, to 131p today. Sentiment has probably been hit by the declining attractions of buy to let for private investors, due to impending tax changes. Also the property sector seems to be attracting new entrants online, with much lower overheads than traditional agents. Therefore it looks a sector which is set to suffer from disintermediation (i.e. technology enabling buyers & sellers to connect directly, cutting out the middleman) via the internet, as are so many other sectors too. So the speculative money seems to be chasing massively over-priced hype stocks in this sector, like Purplebricks (LON:PURP) .
It sounds as if Martinco's business is robust;
"We do not envisage the Government's recent changes to the buy-to-let sector significantly impacting on our business. We are well positioned to sell investment properties if investors do decide to exit, and our research suggests that larger investors will purchase this stock. Buy-to-let investors have generally reduced gearing in their portfolios over the years since 2008 and are well positioned to absorb rising interest rates.
"We remain positive about the outlook for our core lettings business, from which 76% of our franchise royalty income is derived. I look forward to providing a further update at our full year results in April."
I don't really have enough figures to go on, so cannot form a view on the valuation of this share at the moment. I look forward to reviewing its 2015 accounts in April (why so late? Come off it, a small company like this should be issuing results in Feb, not Apr. Sloppy).
The chart looks intriguing - I like shares that have dropped a lot, but then issue upbeat results and outlook statements, as this one has. Sometimes that can be a bargain.
Animalcare (LON:ANCR)
Share price: 203p (down 1.0% today)
No. shares: 21.1m
Market cap: £42.8m
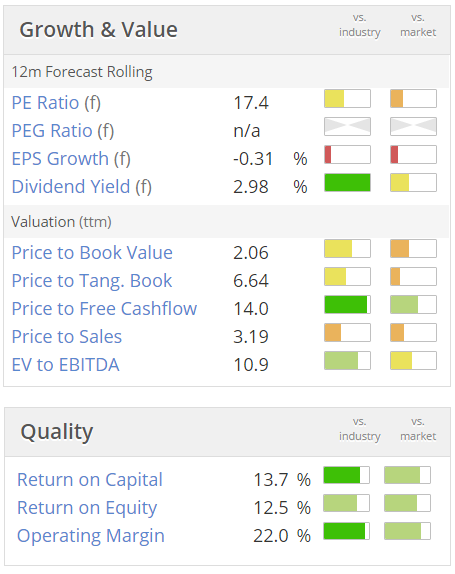 Trading update - this RNS was also released yesterday. The company is a supplier of veterinary medicines. Note from the usual Stockopedia graphics on the right that it has high quality scores - in particular an excellent operating profit margin, indicating pricing power.
Also note that it has a high StockRank of 97.
Ed has explained in the past that a high StockRank is no guarantee of success, but picking a basket of high StockRank shares should, over time, out-perform a basket of low StockRank shares, and the performance stats validate that.
So personally I always get a warm glow when a share that appeals to me on fundamentals also has a high StockRank - it's almost like having a robot friend that is checking my work & giving me a reasonableness check. I try to keep low StockRank shares to a minimum in my portfolio, as the odds of success are lower, so selection has to be very careful, and higher conviction, to make me take the additional risk.
Trading in H1 (to 31 Dec 2015) sounds OK, if unexciting - revenue up 2.7% to £7.1m, although that rises to 5.6% if a one-off £0.2m sale in the prior year is excluded.
What concerns me is that the PER has risen from about 12 in 2014, to 17.4 today. Therefore the share price appreciation since I last looked at it in Oct 2014 has been all about expansion of the earnings multiple, rather than the business doing much in terms of growth.
This is a general problem with small caps. We used to be able to buy good companies on a PER of about 12. Now we have to pay 15-20 for similar companies. Maybe that is a function of ultra-low interest rates for an extended period? Assets become inflated in price. Remember the concept of mean reversion - what goes up will eventually come down again.
Cash - this has risen to £6.1m, and the historic figures show nice cash generation, with the company hoarding a growing cash pile. Cash represents 14.3% of the market cap, so it's fairly significant. It would be interesting to find out what the company intends doing with its cash pile - acquisitions, or a special divi perhaps? Given its stable, and high operating margin, the company doesn't need to hoard cash, and could actually run with say £4m or more of net debt. So there is scope to release about £10m in cash for other purposes, in my view - giving potential upside for investors.
New products - details are given about new products being developed, so I think this is the key area to research, if looking into this company in more detail. If it has good growth in the pipeline, then the shares might end up looking cheap in a year or two perhaps? I like the concept of cash generative companies funding their own growth, through new products, or acquisitions.
Dividends - a nice progression of well-covered divis has been paid out in recent years. The forecast yield is currently about 3%.
Outlook - sounds confident;
Following the solid trading performance in the first half, particularly across the Licensed Veterinary Medicines and Animal Welfare Product groups, the Board remains confident about the prospects and outcome for the full year.
My opinion - this is only a brief review, as usual, so more in-depth research is always necessary. On the face of it, this share looks perhaps priced about right, or possibly a little too expensive? It's difficult to justify a PER of 17 for a company with pedestrian growth, although adjusting out the cash would bring the PER down to nearer 15, not outrageously high, but hardly a bargain.
If you think the new products are set to generate significant growth in profit, then it might be worth pursuing.
It looks a good company, and has a lot of features I like - high profit margin, decent & growing divis, net cash, stable & predictable profitability, I'm just not convinced the current valuation stacks up.
Another point to consider is whether customers might squeeze its margins? Vets have traditionally been fragmented, so individual customers had little buying power. Now that groups like CVS are consolidating the sector, then maybe a more concerted effort might ensue for customers to eat into ANCR's high margins? The availability (or not) of cheaper, substitute products needs to also be a key avenue of researching this share, to determine whether its profit margins are sustainable or not.
Overall though, this one looks potentially interesting to me, and certainly worthy of deeper research. If you like the company, then the recent sell-off looks a potentially good entry point in relative terms, if not in absolute valuation terms perhaps?
Eckoh (LON:ECK)
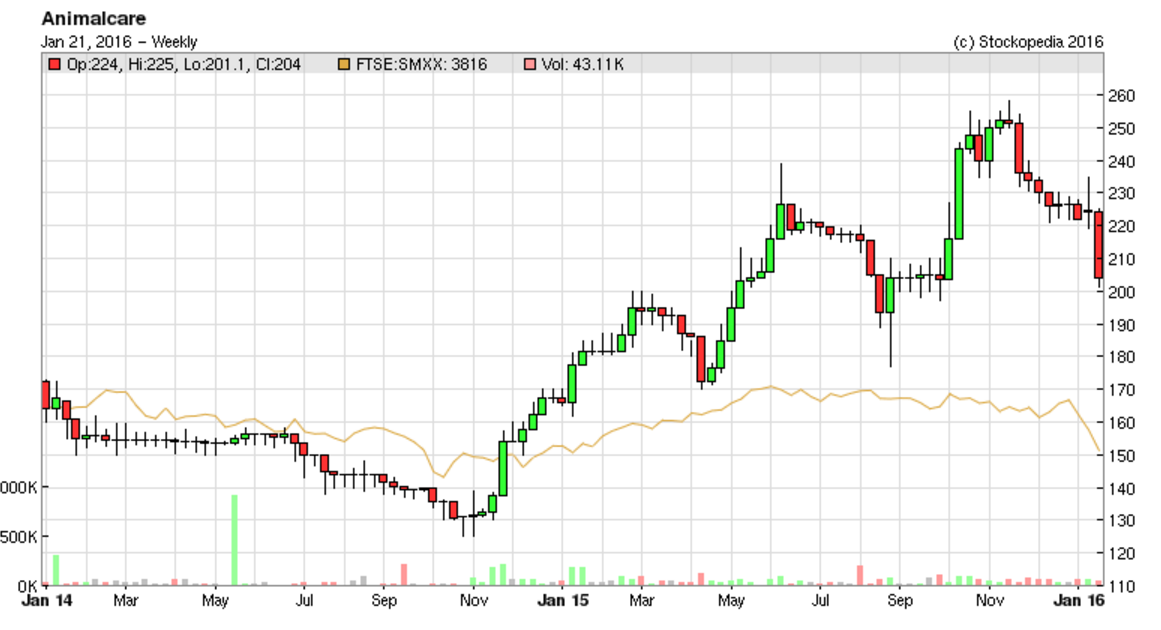
Share price: 44p (down 3.8% today)
No. shares: 224.8m
Market cap: £98.9m
Trading update & contract wins - this RNS came out yesterday, and sounds amazingly bullish,with new contract wins, a bulging pipeline of opportunities, etc.. Which is all great, but the trouble is, it's already in the price, because the update for y/e 31 Mar 2016 is only in line, not exceeding expectations;
...the Group remains on track to deliver full year results to 31 March 2016 in line with market expectations.
Valuation - broker consensus is 1.37p EPS for this year, and they usually use adjusted earnings, so it's a full figure, and the PER drops out at 32.1 times, clearly a very rich multiple that anticipates considerable further growth in profits.
EPS forecast for 2016/17 is 1.77p EPS, so the PER then falls to a still high 24.9 times.
My opinion - this share has sold off quite a bit recently, but it still looks expensive to me. The company seems to be on a roll with contract wins, etc., but the share price already seems to factor in flawless execution.
Also, as a general point, companies tend to make a big deal about new contract wins, but they don't announce attrition, of existing contracts expiring & not being renewed, do they?! (unless they're so material that they trigger a profit warning). As the CEO of one AIM-listed company once told me - ignore contract win announcements, unless they are accompanied by an out-perform against market expectations statement, and broker earnings upgrades. Companies win & lose contracts all the time, it's part of the normal operation of a business. It's only when the aggregate triggers upgrades to estimates, that it's of any real significance.
Also with ECK look at how much is adjusted out of the P&L for share option schemes (backdoor remuneration) - £1.2m in 2014, and £0.9m in 2015 - highly material numbers in both years, which makes you wonder for whose benefit this company is run, when you compare that with the dividends paid out in those years of £0.5m and £0.7m respectively!
The share option charges were not only considerably more than total dividends paid to all shareholders in both years, but represented nearly 57% of adjusted operating profit in 2014, and nearly 28% in 2015. So this company is clearly a lucrative vehicle for management, less so for shareholders, with a paltry 1% dividend yield.
So with this share still priced to perfection, paying out-sized rewards to Directors, and a poor divi yield, the growth potential isn't exciting enough to compensate for the negatives, in my view. To my mind it would start to look more interesting at, say, about 30p per share (tops), and if the divis were increased meaningfully, along with curtailing share options.
Finally, a few brief comments on things I overlooked earlier today;
Quixant (LON:QXT) - Trading update - profit "comfortably in line with market expectations" for calendar 2015, so that's reassuring.
Completed acquisition of Densitron in Nov 2015 - pleased with progress.
Outlook - positive;
"The Company has started 2016 well, with a healthy order book. This underpins our confidence in achieving market expectations for 2016."
My opinion - PER of 25 for 2015 looks high. Drops to 15.1 times forecast 2016 earnings, so valuation rests on forecasts being achieved. Doesn't look very interesting to me.
Empresaria (LON:EMR) - trading update - for calendar 2015 - ahead of expectations, despite currency headwinds.
Adj PBT expected to be up 23% y-on-y. I make that about 10p EPS, so looks quite good value at 87p.
Net debt reduced to £7.3m. Sounds good, but the balance sheet is still quite weak.
My opinion - I see modest upside, maybe to 100p from here. The group seems to be performing well, and has a StockRank of 98. Worth a look.
Escher Group (LON:ESCH) - shares up 11.1% to 175p today, so market likes today's trading update.
Reports adjusted EBITDA nearly doubled to $4.0m in 2015 vs 2014. Real profit figures are not given, unfortunately.
Net debt reduced to $2.7m, which sounds manageable.
Licensing revenues will "continue to be uneven and difficult to forecast" - which is the Achilles Heel of this, and many other software companies.
My opinion - it's impossible to forecast accurately, hence impossible to value the shares with any degree of confidence.
4imprint (LON:FOUR) - yet another strong update from this quality company;
Consistent with the trend reported in the trading update issued on 21 October 2015, strong organic growth continued through the fourth quarter of 2015. Unaudited Group revenue for the year ended 2 January 2016 was $497.2m, 20% higher than the prior year comparative of $415.8m. Underlying** profit before tax is expected to be at least in line with market expectations.
Net cash is reported at $18.4m.
My opinion - a super company. I would be reluctant to buy now - if the USA is entering recession, then we could have already reached peak earnings?
International Greetings (LON:IGR) - (at the time of writing, I hold a long position in this share) trading update was issued on 18 Jan 2016. Strong trading over Xmas, in line with expectations for the full year.
Directorspeak - focus on cash conversion & paying increasing divis (I like it).
PER of 12.5 (based on 153p share price) looks fairly good value, after recent sharp decline in share price. I like a big fall in share price, combined with a positive trading update - so it looks like selling has been sentiment-driven, and could be a buying opportunity perhaps?
All done for today! See you in the morning.
Usual disclaimers apply.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
I really enjoyed the Somero interview and am especially interested as I am involved in the development industry and have shares in this company. Quality, flatness (especially on retail warehouses) and speed are quite big issues for us and I'm certainly going to investigate this company with our contractors in more detail.
Anyway, the CEO sounded positive and straigtforward and answered every question without waffle so certainly worth the effort - thnak you Paul
EMIS yesterday (Thursday) would be worth a gander. Market reaction to results seems very harsh.
Agreed on oil near the bottom and added a last tranche of RDSB which I have been building since the £15. (I sold my original share last summer just north of £25
I favour integrated big oilers rather than simply E&P producers since the integrated super majors can hedge their downstream off their upstream to some extent. They are also traders in the business with good hedging strategies
Supermajors can also capitalise on distress selling of assets and pick up cheap producers in times of low oil price
On supply/demand and price. The relative in-elasticity of the industry means that the supply response to a much lower price takes ages to play out. For a high enough price there is no shortage of oil. However, as oil falls below $30 many operators cannot produce without a loss. So for example the lifting costs in the North Sea are around $50 a barrel whereas Kuwait is around $5 a barrel.
CAPEX in the industry is being slashed with uneconomic wells being capped: this will lead to a supply constraint and price will respond ...and so the cycle goes
FWIW I still think we can get a bit lower and RDSB may be available nearer £12....but for my mind then the rest of the market may well follow that canary!
I wonder if they would appreciate it enough to make a donation to the excellent http://qualitysmallcaps.co.uk/
Paul
Re: Oil Sector
Although a sub $10 barrel can't be ruled out, there is a general consensus emerging that the bottom has been reached and for those brave enough to take the plunge, now might be a good time.
Given that share picking can be both enjoyable and rewarding, I've been researching, cash rich, low cost producers, boasting huge reserves and sensible ongoing development budgets, overseen by strong management with records for delivering. Also importantly no exposure to the potential tinderbox of the Arab World, after all, why compound risk?
FWIW I've been drip feeding into two stocks.......
SOCO International
LekOil
I'm sure many of your admiring followers would appreciate if you feel able to disclose, if and when, you decide to make an investment in the sector.
With king regards
Paul;
An extremely interesting interview with the Somero directors, thanks for organising it. Certainly a very good sales presentation covering all their 'Unique Selling Points' & also their views on World economy & Chinese potential; just a little concerned that they were over selling their own book on the economy aspect. However The reasons behind the 207/8 downturn relative to the current position was very convincing.
Paul
Just listened to Somero interview. I found it very reassuring to hear that the key difference in the eventual downturn that we will have compared to 08 is that the balance sheet is a different animal - Mr Cooney's view was that in 08, with a lot of debt, investors were sceptical about Somero's ability to survive. That should not be the case this time, particularly since they have a lot of variable cost too. Anyway, my point was not to provide a transcript (!) but just to say thank you and invite any contrary opinions.
Thanks
Regarding Eckoh (LON:ECK), Maybe if somebody is going to investor show on 2nd feb, london, they could take up the issue of share options directly with them.
Pauls comment "The share option charges were not only considerably more than total dividends paid to all shareholders in both years, but represented nearly 57% of adjusted operating profit in 2014, and nearly 28% in 2015. So this company is clearly a lucrative vehicle for management, less so for shareholders, with a paltry 1% dividend yield"
Paul, thanks for pointing at the EBIDTA issue in your interview with Somero Enterprises Inc (LON:SOM) ? May I ask what their answer was?
Just a comment on Stockranks: it seems a bit odd to me that the overall Stockrank is 97 for Animalcare whilst Value is 97, Momentum is 97 but value rightly sits at 49. So if each of two of the three components equal the overall value, it implies zero weight to the Value component. Can that be right?
I see what you mean but many 99s have scores in the 80s, in fact very few have 3 scores in the 80s, I know I screen them, there are only 7 that 3 x 80 scores or higher, none have 3 x 90s scores. So if a share has 2 x 97 that is very high and will balance out the lower value score. I guess if value score was over 80 if would be a 100. only Hydro International (LON:HYD) has 100, well it did yesterday now 99 as value has dropped.
Rosered wrote:
"Just a comment on Stockranks: it seems a bit odd to me that the overall Stockrank is 97 for Animalcare whilst Value is 97, Momentum is 97 but value rightly sits at 49. So if each of two of the three components equal the overall value, it implies zero weight to the Value component. Can that be right?"
No, that's not how the StockRanks are calculated. According to this Stockopedia help page:
http://help.stockopedia.com/knowledgebase/articles/184381-how-do-you-calculate-the-stockopedia-stockranks
"The Stockopedia StockRank™? is an equally weighted combination of the following component rankings.? Please refer to the subsidiary pages to learn more about each of them...?
ValueRank
QualityRank
MomentumRank
We calculate these ranks for every company in the market, sum them and then re-rank the output from 0 (worst) to 100 (best). The stock showing the highest Composite StockRank will have the highest score across all 3 contributing ranks."
Very helpful. I see and understand the methodology now. However as some more interested in value and quality and a bit wary of momentum, I will be more careful in referring to the Composite Stockrank. Thank you for your assistance.
"However as some more interested in value and quality and a bit wary of momentum, I will be more careful in referring to the Composite Stockrank."
In that case, you mighty prefer to use the QV Crossover Rank rather than the QVM Composite StockRank (if you're not already using the QV Rank):
http://help.stockopedia.com/knowledgebase/articles/374424-what-are-the-stockrank-crossovers
Thank you pka, I now see I can use the QV crossover in duplicate form then add a few twists of my own.
sorry to break this to you herbie....
http://www.reuters.com/article/us-global-oil-idUSKCN0UV14D
regards
OK so its already happening, looks like they are going to ramp up production also.
Funny enough the oil price has gone up to over $29 now.
I agree with you on oil - I think you're too early to buy in! I'm still short on oil in ETFS DAILY SHORT WTI CRUDE OIL ETC (LON:SOIL). I was planning to take my profit at $25 per barrel but $20 now looks possible. Lots of US shale companies will go bust before the market turns in my opinion. Or something will happen in the Gulf to restrict supply, but no way of knowing that in advance.
Still, that's what makes a market.
I tend to agree if the Iranian sanctions are lifted there will be even more oil on the market.
Paul
I am with you on OIL must be oversold by now, not interested in the physical but a couple of interesting shares have already been mentioned.
Paul, you will be aware that TomWinnifrith was slating you yesterday on your views of Trakm8, as expressed in your comments after the interims in September. I expected you to make some reply comment today. I had a look at the accounts for the Monkey aquisition, and have to say I think he has a point that this seems like a pretty duff deal. The impression Tom gave me is that he thinks TRAK could be another Quindell! Would you do a blog reviewing the evidence and Toms case, please.
Also, I totally agree your comments on EBITDA. Another complaint I have with many updates is the statement "in line with expectations" as Martinco today. This is completely meaningless when there are no broker forecasts (and pretty meaningless when there are) in my opinion. The addition of estimate figure range would not be difficult. This sort of statement is always a negative to me.
Many thanks, Cic.
I am more circumspect about the oil price shift in the last year and am not for jumping back into the sector on anything other than a short term rally. The perceived view that Saudi Arabia has kept the taps turned to on to sink the US shale supply sounds too simplistic. Why shoot yourself in the foot to close down one new source of supply when they have not done this on previous occasions when facing similar threats? A more likely theory to my mind is that they have decades of oil in the ground but see only a small time window before renewables, particularly solar, take a much larger share of the energy market. Ergo might as well pump for all you are worth today as in 10 years time no-one will want the stuff. There is increasing evidence that solar is at or near a tipping point and electric vehicles not that far behind.
Don't forget their arch enemy..Iran, they wish to turn the screw there as well.
Paul - I would like to endorse your comments on EBITDA, profits and capitalisation of development spend [and other, undisclosed, 'intangibles']. My heart sinks when I see 'EBITDA' (and worse still, 'adjusted' EBITDA - incidentally, I totally agree with your comments on adjustments too) quoted in updates instead of profit before tax. Companies with the confidence to distinguish themselves by declaring PBT in trading statements - and better still, including current and prior free cashflow - really set themselves apart from the pack.
In the unlikely event that any CEOs, FDs or PR people read Paul's report as far down as my comments please understand that Paul Scott speaks for thousands of private investors that are well aware of Paul's (and Charlie Munger and Warren Buffett's) views - his views on this are our views too: EBITDA does not fool us; and as Paul implies, it's very mention tweaks our sceptical nerves and sends us delving straight into the cashflow statement (if we haven't already thrown that company on our 'discard' pile).
Regards,
Ed Miller
@paraic84,
try this for a starter,
http://www.buyupside.com/etfs/oilgasetfsmain.php
regards
Re the opportunity in oil and gas: my main play on this is through the ETF 'SPOG' which provides exposure to large cap global companies involved in the exploration and production of oil and gas. For me this is a safer way of playing it without punting on one or two companies I don't understand and which may run into difficulties if they have dodgy balance sheets. The downside of this ETF is it doesn't pay out a dividend while you wait. I'd be interested to know if anyone knows of a ETF in this sector that does pay a dividend.
You might find this useful http://www.hl.co.uk/shares/shares-search-results/m/market-vectors-etf-trust-oil-services-etf. Once on the site I am sure you will have a lot to choose from but occasionally liquidity can be a problem but the fact sheet will help.
ANCR doesn't sell much to VETs directly as there are a few wholesalers in between, so any consolidation on margin is not going to happen or hit ANCR. The critical issue will be if the new pharmacy products can get into the market before someone else eats their lunch on pet tags RFI.
Given the quality of the management, I'd buy on the dips.
Paul
I hear you had a disagreement about Trakm8 Holdings (LON:TRAK) with Tom Winnifrith over on shareprophets yesterday. Are you willing to share your summary opinion here?
Shares have just gone up 20p.
And dropping back now, slowly. I suppose they must be illiquid. If the shorters find themselves squeezed, this could bounce.
Think its just the spread getting wider its now 15p was 5p earlier today, no trading recently.
I hear you had a disagreement about Trakm8 Holdings (LON:TRAK) with Tom Winnifrith over on shareprophets yesterday. Are you willing to share your summary opinion here?
FWIW I took a look at TRAK last night and decided the basher was wrong (but at least consistent with his terrible call on BOO). IMHO TRAK is a solid GARP share and I bought some this morning. I almost feel like a day trader seeing what the share price has done already...
Having done my research, I would now like the basher to bash some more as I would like my next buy to be sub 200p. Thanks in advance. Si.
Hi Paul,
Have you looked at the US oil ETF compared with the actual price of oil?
i.e. $xoi:$wtic
it was last this high in 1999! something has to give, and seem as the price of oil itself doesn't look like trippling anytime soon I guess to get back to some mean level the price of the oil equities has to give.
My guess is that the US shale providers will be first to go, share price wise, then who knows....
just food for thought.
regards
mrwhits.
Re oil, the thing is the low cost producers could supply the entire world demand for decades at say $20 from their known reserves. Whether they decide to do so, I know not, but they can, so there's a risk they keep the prices low longer than most people can stay solvent (or alive). Most high cost oil still seems to be priced for a quick rebound (2-3 years?), which would be pretty unusual compared to historical commodity cycles.
Besides there's a risk of obsolescence, oil is really a one-trick pony: it's mostly only good for transport (all other uses put together are like <20% of consumption) so if any one of the cleaner propulsion technologies reaches parity (net of politics), it will be the next coal.
Finally, from a simple boom-and-bust cycle psychology viewpoint, how often is the generational opportunity when everybody is shouting "generational opportunity"?
Paul, good morning.
Two points of interest relating to Animalcare ( i hold their shares).
You drew attention to the possible buying power of the larger veterinary groups.that are now emerging. The CVS Group has a division entitled MiVet, which is a veterinary buying group enabling private practices to buy at prices negotiated by the Group. This is likely to have some impact on Animalcare's margins.
I was also concerned to note that their income from animal micro-chipping, which represents 17% of their revenue, was down 5.2% last year. This has been good margin work for Amimalcare. From 6th April this year compulsory micro-chipping will be introduced and lots of firms are getting in on the act, cutting the margins for Anim alcare.
I still like the company but their margins will need to be watched.
I have no doubt that the buying power of the likes of CVS and Pets at Home will put the squeeze on Animalcare.
Hi Paul,
I've been keeping an eye on oil services companies rather than producers. Particularly Lamprell, and John Wood. The Blackrock World Mining and Commodity Income investment trusts are also looking interesting. I would prefer to spread the risk by investing in one of these rather than individual oil producers.
BW
Hederz
I think oil will come back eventually although there will be increasing competition from new technologies and increased efficiency of usage. However I personally wouldn't assume ANYTHING.
By a strange coincidence I got my weekly free chart this morning, which is always interesting
http://www.chartoftheday.com/20160121.htm?H .
It's in my beloved log scale and we forget that, as it says, the oil price is now, only the same as 12 yrs ago. 16yrs ago it was only around $12 per barrel! Perhaps the HIGH price was the aberration and we are just heading back to normality.... but absolutely NO one can foresee the future...otherwise we'd all be rich! :) Just remember that the most highly trained academics and economists disagree on most things..... so logically our guess is as good as theirs even without their training! :)
Paul,
Great interview with SOM. Thanks for taking the time to do it, it's genuinely appreciated.
I share your view about the current pessimism, particularly if your buying UK based consumer facing stocks. Everything has got nailed in the sell off and I'm buying some more CAMB this morning. Of course things could change but it seems the market is missing the fact that UK employment is the highest since 1971:
http://www.ft.com/fastft/2016/01/20/uk-employment-...
Something doesn't add up to me. I believe the market needed to blow off a bit of froth but that's it, So I'm taking advantage where good quality companies have been hit too hard. I'm also dripping some money into oil companies such as XOM, CNE & OPHR.
I spent a few hours researching TRAK last night. I can't believe people were paying £4 for it quite recently but at £2 it looks like a bargain - a good quality company with good management.
All the best, Si
Si,
I couldn't agree more - it doesn't add up there is too much pessimism especially around UK consumer facing stocks. Guess they are two ways of looking at economic situation (see my conversation with herbie47 yesterday) and nobody knows which way the markets will go. I risked catching the falling knife earlier this morning with small top ups on Cambria Automobiles (LON:CAMB) and International Greetings (LON:IGR) both with high Stockopedia rankings and recent very bullish trading updates (in the last week!) but the knife kept on falling and they are both down another 5% so far today making it around a 20% fall since the new year. Just as well I am in it for the long term but the way things are going at the moment to quote Keynes 'in the long run we are all dead' !!!
Paul,
Are you able to advise please which stocks fall into your stated category of "financially strong, low cost oil producers"? Is this the likes of BP, Shell... etc.?
Regards,
Andrea
P.S. I see there are some large sell trades going through for SOM today... though price not moving much.
Hi andrea,
As I mentioned in the article, I don't really want to get drawn into saying which oil shares I'm buying, as it's not an area where I have any expertise or competitive advantage.
So your ideas are as good as (or better maybe!) than mine. I should probably just buy an oil ETF and be done with it. But stock-picking is such fun, especially when it works out well!
Regards, Paul.
Hi Paul,
Given your retail expertise, do you have a view on Halfords' results?