Small Cap Value Report (22 Dec 2016) - HSS, HSP, KOOV, WJG

Good morning! Paul is off today, so there's no need to look for a Part 2.
 HSS Hire (LON:HSS)
No. shares: 154.8m
Market cap: £130m
Fair dues to Paul for noting that he saw no alternative to an equity fundraising at this equipment hire company (link here - and thanks to a reader for pointing out this was as far back as November 2015!).
I've also written bearishly on this company before, and have been surprised to see the share price remain somewhat resilient over the past year.
However, this potential placing is much smaller than the amount which I and perhaps others would have viewed as necessary to fix the balance sheet. I suppose bulls might interpret it as a message, from the two institutions taking part, that the hole in the balance sheet is not so large
Shares are up a little bit on the news, so perhaps the placing is being seen as a good show of support from the private equity/hedge fund owners (who will own c.76% of the company after the deal, up from 73.4%).
Rationale:
The scale and complexity of the programme (including
£12.5 million of previously announced one-off costs for the nine month
period ended 1 October 2016), together with the on-going investment to
support revenue growth, has led the Board to conclude that an equity
injection would strengthen the balance sheet of the Group and provide
additional flexibility to fund fleet investment as it completes the
change programme in early 2017.
The programme being referred to involves the use of a new "National Distribution and Engineering Centre", which is supposed to transform how the company operates. Implementing change across the business is taking slightly longer than expected (forecast until Q1 2017 rather than by the end of 2016).
My opinion: It's interesting that the owners are willing to pour some more money into this, albeit just a fraction of the value of their existing holdings. They must be convinced that the next 2-3 years, at least, could turn out in a reasonable way for them.
For those of us on the outside looking in, in my opinion, it's not a transformational deal and it is quite possibly a sign of things to come - dilutive equity injections to keep the company ticking over in the short-term.
Net debt at the start of October was £240 million, which had increased despite the company stating at the interims that net debt was expected to reduce in H2 (from £239 million). This was blamed on exceptional costs.
Most of the debt is in the form of senior secured notes, carrying an annual interest bill of £9 million and maturing in 2019. On top of that there is c. £100 million of bank debt.
Using the company's preferred measure of "adjusted EBITA", ignoring all of the necessary reinvestment and exceptional costs, I can see it making its interest payments - I just don't see much value in excess of that, for equity holders.
Throw in the reinvestment needs of the business and the exceptional costs, and the refinancing risk as 2019 gradually approaches, and it looks highly unappealing to me.
Share price: 232.5p (+6%)
No. shares: 31.9m
Market cap: £74m
Post-Close Trading Update (six months ended 30 November 2016)
This unusual coal-support services-property group looks to have reached a position of stability and relative confidence, after years of turmoil:
The Group has experienced more stable trading
conditions during the period with underlying Group profits for the six
months expected to be in line with management expectations. Hargreaves
anticipates a strong second half with expected outperformance in Coal
Distribution and Property & Energy that will more than offset the
impact of the expected contract delays in Industrial Services.
So it's a boost to the outlook for the full year.
Interestingly, it's the Coal division which is leading the expected improvement (not the Industrial division), as a consequence of higher demand for coal and higher prices.
Legacy issues appear to be under control:
Management remain pleased with the rate of conversion of legacy assets into cash. As reported in October the Group's existing coal stocks have been sold and we continue to expect the full recovery of loans to the Tower joint venture. Working capital performance across the Group also remains in line with expectations. The Group is currently targeting to close the financial year with less than £5m of net debt.
(the next section of text was wiped out by an accident and what follows is a rewrite)
My opinion: I think there is possibly still further upside to be had here, as there are both balance sheet and earnings-related reasons for optimism!
On the balance sheet, the Property division is looking to create £35 - £50 million of incremental value from various property and energy assets. This would add to the company's last-reported tangible net asset value of c. £120 million (May 2016).
On the earnings side of the equation, the Coal division is amazingly still profitable but the Industrial division is also seeking to generate £10 - £15 million of operating earnings per annum in the medium-term.
All of this is much easier said than done, of course, but achievements so far would suggest that we are dealing with a credible management team here.
Share price: 48p (-9%)
No. shares: 175.4m
Market cap: £84m
Interim Results (six months to 30 September 2016)
I wouldn't normally cover this, since it operates in India, is listed on AIM, and has been publicly quoted here for less than three years - that puts it outside my personal risk tolerance levels automatically!
But it has been mentioned on the SCVR pages before so I'll briefly show the results:
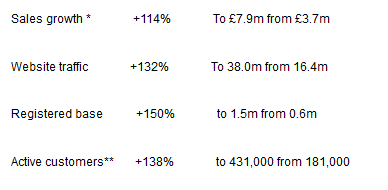
Huge growth numbers but as Paul would point out, it is still at an early stage of development. In Mt. Everest terms, it's still not far from Base Camp!
I do like the fact that it promotes its own label. With private label collections at a healthy 40% of all sales, that makes it a lot more than just an ordinary internet-based distributor.
Financial results:
A loss in the six month period of £9.1 million, significantly worse than the £5.7 million loss recorded in the same period last year.
Closing net cash was £7.7 million, and it raised a further £12.9 million last month. So it should have enough to get to the end of this financial year, at least.
My opinion:
I don't understand why the company is operating at a negative gross margin of minus 20%.
To test the business model for future success, shouldn't it at least have the discipline to ensure a positive margin on sales? Anybody can buy something and sell it for 20% less than it costs to produce, surely?
I couldn't possibly buy into a retailer with a gross margin like this, so it's not for me.
Watkin Jones (LON:WJG)
Share price: 117p (unch.)No. shares: 255.3m
Market cap: £301m
An upbeat RNS from this construction and development company:
In summary, it has:
- Forward sold student accommodation on Stratford High Street (Duncan House) for an undisclosed fee.
- Received planning consents for three developments, two in Aberdeen and one in Sheffield.
- Sold its Athena Hall development in Ipswich for an undisclosed amount. A subsidiary of Watkin Jones will continue to manage it for the new owner.
Despite the lack of precise financial figures, protecting the commercial sensitivity of these various deals, the numbers of student beds help us to understand their potential size.
- Stratford: 511 beds.
- Aberdeen/Sheffield: 1360.
- Ipswich: 590.
Note that the first two developments include substantial commercial/educational space in addition to student accommodation.
Ahead of the 2016/2017 academic year, the company delivered 3,819 beds in total. So the deals announced today involving 2,461 beds are certainly material.
CEO comment:
The planning consents granted for Pittodrie Street and Caledon House are exciting as Aberdeen is an important contributor to the knowledge economy in Scotland, with two universities and approximately 21,000 full time students, and there is a recognised need for purpose built student accommodation in the city. The redevelopment of Rockingham Street in Sheffield provides us with an opportunity to further extend our reach in this important University city.
"With the forward sale of the student accommodation development at Duncan House now completed we can concentrate on the construction phase of this significant development, which will serve the University of London when completed in the summer of 2019. We expect the Duncan House development to make an important contribution to our earnings over the next three years.
My opinion:
Stockopedia quite likes this share, and it has a Stockrank of 80.
Here are the growth and value stats:
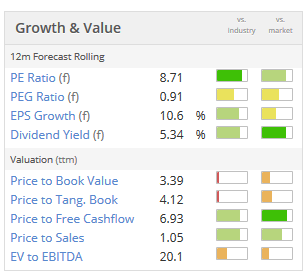
While the shares are cheaper than the market a whole in PE terms, the level of risk here needs to be considered.
Think of visibility, as described in the trading statement last month:
The Group continues to add sites to its strong development pipeline and, at 30 September 2016, it had a total of 21 developments with 6,814 beds targeted for delivery during 2017 and 2018.
The Group's pipeline beyond 2018 is also looking robust with over 2,000 beds across a number of sites already secured.
While these numbers do suggest that the company deserves its currently positive growth outlook, there is a lot of potential variance when we are talking about an average of 10-12 developments per year.
Because of this variance, I think it's important that the shares are priced in such a way that investors do get adequately (i.e. richly) rewarded, if or when the developments succeed. So on that basis, I'd argue that the current share price is probably not far wrong!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Re WJG, FT on Monday mentioned a recent EY report under the heading "Key UK university towns near ‘saturation point’ with student homes". The article seems to be available without an FT subscription https://www.ft.com/content/fdf1a7ec-c302-11e6-9bca-2b93a6856354 but i haven't tracked down the full EY report.
Although it may be superficially appealing to compare Watkin Jones (LON:WJG) to Unite (LON:UTG) simply because they both operate in the student accommodation sector, I think there are some critical differences:
To me, there are significant differences in their operating models and I think Watkin Jones (LON:WJG) is by far the more attractive investment proposition.
Brilliant analysis. Do you think it would be fair to suggest that this will give Watkin Jones (LON:WJG) an advantage whilst the market is bouyant and growing but might leave them a little exposed if the market goes quieter for some reason?
Thank you, although much of what I wrote was merely synthesising what I have read elsewhere on the internet.
I think being debt free and asset light is always an advantage. This applies even more so in a downturn so I think they will be less exposed than the likes of Unite (LON:UTG) or general property companies when the next downturn does arrive.
However I would make three further points:
Firstly, as property development is their main income stream, they do depend on identifying a continuous pipeline of development opportunities each year. Yes this could dry up in a downturn and on this specific point they are in direct competition with Unite (LON:UTG). It's why I would like to see Watkin Jones (LON:WJG) growing the property management side of the business as that provides regular recurring, and high margin, income. However my feeling is that Watkin Jones (LON:WJG) is less exposed to a downturn compared to the wider property market because (as I alluded to in an earlier post) there are different dynamics in play in the student accommodation sector - mainly chronic undersupply and the interplay with the private rented sector and local authorities.
Secondly, in a downturn other property companies may not be able to take advantage of new sites becoming available because they are unable to finance their construction. This could play into the hands of Watkin Jones (LON:WJG) given their different operating model.
Finally, and as this very thread demonstrates, I think there is a fair amount of misunderstanding of Watkin Jones (LON:WJG) 's operating model, not least because they are a new IPO and I am not aware of any other directly comparable listed competitors. That's why it's easy to dismiss them as just another Unite (LON:UTG) whereas the reality is somewhat different.
All of this suggests to me that Mr Market is currently presenting a buying opportunity in Watkin Jones (LON:WJG), but as ever DYOR etc. I could be wildly wrong with my thinking, it has been known before!
Thought I'd add a few comments as I very much like this sector; Unite Group UTG is my largest single investment. I also like the look of WJG but prefer Unite's asset backing and frankly I'm fully invested in this sector.
Firstly, the idea that the student accommodation market is becoming saturated is very difficult to believe. The number of new students has been rising faster than the accommodation is being built. Last year 25,000 beds were added but student numbers increased by 60,000. Also, there were 180,000 more applicants than places in 2015/16. The future is uncertain of course but it would take a major disruption to significantly affect this market - which is one of its major attractions. It was the best performing property asset class throughout the Global Economic Crisis.
UTG also has a development pipeline of 5,500 beds but will be adding them to its wholly owned or partially owned student property portfolios (98% occupancy 16/17 ac yr) . It is very conservatively financed with a LTV of only 36% and as at 30th June its NAV (independently valued) was 620p versus a current sp of 593p.
So with a solid market underpinning, asset backed, and transparent future growth trajectory - it's a very boring investment. Which is probably why I'm talking to myself on Advfn where I mostly post http://uk.advfn.com/cmn/fbb/thread.php3?id=16292632&from=520.
Regards and Happy New Year, Maddox
RE: Watkin Jones and student property over-supply.
I don't hold WJG but do hold Empiric (ESP) another student property company but with a different business model. They (ESP) appear to have no problem pre-letting their rooms with very high occupancy rates. Also they regularly point out that a large proportion of (their) students are not from the UK or EU therefore Brexit is of little concern but the week pound does potentially reduces foreign students fees, accomodation costs etc. making the UK a cheaper place to study.
Dennis.
Also they regularly point out that a large proportion of (their) students are not from the UK or EU therefore Brexit is of little concern
But the Brexit related pressure on immigration is finding it's way through to the easy option of cutting foreign (non EU) student visas, and that is likely to impact - a lot of higher end student accommodation is let to overseas students. It's also economically illiterate for a country one of whose major foreign currency earners is education, but that's another discussion.
Peter
My longer term reason for being interested in Watkin Jones (LON:WJG) is the potential to extend their development model beyond student housing into the wider rental market. There seems a lot of potential to me for them to work with their current slate of institutions who are seeking alternative sources of income. Now that students are burdened with so much debt on graduation they are mostly forced into renting for years rather than buying a place of their own and I am seeing some city centre developments come to market that are essentially adult versions of halls of residence.
My small Watkins Jones holding hasn't done much but I'm keeping it for now to keep myself interested in the way the market develops.
Thank you to the posters who put me right over the ownership and sale of the plane, also to aflash who brought to my attention UTG which seems to be the closest comparative. I do feel that watkins Jones has been brought to the market at just the right time for the owners but you cannot blame them for that can you?
In the real world, the difference between advice and opinion by Paul is a matter of semantics. Clearly he is giving tips/advice and indeed on occasion when I know there is a share he is fond of I shall occasionally buy it ahead of his comments published here if it is a small cap and the share price not risen a great deal follwoing an RNS release. Then he publishes and a few hours later I sell after a small price rise.
The reason why it has to be advertised as 'advice' or not a 'tip' is a legal one to protect himself and Stockopedia.
If SCVR was purely about education then there would be no need whatsoever to choose shares that issue an RNS on the day; could easily comment about a share that issued an RNS months ago or just omit the name of the company all together, to achieve the same purpose. But then that would hurt the commercial viability of Stockopedia.
There is definite value in his explanation and views about how a company presents its information.
The sooner the better this fallacy of not being a tipster is dropped the better. Same goes for a number of other commentators.
Carcosa,
That's not how I see things at all (post 27).
I'm giving a personal opinion on company results & trading updates. The emphasis here is on people doing their own research, and hopefully my articles may well be of use to people in flagging up interesting companies, and avoiding dodgy companies.
However, I'm absolutely not giving buy or sell recommendations. I don't want to do that - because it's completely wrong as a concept. People should be researching companies in depth themselves, not blindly following tipsters. I deplore the whole concept of magazines & bloggers putting buy or sell recommendations on shares - that's completely wrong - because it encourages people to punt on things, instead of doing proper investing & taking responsibility for their own investments.
We could give recommendations here if we wanted to - other websites do, and rely on the journalistic override that allows such tipping. However, none of us here at Stocko want to do that. Instead we like producing articles that stimulate thought, and debate.
I'm very much against people blindly following me into shares. Although I can't control what people do, so am not going to get too stressed about it either way.
Paul.
Hi Epson
Watkin Jones (LON:WJG)
If true, it may not be a big thing, but I thought I'd look anyway. However I don't have an ADVFN login (yeh, I know), so I can't see the post. Therefore I thought I'd look for a secondary source of the information. I could not find anything on Google, including the following search strings (and others)...
+"watkins jones" +airplane
site:watkinjones.com airplane
Does the ADVFN post give a source?
Thanks.
Hi Lion Tamer,
Watkin Jones (LON:WJG) aeroplane is mentioned in the admission document, see http://www.watkinjonesplc.com/results-centre/key-corporate-documents. From that it was purchased prior to 1st October 2012 for a smidge over £3.3m and had been depreciated by £432k by 30/09/2015.
It's not mentioned specifically in the recent interim results but looks to me like it has been rolled up within Property, plant and equipment in non-current assets.
Simon.
Yes, the Watkin Jones (LON:WJG) aircraft is mentioned in the admission document, but it says it will be sold!
Page 121:
"9.18 Proposed Sale of Aircraft. Saxonhenge Limited, a member of the Group, will, prior to the end of
the current financial year, sell its aircraft to a new company to be incorporated by Mark Watkin Jones,
at its book value. The Group may, following such transfer, charter this aircraft on arms-length terms.
Planehouse Limited, the landlord in respect of a hangar at Caernarfon Airport that is leased to Watkin
Jones & Son Limited (as described in paragraph 9.12.3 of this Part V), shall surrender the lease of
this hangar, for nil cost to the Group, on the transfer of such aircraft."
I have a modest holding.
Thanks Simon!
I'm not a holder of WJG looks a good company, but what put me off was the company aeroplane which I read of on this thread post 47, http://uk.advfn.com/cmn/fbb/thread.php3?id=35318049&from=1&to=435 it's not just the £3m cost (which doe's seem excessive for a small AIM listed company) as much as the directors attitude to company money.
Hi folks, you're all probably right. I can see a lot of merit in what they are doing and how they are doing it. It's a close call for me either way. I was probably in profit when I decided to come out and that may have swayed my decision (it doesn't happen very often!)
I agree with bestace and timarr that Watkin Jones (LON:WJG) should be valued on earnings power, not book value. It's not buying to collect rent like a property investment company, it's buying to build/improve and then to sell! And sometimes to provide management services afterwards. So the P/E is relevant and the P/B much less so.
But I do wonder if the the market for student accommodation might not become oversupplied in the next few years, cutting off development opportunities for Watkin Jones (LON:WJG). Even if it took 5-6 years for this to happen, it could make all prior applications of earnings multiples redundant (since there would no way to produce 4,000+ beds at the prior rates of return). Some companies in the building sector have a nasty habit of looking the cheapest when they are the most overvalued, after all.
Just my opinion, DYOR etc.
I think the shortage of student accommodation is so chronic that it would take a massive drop in student numbers to make a material difference to the likes of Watkin Jones (LON:WJG). It may happen, given the unknown impact of Brexit among other things, but another driver is that whenever purpose built student accommodation is completed, it frees up housing stock from the private rented sector for non students. This is clearly beneficial given the pressures on housing in this country, and as a result I think the market dynamics for the student accommodation sector are a bit different to those for the general construction sector as a whole.
Hi Graham
Yes, the potential oversupply of student properties is something I have wondered about. With relatively recent IPO's it's always worth looking for the reason, but the significant stake held by the Watkin Jones family mitigates against the belief that the owners were looking for a quick exit.
But as bestace has remarked that's probably a long way off and even if it wasn't I think the business model could be modified to address the private market; the fundamental undersupply of property is not a problem that's going away. In addition the Fresh management business is an interesting operation in its own right, with gross margins at about 65% and the potential to double the number of rooms under management over the next three years.
As a holder I'm conscious that I'm putting the bull case here. The business depends on finding a constant flow of suitable locations and that the market for forward selling their properties holds up. Zeus are lyrical on the forward visibility but I think that could vanish in a severe downturn.
But I'm a great fan of family run businesses with a decent track record, and as Watkin Jones has been around since 1791 I think we can at least agree that it has longevity on its side :)
timarr
I do wonder if the the market for student accommodation might not become oversupplied in the next few years, cutting off development opportunities for Watkin Jones (LON:WJG). Even if it took 5-6 years for this to happen, it could make all prior applications of earnings multiples redundant (since there would no way to produce 4,000+ beds at the prior rates of return). Some companies in the building sector have a nasty habit of looking the cheapest when they are the most overvalued, after all.
If one compares it with UTG (Unite group) which has been involved with Student Accomodation for longer it seems we are at the top of the cycle. WJG cashed in on the trend. Since the spring of 2015 UTG has been trading at the top of its range. Nobody wanted it from July 2011 to July 2012.
The business models are similar but not the same. Nevertheless your point on oversupply is spot on.
Watch the piworld video www.piworld.co.uk/company-video.../watkin-jones-at-mello-1371
https://www.google.ca/url?sa=t&rct=j&q=&esrc=s&sou...
and Draw Your Own Conclusions
If Watkin Jones was valued at around TBV then it would be offering a yield of about 20%. That kind of yield only occurs when the company is about to cut its dividend but here we have a company that has net cash on the balance sheet and with highly visible forward earnings that cover the dividend about twice.
The point is that they're not a traditional property company at all, they forward sell much of their development and often end up with contracts to manage the properties once they're up and running through their Fresh subsidiary. Forward selling removes the assets from the balance sheet, hence the discrepancy on P/TB.
They had £15.4 million cash at the last interims, two months into the current year they have 65% of full year 2017 already locked up and Zeus are estimating £30 million in cash by the end of this year. The Watkin Jones family retain significant stakes in the company through family trusts. Whether you regard that as a good or bad thing is a personal choice, but I'm comfortable with it.
In short, it looks like a well managed company with a sensible business plan, with excellent earnings visibility and cash backing which offers a very decent yield. I rather like it, but thereagain I don't value it as a traditional property company.
timarr
I see that Petards (LON:PEG) announced a contract renewal with the MoD today worth £1.6m plus over 3 years. Unless I'm missing something, this share is so far under the radar that nobody seems to be keeping count of the contracts being won and the value that is being built here.
Disclosure - I am long Petards (LON:PEG)
From June 2013 to August 2016 it was chugging along at 15p. Since then it has been a vertical rise. You ARE missing something.
Hargreaves. They do seem to have struck a bit of good luck, combined with sound management. However, don't forget that the board's judgement has to be suspect as they authorised a £6.3m share buy-back at 598p about 2 years ago, thus wasting approaching £4m of cash.
dfs12 WJG is not a property company, it is a developer. It relies on successful developments, often pre-sold, for its profits, and does not hold properties for capital gain or rental income.. Suggest you look more closely at the business model before judging.
Thanks Graham for your review of WJG. Dfs12 - isn't the P/TB value explained by their business model of selling the the development up front and receiving cash for it on a monthly basis as it is built - ie it is their aim not to have properties on their balance sheet.
I held Watkin Jones (LON:WJG) up until recently and then changed my mind. The two things that put me off...
1. Its a recent IPO (so might suffer from persistent sellers over the medium term depressing the share price)
2. It has a price to tangible book ratio of over 4.
P/TB over 4 is very high for a property company. When you think about the value of a property firm it should usually be approximately equal to its underlying tangible book value (which will be dominated by land and property) - and that is assuming that there is no debt. A property firms other assets will probably be negligible compared to the land and property. And most real estate firms will hold their property assets on the balance sheet at a recent valuation. So the idea that the management or brand or anything else can make the real estate company worth a multiple of it's fundamental assets (on a recent valuation) seems pretty hard to believe.
If you look at almost all the other big real estate firms they trade at a P/TB of between 1 and 2. That seems a sensible range to me. A value of over 4 is a big warning sign that a fairly hefty drop in the share price could be possible.
Clearly this simple analysis could be completely misguided and it might turn out to be a star performer. Certainly when I looked into them I really liked the look of the outfit. Nice business model and team. And as far as I could see/remember there wasn't any private equity company involvement prior driving the IPO which has to be good news. Also a nice divi. So lots good. But the P/TB dominated in the end and I sold out.
Hi DFS12
Watkin Jones (LON:WJG)
I see WJG not so much as a pure property company, but as a manufacturer of investment products which it pre-sells to investment institutions, (with a much smaller property management company bolted on which I did not factor in for my decision). If the model works, it gets to operate with less capital invested in ongoing projects.
I'm a holder since Aug & only with a cautiously modest holding. Might top up sometime all things being equal or better.
Paul's comments on HSS were 13 months ago not last month.
There seems to be a rerating of HSS as they have gone up around 80% since then.
Paul pointed to Lavendon Group as a better bet and I fortunately followed his advice.
Thanks very much, I've fixed the HSS comment.
I don't think Paul ever gives "advice"; he merely offers an opinion.
RE: KOOVS : It was exactly what I was thinking. They are selling products on loss to simulate growth in sales.
This "company" is a bad joke.
Morning Graham,
Thanks for covering today.
Without pre-empting your section on Koovs (LON:KOOV) I thought their interims today were dire. Although apparently in line with expectations. A broker note this morning says don't expect breakeven until 2020! It amazes me that punters are prepared to completely ignore diabolical financial performance since it started. Instead they focus on the story - of a booming middle class in India, and fast growth (from a tiny starting point any level of growth looks good!).
Internet disrupters is one of my favourite (and most profitable!) themes at the moment. However one does need to be selective. There are only a few which make it to profitability & great success. The vast majority fall by the wayside. Judging on its performance to date, I think Koovs is very likely to fall by the wayside at some point - when punters tire of pouring money in, to finance its losses. At the very least, there's probably a lot more dilution coming, to make good the ongoing heavy losses.
Happy Christmas to all!
Regards, Paul.
Hi Graham, will you be reviewing Watkin Jones (LON:WJG) today? I thought they put out a cracking news update this morning and the share price hasn't budged at all. Still on a PE below 10 and a 5%+ dividend yield.
DYOR etc.
Hi bestace, I've had a look at it now, thanks for the suggestion.
Thanks Graham, much appreciated.
In response to dfs12's point, and as others have pointed out I don't think Watkin Jones (LON:WJG) can be lumped in with other property companies because they forward sell the properties before constructing them. The properties are not held in their books as fixed assets valued at open market rates, but are instead shown as 'work in progress', or inventories and valued at cost.
The forward selling model is also why I'm less concerned about visibility of future income. Yes it's possible that construction timescales on a project could slip, but revenue is recognised on a monthly basis as construction progresses so a slippage doesn't mean the whole project has fallen through. Granted, there are penalties involved for slippages, particularly where they have been aiming for project completions prior to the start of an academic year, but they seem to have an excellent record in completing projects on time and within budget.
Also, for the next couple of years at least, a large proportion of forecast revenues are already 'in the bag' from projects previously forward sold and on schedule for completion. Just as there are some downside risks, the relatively low number of projects each year means there are also upside risks for future years if they can identify more sites for sale than are in the current forecasts.