Small Cap Value Report (25 Nov 2015) - VP., HSS

Good morning!
The Chancellor's Autumn Statement is due to be announced shortly, so I expect all eyes are on that.
It wasn't possible to write a report yesterday unfortunately, but I'll circle back to those announcements later this week, as we don't want gaps in the sequence.
There are a couple of equipment hire companies reporting today, so let's start with those.
VP (LON:VP.)
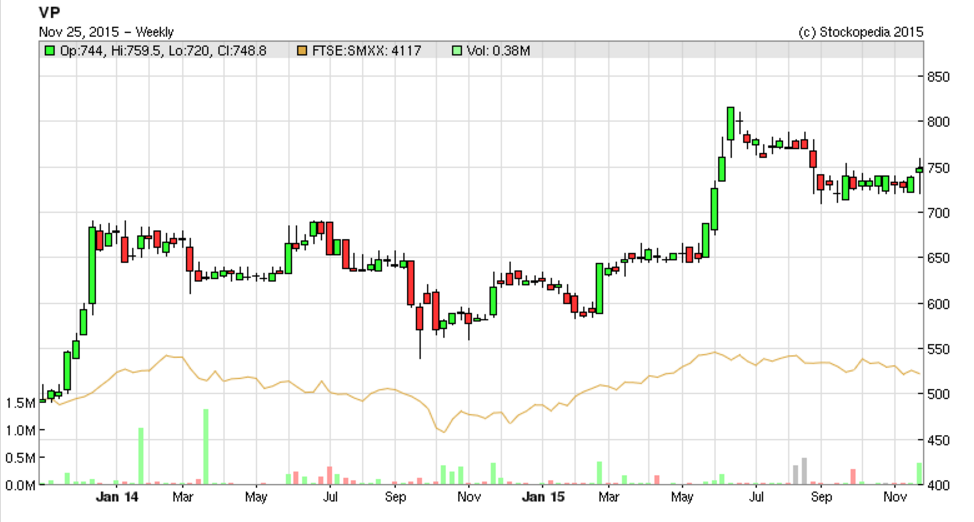
Share price: 749p (up 4% today)
No. shares: 40.2m
Market cap: £301.1m
Interim results to 30 Sep 2015 - the headline figures here look solid, rather than exciting. Key numbers being;
- Revenues up 4% to £105.1m for the six months
- Profit before tax & amortisation up 6% to £17.2m (I'm happy to accept this as an accurate performance measure, as the amortisation charge is non-cash, and immaterial anyway)
- Headline EPS is also shown pre-amortisation, and rose 7% to 35.14p
Judging from last year's results, there seems to be a trading bias towards H1, and the full year broker forecast seems to confirm this, with 54.4p forecast for y/e 31 Mar 2016, assuming that forecasts are prepared on the same basis that the company reports.
This seasonality makes sense, since there's more outdoor construction & maintenance activity over the spring & summer, than over the winter.
On reading the divisional breakdown, it's clear that most parts of the business are doing better than the headline figures suggest. UK Forks and Hire Station did very well, with profits up 25% and 27% respectively. However, two smaller divisions performed poorly, in particular Airpac Bukom (impacted by the O&G sector slowdown), and TPA, where profit more than halved.
So assuming the problem divisions (which are relatively small) can be turned around (all are still profitable, so no basket cases), then there is reason for optimism perhaps. I like shares where strong performance is temporarily obscured by fixable problems at a particular division, as that can allow a decent value entry point.
Outlook - this sounds reasonably encouraging;
This period has once again demonstrated the Group's ability to deliver good results even when some of our markets are performing at less than full capacity. This continues the excellent progress delivered over previous years.
We see opportunity across all divisional segments in Vp and will continue to deploy our robust financial strength to deliver further value growth to our shareholders.The Board has every reason to believe that the Group will be in a position to deliver a very satisfactory result for the year as a whole.
I think they are trying to say that they're likely to be in line with, or maybe a bit above market expectations, but that's my interpretation. I sometimes wish companies would just tell it like it is, instead of finding carefully constructed words which give them wiggle room, but frustrate readers, who have to work out how to interpret those words.
Valuation - looks reasonable on a PER basis, but quite high on a price to NTAV - which is usually about 2 times for equipment hire companies, so at 4 times, this is looking a bit warm.
There again, this company seems to sweat its assets well, so it might well deserve such a premium.
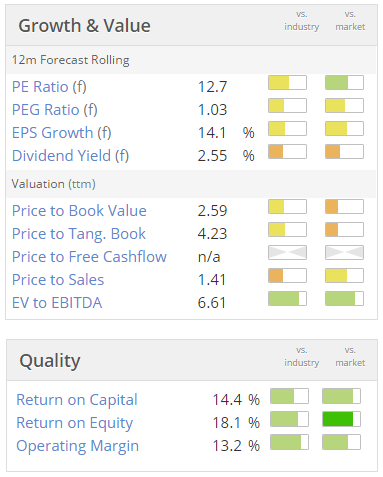
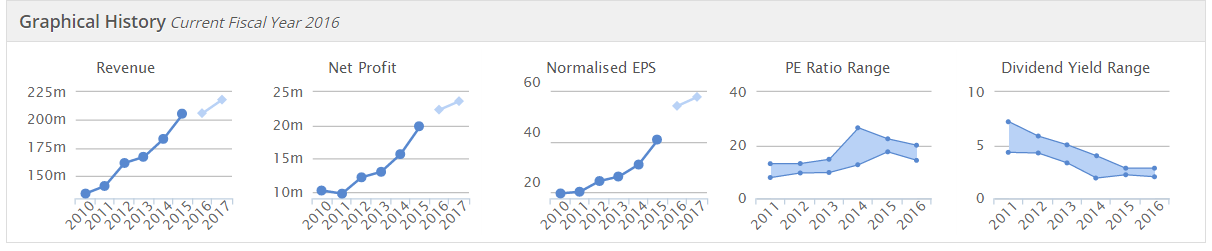
The big question is where are we in the cycle? If we're near the top, then the valuation should now be moderating, to factor in future declines in earnings. If we're not near the top of the cycle, then the valuation could still have further scope to rise.
Remember that hire companies are benefiting from ultra low interest rates, as they carry a fair bit of debt, so they should be making hay in the current environment.
I note from the cashflow statement that there were substantial share purchases by the employee trust, so the accounting treatment of that needs to be investigated.
HSS Hire (LON:HSS)
Share price: 46.8p (up 1.1% today)
No. shares: 154.8m
Market cap: £72.4m
Great caution is needed with this share, in my opinion, as it was subjected to the scourge of Private Equity, thus loaded up with debt, and floated on the Stock Market at an excessive valuation, still with way too much debt remaining, and issued a profit warning just months after the IPO. A truly appalling sequence of events, that surely must put off investors altogether from even considering taking part in any future IPOs from PE? This certainly isn't an isolated case either. I would say that PE floats would make an ideal starting point if you're looking for shares to short.
I last reported on its interim figures & profit warning here. Re-reading that article has reminded me that the company has a weak balance sheet (NTAV is negative), and too much, expensive debt. So caution is needed when the company mentioned EBITDA and EBITA, as there's a hefty interest charge to come off those numbers.
Trading update - covering the 39 weeks to 26 Sep 2015. Adjusted EBITA of £13.8m for Q1-Q3 may sound reasonable, but interest costs will eliminate most of that, so there's in reality little overall profit being generated.
Net debt - is now £210.4m . I don't see any alternative to an equity fundraising here, to reduce excessive debt, and de-risk the balance sheet. No doubt that will be done in a discounted Placing at some point, which private shareholders will be excluded from probably. That gives us little incentive to consider buying the shares now.
My opinion - I'll need to look at the latest broker notes, to ascertain whether there's a trading opportunity here, to buy the shares for a quick punt on a bounce? The general tone of today's announcement appears to suggest that conditions are stabilising, and that there might be a recovery play here, given that the shares are now down a staggering 78% from the IPO price
Although the poor balance sheet means it could only be seen as a high risk share, and certainly not a long term hold, due to the excessive debt, and inadequate equity on the balance sheet. That said, we're in a parallel universe right now, where highly indebted companies are allowed to continue trading, so who knows, everything might turn out fine in the long run?
I'm tempted to have a nibble, but have been catching too many falling knives lately, so on reflection it might be best to avoid it!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

13 comments
Hi Paul -
The following comments are not a put-down on Boohoo.Com (LON:BOO) but purely observations:
- "never fall in love with a share" is something often quoted by the investment gurus. It affects your judgement.
- As a general rule a strong charismatic leader in charge of a plc is to me a red flag. I used to think otherwise but recent AIM fiascos have made me change my mind.
Just my view, to echo your final comment.
Regards, Ram
It also sounds as if they need to spend some of that £60m on ensuring their prize asset, i.e. the website is rock solid AND not vulnerable to cyber attackers who can extort them by using such strategies as distributed denial of service attacks.
Can you imagine how damaging it would be to their business to lose the website for days or even weeks?
A security consultant was asked to look at the Talk Talk website after recent security 'improvements' and indicated that there were still vulnerabilities.
I'm sure these attacks happen frequently but large companies just don't publish the details for fear of reputational damage.
Best of luck to all holders
Phil
DDOS is not that hard a problem, you can rent a defensive front end on demand, probably takes an hour to setup (DNS-level switch).
It seems they already use a third party vendor (venda.com) to run the customer facing website anyway, who should take care of this. This is good practice: they're not an IT company, so it's good they outsource that.
Well that said ... where you website is your business it becomes critical to your success ... therefore any down time is a disaster. The fact that it fell over when Paul was on a visit ... perhaps 3 hours (edit: I mean Paul was there perhaps for 3 hours)? ... would tend to suggest that the infrastructure (whoever is providing it) is not as robust as it might be.
Hopefully some comment on CAMB to come...
NI
Thanks martinthebrave. I saw that on the BOO ADVFN board as well. Could be a decent short term boost. Longer term I'm not sure how good that will be for the company.
NI
When I was visting the Boohoo.Com (LON:BOO) HQ a few weeks ago, the ground floor area was mainly set out for the wholesale operation - i.e. selling to the likes of ASOS and NEXT. They seemed pretty busy, but nearly everyone took time out to have a chat to me, as they all remembered me from my days at Pilot (which I left in 2002). Apart from the expected rib-tickling (asking me if I had brought any PD cheques - I used to run Pilot on post-dated cheques basically in the 1990s), but it was more serious because Pilot went bust in 2005, 3 years after I left, and Pinstripe (the predecessor company of BooHoo) was one of, if not the biggest creditor - they lost over £1m on a bad debt to Pilot. When I heard about this, I was devastated, as I knew what a reliable and decent supplier they had been so before I visited, I made sure that (a) I wasn't going to get knee-capped, and (b) that they understood I had left Pilot long before financial problems emerged.
Ask yourself this - would you roll out the red carpet for a former FD of a customer who had stuffed you with a bad debt of £1m? Well that's exactly what BooHoo did - they couldn't have been nicer to me, and I was amazed at how many people in the building remembered me from my days at Pilot in the 1990s.
I said to the CEO, Mahmud Kamami, as we went round the building, I said "You know what BooHoo is?". He replied, "What?". I said, "It's Pilot online" - expecting him to shoot me down, and say how much better it is. You know what he replied? He said, "That's EXACTLY what it is! You boys could have done this, if you'd just had £5m cash in the bank, and worked out that online is where it's at. Instead you went bust, because you didn't have any cash in the bank! That was your mistake. That's why I keep £60m cash in the bank now. We can survive anything that happens. You imagine if you'd done that".
He was right.
Also, I asked him about his office building being such a labyrinth, it's in 49-51 Dale Street, Manchester, the same address I used to send loads of paperwork in the 1990s, before we had email. I asked him, how do you find your way around? Mahmud replied, "Listen Paul, when you pay for it, you remember every ####ing inch! And you can put that in your ####ing blog, I don't care!"
That might put off some investors. For me, I loved it. That's the way the rag trade is - you want hands-on entrepreneurs, watching every penny. The website went down briefly when I was there too, which was fascinating - seeing how everyone reacted. The CEO remained calm, but clearly agitated. He largely ignored me until the website was back up again, as you would expect. But he was controlled, and polite, towards all staff, even the IT Director.
As we went round the building, the CEO acknowledged every single member of staff, with all responding with a nod, but not jumping to attention, just getting on with their work irrespective of the boss being around. So it's NOT an environment of fear at all, quite the opposite. It's a buzzing place, full of trendy 20-somethings, all with a common purpose - exactly what I wanted to see.
Mark my words, this business is really going places!
They can source, and can duck & dive, in a way that our buyers used to do at Pilot. Nobody else works that work these days in fashion. So BOO really has a big gap in the market to themselves, and they're so price competitive, and so good at sourcing, these guys will really do well in coming years - internationally, as well as UK. Wholesale, as well as retail.
Just my view. DYOR as usual.
Regards, Paul.
Paul,
Sounds like you had a great visit with Boohoo. Like you, I have a lot of time for the way the two CEO's run the company and I rather like Mahmud's straight-talking although it will not be everyone's cup of tea. As part of my research I read a great interview with him in the Telegraph which sealed it for me and I bought my first shares there and then.
I particularly like the level of control they have over every stage of the product right from design and manufacture through to marketing and the way the feedback loop is closed meaning the early stage processes can react very quickly to changing sales activity. I think Terry Smith would agree that's the sign of a "good business" although he'd never invest in anything where there is so much fierce competition.
The only thing I would take a slight issue with from your report is the comment about the cash. He has to remember now that Boohoo is a listed company and the cash is not all his! The company is throwing off cash now and there is a mandate for buybacks in place, so the cash on the books looks to all intents and purposes like excess cash and so a fair chunk of it to be handed back to shareholders rather than sat in the bank earning bugger all interest if they cannot find anything better to do with it than "rainy day" money.
All the best, Si
LVD is cheaper than VP on most measures so I can continue to prefer them as a play on construction.
HSS Hire (LON:HSS) can quote adjusted EBITDA and adjusted EBITA all it likes. The important figure is that net debt. Up to £210.4 million from £197.2 million in 3 months.
(Disclosure: Short HSS)
Boohoo range now available via the Next.co.uk website - http://www.next.co.uk/search?w=boohoo&filter=-brand:next#1_309.
Hi Paul
Thanks for the write up of VP (LON:VP.) I thought the results they issued this morning, were pretty good. I thought there may have been a read across to Lavendon (LON:LVD) where the share price has performed poorly in recent months, surprising since they issued a Trading Update last week which confirmed they were performing in line with market expectations. I guess the market has worries about their exposure in the Middle East, although they sounded encouraging about their performance in the Middle East.
Look forward to reading your comments about HSS Hire (LON:HSS) which I'm sure you'll cover.
Best wishes,
Imran.
Hi Paul
I hold a fair slug of VP and rate them as great LTBH stock , mgt are cautious and capable and appear to lack the hubris of many of their ostensibly similar peer group. If you can get the CEO to do one of your interviews it'd be very interesting. I think that a lot of their workload is maintenance driven and thus less cyclical and in any case they are not going to be too far out of step with the cycle that Waterman's CEO talks about...whose shares I also hold and whose RNS yesterday gave me a warm feeling too!
Cheers
Cheers