Small Cap Value Report (22 Jan) - NWKI, CLL, TSTL, CAR

Good morning. People seem to like the new format, with clickable (through to that company's StockReport) headers, so I shall do that every day from now on.
Also please note that I'm spending all morning writing these reports now, updating them about every hour from 8 a.m., so if you keep this page live in a tab on your browser, refreshing it from time to time will ensure you don't miss anything! The email goes out at noon (see sign up box below this article), but I might still be updating it until about 2 pm, depending on how much news there is each day.
Networkers International (LON:NWKI)
Recruitment group Networkers International (LON:NWKI) issues a trading update for the year ended 31 Dec 2013. It says that pre-exceptional profit before tax, and EPS should be in line with the Board's expectations (urgh, hate that phrase, why can't they say market expectations, like most other companies? We know what market expectations are, but the Board's expectations could be different, so it's a bit of a cop-out referring to the Board's expectations!).
Although they also note that Net Fee Income fell by 5% in 2013 (i.e. NFI = gross profit, which for recruiters is their fees excluding the wages paid to temporary workers, so it's the most meaningful measure of revenue the company has earned, as opposed to total revenue which includes the wages of the temps that they supply & hence recharge on to clients).
The reasons given for the fall in NFI are twofold - firstly that 2012 (surprisingly) was a record year, and secondly that there has been a (positive in my view) shift in NFI more towards permanent placements, as opposed to temps. I think that is positive because the profit margin is higher on permanent placements, whereas supplying temps is very competitive, with clients squeezing out profit margin by playing recruitment companies off against each other.
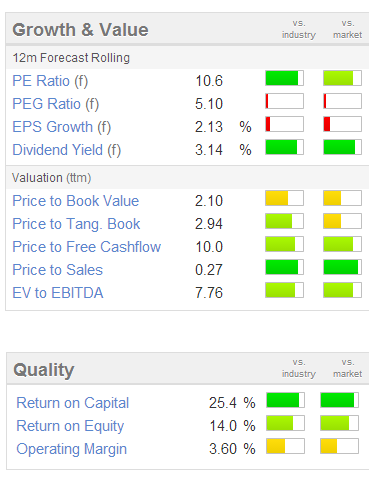 It's valued at a market cap of £41.2m, at 50.5p per share, which has enjoyed a re-rating of about 46% from the 34.5p low six months ago. Is there more in the tank? Quite possibly, as the forward PER is only 10.6, with a 3.14% dividend yield, and they carry little debt - today's statement says that the only debt is invoicing discounting (normal for recruitment companies) and reduced over 55% to £3m at the year end.
The fly in the ointment here is some litigation in the USA. This is the first I've heard about that, so it just shows how important it is to read the Annual Report & results statements very carefully. They have made an existing provision of £1.6m, and are making another £0.25m provision. This is a worry, and personally I wouldn't want to invest until this matter has been closed off.
Also, it's a worry that the company has allegedly violated laws governing employee conditions & payments. There could be a perfectly reasonable explanation, but I would want to ask some difficult questions before investing here, to ascertain whether the company just messed up, or deliberately violated laws in the hope of getting away with it? Also, what procedures have been put in place to ensure that this cannot happen again, and that the company complies with all relevant legislation in future?
There is more information in the 2012 Annual Report apparently, so I'll have a look at that when time permits. The outlook sounds positive, with the company saying today;
Whilst we are only in the early stages of the year, the Group has made a very encouraging start to 2014.
So if I can get comfort on the litigation issue, then these shares look potentially good value & worthy of further research in my opinion. As always I am NOT recommending any shares, just flagging up ideas for research that look interesting on an initial, cursory glance, which is all I have time to do here - hence further, deeper research is essential.
Edit: On reflection, maybe I'm worrying too much about the litigation issue here? It's been known about for a long time, and hence is probably discounted into the share price already. So I might dip my toe in here with a small purchase, given that the outlook statement uses the words "very encouraging" start to the new year, and the valuation looks good value to me. With the economy apparently improving quite strongly now too, recruiters should have a good year in 2014.
Cello (LON:CLL)
This marketing group issues a trading update for the year ended 31 Dec 2013. It looks good - the key point saying;
Strong trading for the year, revenues and headline profit before tax ahead of consensus market expectations
Various other positive points are listed, in particular I like that net debt has reduced below expected levels. Although as I reported on 18 Sep 2013, the Balance Sheet at Cello is weak, with net tangible assets being negative by £6.9m at the last reported date. Furthermore, they make lots of adjustments to profits, some of which are questionable. So overall, it's not for me, although I can see the attraction, especially after this positive update statement today. So it's a question of weighing up good trading, against a weak Balance Sheet.
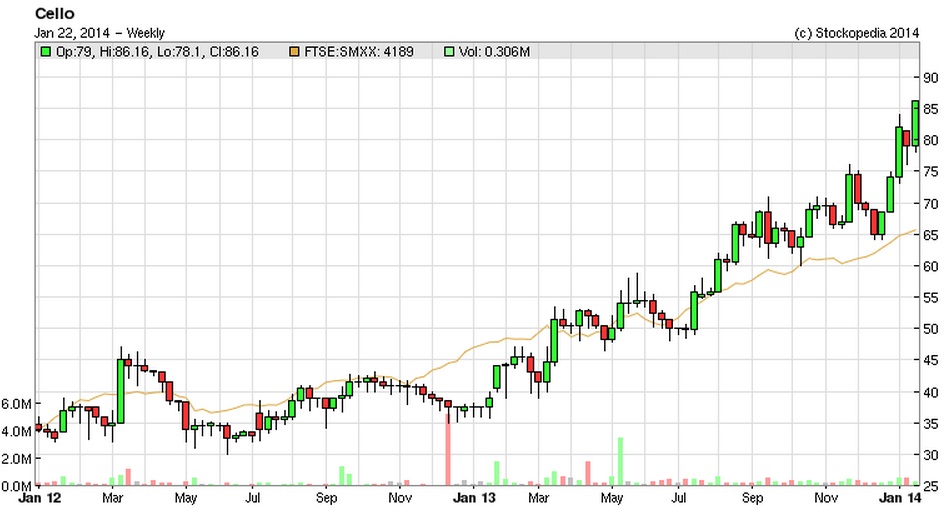
Their shares are up 9.5% this morning, so good news for shareholders. Marketing is an excellent sector to be investing in right now in my opinion, as flagged here several times before - as the valuations are still reasonable, yet clients are starting to crank up their spending, given that the economy is now appears to be recovering on a sustainable basis.
Tristel (LON:TSTL)
Tristel seems to be making progress, with an H1 update for the six months to 31 Dec 2013 (their next year end is 30 Jun 2014). What an excellent trading update too, it's crystal clear, giving the figures, I wish all companies would report like this (I have added bolding to most important points below);
Tristel has had a strong first half and expects to report encouraging performances from all business segments. Furthermore, following a better than expected December, revenue will be in excess of £6.4m (2012 £4.4m) and pre-tax profit in excess of £0.7m (2012 adjusted pre-tax loss of £0.6m) exceeding levels indicated in the AGM trading update issued in December.
The Company has benefited from strong operational cashflow in the first half of the year and net cash at 31 December was £1.4m (2012 net debt of £0.4m).
My only criticism of this trading update is that it is vague about full year expectations, saying only;
We continue to build upon these successes with confidence that they will continue into the second half and beyond.
So looking at the broker consensus forecasts, 1.8p is forecast for this year, and 2.7p for next year, which at 51.8p makes the shares look a tad pricey perhaps - that's 19.2 times next year's earnings. So bulls on this stock must believe they will beat broker consensus, and today's positive statement might mean they're on the right lines? It's not for me at this valuation though, and the shares have had a great run of about 150% in the last six months.
General market comments
This is very much a sentiment-driven stock market at the moment, which is increasing risk - because as we are increasingly seeing, it only needs a slight disappointment to knock prices back 20-30% (or even more). That's the big problem when you start chasing up stocks to more & more stretched valuations.
Also, I think the risk of a general meltdown in frothy stocks is increasing by the day. So I'll stick to my Value & GARP stocks, comfortable that they are good businesses at reasonable valuations - so if they drop, I'll use my spare cash to buy more. Whereas momentum traders are all assuming that they will be the first out of the exit - well they won't all be first out, will they?!
I think that, at some point, we could see a real meltdown in some of the more wackily valued stocks. I've no idea when though! (probably triggered by the next big correction in the USA). Sentiment can turn so rapidly, especially when all those stop losses start being hit, so it pays to be prepared.
Overall though, I think this bull market will continue, after the next correction. So my feeling is that there's no reason to be bearish overall, just cautious about valuation. After all, the two big bear markets in my investing career (2000-early2003, and 2007-early 2009) happened at the end of a long (7+ years) period of strong economic growth, and increasingly stretched share valuations.
Comparing that with now, whilst there are pockets of over-valuation at the moment, many of the larger companies making up FTSE 100 actually look quite good value. So it's mainly small to mid caps where some valuations have become stretched. In my opinion, stocks will correct individually, as investors take profits, and it dawns on them that they are over-valuing a lot of companies.
Consider also the macro picture - we're coming to the end of a long period (5 years) of depressed economic conditions, falling real household incomes, etc. So now recovery is taking hold, the stock market is just factoring that in - and valuations often look quite high on a PER basis at the start of an economic recovery. Once companies earnings rise, on an operationally geared basis sometimes very considerably, then the valuations become much more reasonable.
Overall then, I think caution is needed on valuation, and I'm banking profits by top-slicing things that have gone up a lot (as I always do). So that gives a pot of cash to keep on the side, and invest when prices correct, or when particular bargains pop up, as they do all the time, especially at the overlooked micro cap end of the market.
Please add your comments about your general market view in the comments below, this is not intended as a monologue, but a conversation starter!
Carclo (LON:CAR)
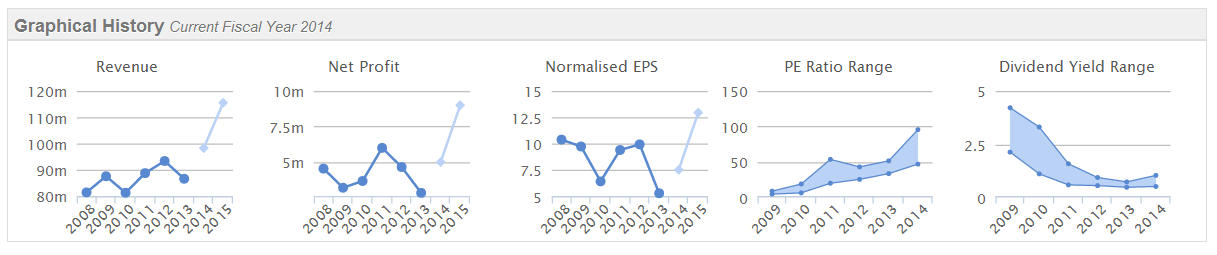
Checking the archive here, I haven't reported on this company before. It's cropped up as the largest significant sized company % faller of the day today, down 33% to 178p per share, so the market cap has plunged from £175m to about £117m. Not good. It's some sort of UK-based specialist plastics company, and performance in recent years looks to have been fairly lacklustre, so the valuation appears to rest on broker expectations of much higher profits in 2014 and 2015, as indicated in the Stockopedia graphical history below;
As I don't know anything about this company, it's not really possible for me to interpret this trading update very much at all. It says that H2 trading was stronger, but lower than expected. As regards outlook, the company says;
The group's balance sheet is strong and its funding remains secure. The board looks forward to sales and profits progression across the group in the coming financial year.
There are no figures in this trading update, so it's not possible for me to comment any further. Look at the forecast PER range above - between 50 and 100 earnings, and it doesn't appear to be trading as well as expected, so that's a perfect example of the dangers of highly rated stocks disappointing on growth that I mentioned earlier on in today's report.
Why take things on faith, pay up for a racy valuation, and then wake up one morning to find your shares 33% lower, because growth hasn't turned out to be quite as good as hoped? That seems like lousy risk:reward to me, and is exactly why I don't pay high prices for growth stocks. It has to be GARP, or I'm not interested.
That's it for today, see you tomorrow morning as usual!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in NWKI, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Hi Paul
Really learning a lot from your reports - much appreciated
With regard to the new format, could you ask the programming people at Stockopedia, if they could direct the clickable headers to a separate tab, so that we could keep your report open in one tab and look at the company in question in another
Chris
Hi Chris,
"could you ask the programming people at Stockopedia, if they could direct the clickable headers to a separate tab, so that we could keep your report open in one tab and look at the company in question in another"
There's an easy way around this.
Just RIGHT-click on the link, and select "open in new tab" from the pop up menu. That presents things how you want.
Cheers, Paul.
Chris/Paul,
An even easier way - just middle click on the link.
On Networkers International the litigation issue is an interesting one Paul. You're right that it first popped up years ago but the case was on hold while a related case rumbled on:
http://bryanschwartzlaw.blogspot.co.uk/2012/12/normal-0-false-false-false-en-us-x-none.html
Now that that case has concluded it's clear that Networkers are facing a class action and that sounds like an expensive proposition. So I can see why they've upped their provision to £1.85m (never mind the recent £0.25m legal costs) and are looking to settle with the litigants.
Whether they're out of the woods on this one is hard to say but at least there should be clarity on the issue in the first half of the year.
Hi Paul,
Just wanted to say thank-you for all the hard work you put in to your Stockopedia small cap value report.
We originally expected a brief single daily update from you and have found ourselves surprised (and delighted!) that you are providing further information throughout the morning - and beyond! Its a daily ‘must-read’ for us. We have been inspired and educated on a daily basis by your writing. My husband has even been moved to review various company financials, having previously ‘let’ me look at the numbers whilst he 'runs with his gut'!
In the past we were often around lurking in 'the pub' and (hopefully) learning but your current daily reports are in another league.
Very few of the companies that you have commented on have been right for our investment profile, but you have brought our attention to one or two companies that we like and would never have noticed - even with Stockopedia's extensive research capabilities. More importantly, you have alerted us to various pitfalls that may have otherwise caught us out.
So, thank you :-)
Alyson
Hi Alyson,
Thank you for your kind words, very nice, made my day! :-)
It's hard work, but I enjoy writing these reports, and it's a great discipline to have to put things down in writing that are scrutinised & challenged by many readers.
Regards, Paul.
Hi Paul,
As you mentioned the bigger picture and asked for contributions I thought I would respond, however I recognise what I am about to say regarding market timing is the antithesis of value investing.
As well as being a fundamental based investor I am very interested in stock market cycles and historical patterns. I have published a book about my 17.6 year stock market cycle which repeats in steps of 4.4 years (cyclical bull cycle) and 2.2 years (cyclical bear cycle). While this all sounds very precise, it is not. The years provide turning points but not specific dates. This diagram shows the secular (long term) 17.6 year bull and bear cycles. I have demonstrated that this precise cycle goes back to 1929 for the Dow Jones.
http://www.17yearstockmarketcycle.com/2013/05/secular-bear-market-vs-cyclical-bull.html
I am not saying hide under a rock until 2018, what I am saying is that the market will be continue to be volatile until 2018 (and ultimately go sideways) but from now until 2018 is a great time to accumulate stocks before the next secular bull market starts in 2018. You might say that the secular bull has already started, I don’t think so with interest rate artificially low and QE propping up US stocks, however I am not bearish as I do think the economy is picking up following the global financial crisis and interest rates will lag inflation.
http://www.telegraph.co.uk/finance/personalfinance/investing/10421834/Why-a-bull-market-could-come-charging-back-in-2018.html
I went 100% long in 2013 and I intend to stay that way until 2035. I agree with you that valuations have become a bit rich and some sort of correction is inevitable. I think it will be short lived and not a 2 year bear market as per 2000-2003 or 2007-2009. But I, like you, avoid poor balance sheets and crazy future expectations and therefore I think my portfolio will weather any temporary setbacks. I also avoid leverage having learnt that lesson the hard way (like most do).
This article shows that the cycle massively outperforms the Dow Jones since its inception in 1897.
http://intel.harriman-house.com/trading/halloween-indicator-timing-market-significantly-beats-time-market/
To conclude I am anticipating a short sharp correction or sideways range rather than a prolonged sell off.
Thanks for your posts here, I read them every day and enjoy them greatly.
Kerry
Hi Paul
I note the focus on operational gearing in your reports over the last few weeks. Not being an accountant by background is there a quick way to identify / know whether a business has high operational gearing.
Many thanks
Ric
Loudenr
a good clue to a company with operational gearing is a high gross profit margin. In some businesses the gross profit is simply arrived at by deducting the cost of goods sold from the revenue generated.
If other costs are relatively fixed then the gross profit generated by additional sales tends to go straight to the bottom line (net profit) without much in the way of additional cost.
Retailers are a good way to think about it. The gross profit equals the sales revenue less the cost of whatever they're selling. The shop running costs (payroll, rent, heat and light) are relatively fixed.
Two obvious ones are Games Workshop (70% GP margin) and Topps Tiles (60%). Those are exceptionally high GP margins.
Paul highlighted the operational gearing on Topps Tiles recently - if more people are doing their homes up now their % profit growth will outshoot their % revenue growth by some distance - which the market has started to recognise. Topps Tiles are probably not incurring extra costs attracting more people to their shops right now. Games W. has stumbled recently - whether this is a sign of a longer term trend is hard to say.
Those are obvious examples, but more generally I think you have to think about the business model and how additional revenue is generated and what costs need to be incurred to increase it.
A high gross profit margin also provides you with a higher margin of safety when things aren't going so well. Cars are selling well at the moment - but look at the skinny margins the distributors are reporting.
Hi Ric,
You asked;
I note the focus on operational gearing in your reports over the last few weeks. Not being an accountant by background is there a quick way to identify / know whether a business has high operational gearing?
Operational gearing is really just another way of saying that a company has high gross profit margins, and a relatively high fixed cost base. So it only takes a small change in sales to trigger a dramatic change in profit.
Non-food retailers are a good example - most of their costs are fixed or semi-fixed, e.g. rent/rates/utilities on all the shops, plus staffing has to be kept at a certain minimum level. So if sales suddenly shoot up, then the effect on profit is magnified greatly. This is good in a recovering economy, but potentially fatal in a Recession.
So really just look for companies that have high gross profits, and a largely fixed cost base that has the capacity to handle much higher sales. Software and internet companies are probably the most operationally geared, as their costs are almost completely fixed, and their sales are made on 100% gross profit margins. So additional sales drop straight through to profit.
Cheers, Paul.
Edit: Sorry, I just noticed that shipoffrogs had already answered your query, saying pretty much the same things as I've said above.
Loudenr
Paul has made a very useful point in suggesting investors look for companies with high operational gearing. One way to look at this is think of a business that has unused capacity to service more customers than it does at the moment and where the additional cost (what accountants call the marginal cost) to service an additional customer is very small. The larger the amount of excess capacity the more the potential the business has to significantly increase profits by exploiting this excess capacity.
A hotel is a good way to illustrate this. A hotel might be operating at say 60% capacity with only 6 in every 10 rooms let on average each night. By letting the extra rooms there is very little additional cost to the hotel, there will be laundry of the towels and bed clothes and maybe some electricity cost. But it is likely that perhaps 95% of what the customer pays will be profit (excluding the VAT). There is also the potential for additional revenue from the bar and food served in the restaurant that additional customers might generate in addition to the room charge.
Another example would be a plant hire operation. A piece of kit might only be rented for one week a month at the moment so there is scope for it to be rented out for another three weeks in the month with little or no additional cost to the business. The extra income is almost 100% profit.
When I sat down last year to look at industries that would have high operation gearing the first thing I thought of was a theme park as the only extra cost of having more visitors is some extra electricity in running the rides a bit longer. These places also have the capacity to handle a very large number of visitors before they get full. At that time there wasn't a suitable investment available in that industry but very conveniently along came Merlin Entertainments (LON:MERL) last Autumn.
I went on a National Express coach yesterday and on both the outward and return journeys the coach was under 50% full. If they could fill those empty seats the additional revenue would be very nearly 100% profit after a small additional cost in diesel for the heavier load. The added attraction of this business is they can very easily add on more capacity by hiring an additional coach, which they do at peak times. That means they can fill their "owned" capacity and meet any additional demand by hiring in. This is something they do very effectively at peak times but it needs to be carefully managed. Increasing capacity quickly is not something you can do in a hotel or on a railway very easily. Given the amount of spare capacity they have I also feel this is a wasted opportunity. Why is more not done to attract passengers from the rail network?
Hope these idea are of some help.
Quercus is interesting isn't it? On the face of it the company looks dead cheap and of reasonable quality (apart from structural decline in its sector) and a few weeks ago looked like an investment candidate. The only apparent red flag (beyond the declining share price) looked to be the steady decline in net cash held by the business - but there was still cash in the bank a few months ago.
However now the company is in discussion with its bankers! How did that happen given that the company was debt free at the last reporting and had a healthy coverage of its current liabilities by its current assets? Could this turn of events have been foreseen? I can't see the company being bought for more than peanuts but I'm still surprised by the speed of the collapse.
Thanks for the info rombold1 and Reynart - Now I know why they are so cheap!
Agreed with rombold1 on Quercus. They will be exposed to big Christmas returns from publishers right now and there can be no certainty that any sale will be at a premium to the current share price.
Hi Paul,
In case of there being a market meltdown,could you please let us know some of the value and GARP stocks you would be happy to buy/keep?
Quercus said yesterday"
"
As indicated in the Interim Results published on 26 September, 2013, the UK book trade has continued to be
challenging. The bulk of our profits are usually generated in the final quarter of the year. However,
sales in the final quarter were lower than expected, due in part to continuing issues within the book trade
which led retailers to adopt very conservative ordering policies and a lower than expected upturn in
digital sales over the Christmas period to the end of the year. As a result, the Directors expect the
Company to make a significant trading loss for the financial year.
The Company is in constructive discussions, which are on-going, with its bankers, Barclays regarding the
terms of its facility. A further announcement in this regard will be made in due course."
And today put themselves up for sale , at the behest of Barclays? , so they look uninvestable to me
I have been following Quercus Publishing for a long while now and there have been some dramatic falls recently without any news.. It seems extremely good value and on a PE for 2014 of 1.99... It has a 99 Value rating and no debt... I can't work out why this is so cheap - however i do realise that this particular share is not very liquid. Please could someone take a look and let me know what they think!
I saw that Carclo (CAR) produced a somewhat but not seriously negative trading update this morning. Sales of its coated film for electronic gadgets are below previous guidance. I later saw the SP down 35% and promptly bought some A case of buy first and think later? I would be interested in your views on Carclo while I go away and do my own research.
I like the new format, btw, and also admire the increased efforts you are putting in. I hope you get paid by the number of company reviews (rather than by the word - reading time limited).
Good morning Paul,
If you have time I would be interested in your opinion on the announcement from Trap Oil (LON:TRAP) today. I know you showed some interest in this company last year. Against a market cap of about £22m they say they have cash of £16m and I believe also some shares in Igas worth maybe £6m, so it seems everything else they own is in for free. I'm hoping to attend their presentation tomorrow evening (MRQ Online) when we might get a better view on prospects for the business going forward.
Andrew