Small Cap Value Report (22 May 2015) - PLUS, TUNG

Good morning. Well actually, it's not, it's been a horrible morning, as unfortunately I got caught on this one:
Plus500 (LON:PLUS)
Temporary suspension - the crazy thing is, I've never liked PLUS, and have always written negative things about it, saying how the figures looked too good to be true, or too good to be sustainable. However, in a rush of blood to the head, I decided to have a punt on it in my personal trading account a few days ago, and averaged down a few times, so that my average buy price is about 446p. This is now looking like a mistake. The shares have been temporarily suspended this morning at about 293p.
No details about the suspension are given, in terms of why, or the duration, with a statement today simply saying this;

It should be emphasised again, that my sensible, longer term stuff is what I write about in this blog, but to keep myself amused, I also do a bit of shorter term trading, of interesting & liquid shares that are moving a lot, e.g. Quindell was a share I was very active in last year, and made a terrific profit on it, being mainly short, but also sometimes long (for the rebounds).
Things have not worked out so well on PLUS. Chatting to my broker, he said that opinion on this stock is totally polarised (as it was with Quindell too). It might be worthwhile to recap on the bull and bear points;
Bear points
- Israeli company, listed on AIM
- Question marks over how the company has achieved such high profits & growth
- Sustainability of its business model under question
- Some negative reviews online from customers
- High profile short sellers (e.g. Gotham City) have attacked the company
- Recent freezing of some client accounts, due to inadequate paperwork, under regulatory pressure
- Repuational damage from freezing client accounts
Bull points
- Pays generous divis, including a large one paid a few days ago
- If the accounts are real, and sustainable, then the stock is now arguably cheap
- Former head of the FSA is a Non Exec
- The company claims to use clever online marketing to attract losing clients, who are highly profitable for them
- The company has had previous issues, which blew over fairly quickly
My opinion - it sounds like there could be more bad news to come out, but we don't really know at the moment. I've not seen anything concrete from the bears to support their allegations that the company is some sort of elaborate scam. The big divis paid suggest otherwise.
Maybe the Stock Exchange felt the shares had to be suspended, as the market was clearly becoming disorderly this morning? I've put a call in to the Nomad, so hopefully might get some more idea about what's happening, and if/when the shares are likely to resume trading.
Am obviously kicking myself for breaking my own rule of not investing in overseas companies listed on AIM. Or rather punting, not investing. So one to add to my "mistakes" book I think, although we don't know what the outcome will be yet. I fear things might get worse, before they get better though.
Breaking News!
Clarification statement - PLUS has just issued a statement, which reads quite positively in my opinion, in terms of how it might affect market sentiment. It gives more detail about the regulatory problems it has run into in the UK, and what it is doing to sort them out.
The shares have gone into auction, so will be coming back from suspension any minute.
Here's a summary;
- On 9 Jan 2015 the FCA required PLUS to appoint a "Skilled Person" to review its regulatory procedures & controls.
- On 15 May 2015 the FCA required PLUS to prohibit transactions on customer accounts without correct documentation & cease opening new accounts.
- PLUS has put 40 staff onto rectifying the documentation issue.
- Client accounts are being unfrozen when they provide documents needed.
- New client accounts should be possible again "in the next few days".
- As an interim measure, new accounts are being diverted to its Cypriot & Australian subsidiaries.
- Further update at AGM on Wed 27 May (next week!)
- Confirms $65m special divi was paid in full on 15 May 2015.
- Confirms has >$88m in own cash, over & above client funds.
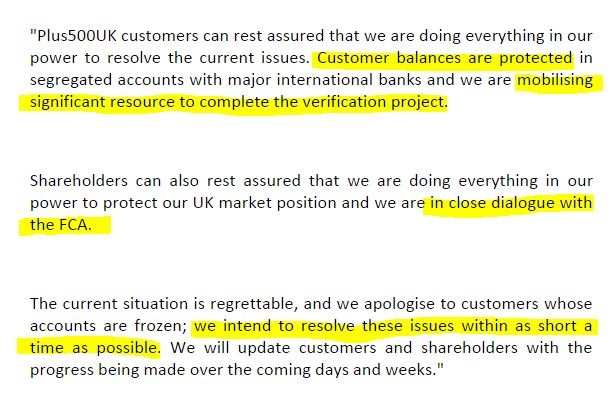
My (latest!) opinion - phew, this is nowhere near as bad as I feared.
It sounds as if the company is on the case, and getting things sorted out with respect to incorrect client documentation. My main worry is whether the regulatory problems get worse, and the FCA kicks it out of the UK market altogether. Although I can't see why they would do that, given that the fundamental issue is incorrect client documentation, which they are now sorting out.
Personally I am not convinced by the bear case (that the company is an elaborate fraud), so we could now see a recovery as shorts rush to cover their positions? I am minded to tough this one out, so I remain long in my trading account, but it's been a heart-stopping morning. Memo to self - stop doing these high risk trades, it's not good for your blood pressure!!
Tungsten (LON:TUNG)
Placing - I was slating Tungsten yesterday, but concluded that Edi Truell would probably pull something out of the hat, and he has done - a £17.5m (gross) Placing at 80p per share, which compared favourably with last night's close of c.70p, but compared very unfavourably with the much higher share price a few weeks ago.
The gross proceeds seem to be £17.5m, but yesterday's statement indicated a £15m net proceeds (after underwriting fees), so I will just clarify that point and update this article in a few minutes.
My opinion - raising fresh cash is clearly positive for the company, and 4 Board members have taken up stock in the Placing, although 3 are de minimis. Edi Truell has taken up 3,762,500 shares at 80p - so another big vote of confidence from him personally, so there's no denying his commitment to this company. Whether that actually has any predictive value, is very much questionable, based on previous similar big gestures.
My main concern is that the money raised doesn't look anywhere near enough, given the company's heavy cash burn. Although it sounds as if Tungsten Bank might be sold, which would raise more cash. Further talk from the company about creating a JV structure with a financier, is all very well, but that means giving away half of the upside potentially.
So whilst risk has reduced from raising fresh cash, it sounds like reward might end up reducing too. The sheen has very much gone from this wonder stock, and its management. I echo the remarks from Ben, in the comments section below, that experience with Tungsten is yet another example of how investing in story stocks is fraught with risk, and so many of them go wrong. Why on earth do we let ourselves get sucked into these story stocks, given the appalling end results in almost every case?! (this is very much a "memo to self" comment!).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
I bought in on friday at 202p and sold today at 299p. Its not investable as a stock as too many question marks and from here it really could go either way, I just saw it that the odds of it bouncing from 202 were substantially higher than it going further south. It has cash of around 76p so from 202 there was a maximum risk that I could see of circa 66%, and from here I think its a day traders dream stock as it will suffer from large swings in volatility so thats me done for now on this stock but I wish both sides well.
Re. Plus500 (LON:PLUS) Titan's Friday analysis http://www.titanip.co.uk/987/ is a detailed balanced view on the pros and cons of investing in this company at this crucial time. Briefly the scenarios are
- it is a fraud - value zero
- based on a disaster scenario it is worth around 250p
- based on reasonable but very conservative assumptions of impact of ALM, loss of customers, etc, it is worth around 600p
The SP as I write has just crept up to 300p. So the choice is losing your shirt or doubling your money. All that appears to be missing is the roulette wheel.
There is however a risk factor that Titan has not considered in his analysis. It is clear that PLUS have had a cavalier attitude to compliance. I would bet that they didn't even have a Compliance Department. Contrast that with with some financial services companies I have worked for which have up to 100 permanent staff enforcing compliance (OK these are much larger organisations than PLUS, but the point is that they take regulatory compliance very seriously). In this scenario, FCA will probably discover other breaches. All it would take over the next few months is public knowledge of a further different breach to send this stock back spiralling down.
I therefore differ from Titan's final verdict. The risk/ reward balance is firmly against investing or taking a punt.
All IMHO, DYOR, etc.
Ramridge, yes, I agree with your conclusion. Another factor for me is that Plus500 (LON:PLUS) has reportedly been under investigation of some kind since January 9, that's four months ago, without the Directors feeling the need to inform the market. Looking back, I see this was rumoured by "The Times" as long ago as last September:
http://leaprate.com/2014/09/plus500-drops-8-amid-fca-investigation-on-customer-signup/
Note the comment in this article that "The Times also quotes a Plus500 spokesman as responding that the company is indeed fully compliant with money laundering rules."
None of this inspires confidence, imo.
The Quindell (LON:QPP) share price was, I believe, close to 600p at the time of the Gotham City report so one could also say that the share price is still down 80% from its high point. I think that Quindell (LON:QPP) was a bomb waiting to explode, long before Gotham City ever came on the scene. Several other people were already analysing the hype being put out by the company, particularly in respect of revenue assumptions, claim success rates and accrual accounting and finding that it didn't stack up at all. Imo, there may still be even more skeletons to come out of the cupboard at QPP. Of course, these people who were doing their homework properly were rewarded by being insulted, abused and harassed by the unconditional and unthinking supporters of the then QPP management. That management has now mostly left the company, totally discredited and perhaps very fortunate not to be guests of Her Majesty in the Scrubs. So actually, Gotham mostly got it right, imo, as did people like Tom Winnifrith. As for the court case, no, it wasn't "lost", in fact the case was never heard since Gotham didn't put in an appearance, something that the then QPP management might well have been very thankful for; it would perhaps have turned out to be very embarrassing for them to be on the stand, answering under oath! As for shorting, the arguments for and against have been gone through often enough so I won't add to that.
The thing was so heavily oversold that there had to be a technical bounce at some point. Too bad it's not from the level I bought at.
Jane
As a shareholder until yesterday, it seems to me that most/all of the accusations made against PLUS were considerably wide of the mark. This was true even of the report that PLUS was suffering delays in on-boarding (horrible term) new customers, which sounded like they were winning more new business than they could cope with... ...which seemed to me like a relatively good problem to have, when the reality seems to be far worse. I wish these reports had been more accurate!
I cannot blame the shorters for the reputational damage albeit many of their allegations were wide of the mark. IMHO, this fiasco is all down to management incompetence and seemingly, again IMHO, a desire not to update the market in an appropriate and timely manner.
I had thought the appointment of the new director on 01-Jan-15 was a big tick in the compliance box for PLUS, but perhaps the opposite was true, with deficiencies being identified and addressed accordingly, as a result if his actions. Who knows? Certainly the FCA seems to have got involved at PLUS within 8 days of his appointment.
All rather frustrating. Obviously all the above is personal opinion.
Regards, Martin
Martin,
There's another factor which is equally important in providing that fertile ground for short-sellers and that's the frequent shareholder denial of information that comes to light about the company they're invested in, a kind of blind identification with that company, a kind of herd "circle the wagons, we're under attack" mentality, a refusal to even examine the possible validity of information or allegations. Why that occurs, I really don't know, surely there ought to be a deliberate detachment from identifying with the companies one is invested in and the people running them? Yes, there are common interests but also very opposed interests and we can't assume ever that directors have shareholders' interests as their number one priority. It's shareholder psychology, I suppose, something that I now see was present in my own early approach to investing but that I've learned to recognise and deal with. Excuse my musing! Bonne journée.
Jane;
As is often said "do not fall in love with your shares"....divorce can be expensive!
Martin,
Maybe some/all of the accusations made against PLUS were wide of the mark.
But isn't the fundamental problem with the business this: The business model relies on clever advertising to get naive customers to sign up to their platform. They/we know the customers are naive because if they weren't they wouldn't sign up to Plus in the first place. Competitors offer a similar but enhanced service to Plus, the only logical reason why a customer is with Plus is because they are not aware of other platforms available, or not able to compare the offerings between platforms and see that other platforms are better for them.
Plus are certainly not the first, nor will they be the last company to use clever advertising techniques to get customers to buy an inferior product at a higher price. The problem is they operate in a regulated industry, where part of that regulation is to ensure that potential customers have enough understanding or expertise of the product to make informed decisions. It seems to me if Plus were following the rules they would have to reject every potential customer on the basis that they wanted to sign up to Plus in the first place!
I should add that I have never used Plus' platform and am basing my opinion around research I did a while ago, but the general consensus I found was that Plus' offering was inferior to competitors in pretty much every area.
Add to this the general appearance of shadiness from the company structure/history, and managements lack of clarity and updates to the market. It's no surprise that the shorters have gone after it. Even after the huge price drop this week it still looks to me like a very risky proposition to invest/take a punt on. I have no position either way, and will be interested to see how it unfolds.
Matt
Well rather surprisingly Plus have gone up over 20% today. I thought the shorters would be attacking today but it seems some have reduced their holdings. The sp is now around 300p, really not sure which way its going to go now. I have sold 50% and we will see, at least its better than I feared on Friday.
garbetkib,
Both!!
Matmat
Which do you think of as the vulnerable people to be ripped off more - customers or shareholders.......
Hi Paul,
Thank you for your superb write up and opinion of Plus 500. The short sellers will have had an effect on the reputation of the company for sure. 11.7M trades today must include the short sellers determined to drive the price further down.
The F.C.A. will keep a tight watch on them & dealing in Bitcoins leaves the possibility of money laundering going on somewhere in the line in the world. Hopefully Plus 500 has already put stringent plans into operation when they started the business off.
How can you put a value on the true share price now? clearly right now it is more undervalued than earlier in the week & all I have to go on is the Vector Vest valuation. Stockopedia is still giving it a 95 stock rating although the momentum should may be showing negative currently!
Hi lightningtiger
Surely the recent RNSes highlight that PLUS's procedures, at least in the UK, have been unacceptably poor, i.e very far from stringent? Back-office operations are not rocket science and this is certainly true in terms of vetting new clients.
PLUS may well now be very cheap but I have to view them as uninvestable for me, as IMHO management view providing timely, complete and accurate information to the market as some sort of optional extra, not a basic requirement. Even today's RNS contains no information on how this fiasco is impacting trading and customer recruitment. And, just because this is allegedly a confidential process, why the 4.5 month delay in advising the market?
All in all very painful for me, especially as I have been abroad all week and unable to react quickly to unfolding events. I also wonder about the NOMAD's role in all this.
Cheers, Martin
Cheers, Martin
Lightningtiger,
You write, "the short sellers will have had an effect on the reputation of the company for sure. 11.7M trades today must include the short sellers determined to drive the price further down."
This knee-jerk response to blame "the shorters" follows the pattern of companies such as Gulf Keystone Petroleum (LON:GKP), Monitise (LON:MONI), Blinkx (LON:BLNX), Quindell (LON:QPP), etc, etc, etc, where there are always some shareholders who can't bring themselves to see and accept very, very obvious management and business failings.
It is those failings and the red flags that have been signaled for months now in the FT and elsewhere that have brought down the share price of Plus500 (LON:PLUS). The reportedly serious and apparently systematic breaches of the anti-money laundering regulations is surely a major cause for concern in a company you would invest in? I'm not a lawyer but would such breaches actually constitute criminal behaviour? Would that not be relevant in your assessment of where to invest?
I think you will find that shorters (of which, btw, I am not one) need fertile ground to make money out of their (entirely legal) activities. Imo, it is the management of Plus500 (LON:PLUS) you ought to be blaming for damaging the reputation of the company and for the collapse in the share price, no-one else.
Well the only ones of those I know are Quindell and Plus500. Re Quindell it was Gotham City that really had the effect of bringing the sp down, I believe, many of the things they said seem to be false, did they not lose the court case? I don't really like shorting, I don't think its right someone can sell short and then issue reports or say things to bring the sp down for their gain. I can see why its illegal in some countries. Quindell sp has recovered from 25p to 130p.
Do you think it's right someone can buy long and then issue reports or say things to bring the sp up for their gain?
No.
Tungsten;
It predecessor company, OB10's major customer's were Mega Corp (the household name multi nationals you and I use every day). OB10 did a good job at automating invoice payments for MegaCorp. However, the tougher part of the OB10/Tungsten model was that all Mega Corp's 1000's of suppliers had to sign up to to the OB10 platform, which they would only do because their major customer, MegaCorp told them they had to. If they were in effect forced by their major customers, Mega Corp, to sign up to the OB10/Tungsten platform, why would they feel kindly disposed to Tungsten to then buy credit/invoice discounting from Tungsten? Are there not many other invoice discounters out there in the market place? This has always been my primary problem with the Tungsten model
Who married Tungsten and OB10 together and why did they do it? The old Adage applies; always ask who is selling a company to you, and why are they selling it? OB10 was a perfectly solid business, but not a stock market mega star, even when combined with a bank
Veg,
"Financial services companies are the ultimate in trading on their client's "trust". Once you lose it it, then it is often curtains: Northern Rock is a prime case in point. Plus's technology may be great but if clients start to vote with their feet then there are never any "assets" left for shareholders, just a brand name (devalued) and some proprietary trading systems."
Absolutely - I'd say the same is similar of IT companies. As soon as the customers start moving, due to all the negativity, it's game over- whether the technology of the equipment is state of the art or not. There'll always be someone else with similar offerings,which might not be quite as good, but wont be suffering from bad press and questions to its financial stability/integrity
Reputational damage from such shorting attacks which exacerbate short term problems cannot be underestimated - especially these days given the hundreds of billions available to such shorters.
Good weekend all...
Hi Paul
A while back, Ed suggested that in terms of its StockRating, PLUS might be a false positive. I did not buy this argument at the time and if PLUS's compliance function had been vaguely competent, we would not be where we are now. However, we are where we are and, this indicates why a portfolio approach is necessary albeit I have still taken an unpleasant hit here.
On a separate tack, I would be interested to know whether the lack of information from PLUS since 09-Jan-15 means there has been a false market in PLUS's shares for some or all of this period? Given that the customer sign-up process is a key element of PLUS's business model, the fact that it has been massively deficient seems very material to me.
Thoughts welcome.
Cheers, Martin
Financial services companies are the ultimate in trading on their client's "trust". Once you lose it it, then it is often curtains: Northern Rock is a prime case in point.
Plus's technology may be great but if clients start to vote with their feet then there are never any "assets" left for shareholders, just a brand name (devalued) and some proprietary trading systems.
Therefore I would watch v v closely any client movements. If you were their client and had had your funds frozen due to FCA AML checks do you adopt a "wait and see" policy or migrate to a reputable competitor like IG Group (who may be the winner out of this). The contrarian in me says "its become interesting" the sensible one thinks "watch it for a while longer". The sensible one is winning at the moment.
Hi VegPatch,
I think those are fair comments, although it's important to remember who the clients of Plus500 (LON:PLUS) are. They're not the likes of us, they instead seek out gullible, small punters through ads on Google. Typical account size is very small, something like £1,000 I vaguely recall from memory.
Customer churn is high (i.e. they blow up their accounts quite quickly, as is the case with many spread bet companies too), so reputation is not really something that most punters who open accounts with PLUS would even be aware of, I think.
Therefore, I think there's a good chance that PLUS could recover surprisingly quickly from this crisis. The bear case is greatly exaggerating the negatives, in my view.
I'll give it a few weeks to see how this trade pans out, but freely admit this has not been one of my better punting ideas (so far, anyway). I only mentioned it here because people were getting confused between me saying here that I don't like the company (and that remains my view!), but saying on Twitter that I had gone long (which was just a trading punt). Why do some people have such difficulty with that concept?! (i.e. that it's perfectly possible to have a punt on a share which you don't actually like, if you think there is a short term trading opportunity).
Have a good weekend all, I'm going for a lie down in a cool, darkened room, to allow my blood pressure to subside, after a rather fraught day!!!
Regards, Paul.
Paul
Plus500 (LON:PLUS) It isn't just AML, the FCA are looking at customer recruitment, and for exactly the reasons you outline. Spread Bets and CFDs are sophisticated products and it is the responsibility of the service provider to vet customers and turn away those who do not understand what they are doing. They cheerfully admit that their customers are so bad they don't even need to hedge positions; if leverage is large enough just the random walk of intraday price movement will even wipe out trades heading in the right direction. Ipso facto their customers are not qualified to trade and the company has broken the rules letting them trade. If I were a Lawyer and I thought the funds were there for compensation I'd be seeking members for a class action on this basis.
AW
AW,
Good to see someone put forward the question of 'Do I want to own a company where the fundamental business model is to (probably) illegally rip off vulnerable people'. I guess to a lot of people the answer is 'how much will I make?'
I had a look at Plus a while ago on the back of what on the face of it were fantastic numbers, thankfully, I decided the company wasn't for me. Good luck to those still holding positions.
Paul, I owe you a drink. Just bought Plus 500 at 252.37p. Just caught your blog in the nick of time.
Thanks. you're a star. Have a good week end.
Charles
Re Tungsten (LON:TUNG) the one line from their recent trading update that makes me still bullish on this stock is: '38 suppliers had completed the registration process to become a customer of Tungsten Early Payment. Total invoices financed was £32 million.' £32 million sounds amazing from just 38 suppliers but it appears they use the option repeatedly and just build the cost into their prices.
If they can roll out the invoice financing to even a small percentage of their 171,000 suppliers (which itself is set to double in the next two years) then the hundreds of billions Truell rashly boasted about suddenly doesn't seem so incredible.
P.s. I agree management here have hardly covered themselves in glory but they've not been helped by the 'rent-a-mob' brigade who've tried to bring this company down, ultimately making it harder for them to raise the capital they need to expand and create new jobs and wealth for shareholders.
Sold 50% of PLUS several weeks ago for a healthy profit from my "punt" account. I can see no reason why the shares will not rebound when all the fuss dies down and I therefore remain long. Happy days!!
As someone who majored in Nineteenth Century Literature, may I recommend a holiday weekend break (well, of sorts) from PLUS and TUNG in reading Anthony Trollope's "The Way We Live Now" or, even better, in watching the excellent David Suchet in the BBC dramatisation of it. Trollope's portrayal of Melmotte could have come straight out of some of the characters who promote their dodgy wares today on AIM. Highly recommended but also very instructive!
George Hudson, the 'Railway King' was supposedly one model for Melmotte. He was the MP for Sunderland. 'Nuff said!
Paul,
If they can get £50m for Tungsten Bank doesn't that mean the company is valued at £25m? Might be worth a £1 spread bet for fun - always the best anwer to prevent the loss of real money. If you do have a dog the best thing is to sell half or at least something - it pushes you away from holding on in hope and once you have sold half it is so much easier to sell the other half.
FM
as a nice distraction, did you notice UCG.L (tinpot) have announced a 1p divi, when the share price was 10p!
Regards
Hi Paul,
I agree re PLUS.L and its divis, cash flow can only lie for so long, and unless they have been stealing money from clients then it looks to me like the cash flow is plausible, and that it is just Plus's turn for the mangle....
I would say that though as I am long PLUS.L in my "value" driven portfolio.
I don't intend selling any at the moment, as I can't see a genuine reason why, despite all the (very load) noise, and I am willing to wait up to 2 years to see my bet work out, or go wrong.
As ever, time will tell.
Best of luck with your short term trade.
Regards
Why we need to second guess the stock ranks and stock screens:
* stock ranks and screens can only work with the published results
* it's the auditors job to verify the truth of the published results. Auditors sign up to the fact that the accounts present "a true and fair view" of the business
* but the auditors are employed by an audit committee - effectively the board of directors. If they want to keep their (highly paid) work, it's strongly in their interest to go along with the wishes of the directors. Tthis might change if auditors suffered heavy penalties when they sign off on a set of accounts that is later found to be incorrect. How often does that happen in practice? A legal obligation to recompense shareholders for their losses might be interesting here
* similarly for NOMADs
So the excellent Stockopedia stock ranks and screens can get things very badly wrong when the reported results turn out to be partly or completely works of fiction.
As always, many thanks to you Paul for the thoroughness and good sense of your analysis and especially for your, highly refreshing, willingness to own up to errors and misjudgements. We are much more likely to make a success of this game when we are willing to protect our investments instead of our egos
its in and out of auction at the moment, currently in.....
Plus have just released some RNS and suspension is lifted. But I cant trade with my broker?
Re PLUS, I'm still waiting for the most recent dividend in two accounts (ISA and SIPP). I sold all my PLUS shares just before 10am this morning and now kicking myself slightly for panic.
Got the dividend this afternoon after phoning customer support on the ISA. Seem to remember having to chase the previous dividend also. They say it's due to the dividend being paid by cheque in another currency.
Fair play for admitting your mistake as many wouldn't.
What interests me now is that a lot of people including yourself have a punting account. Mixing a small amount of gambling spreadbets or punts as you call them . It certainly doesn't fit your profile as a value investor. We are certainly in the thrills of a bull market when some of the better investors get caught up in the euphoria are taking chances others wouldn't .
good luck all the same
Hi pyemackay,
Actually, in my experience lots of successful investors have two very distinct approaches - a value-orientated long term portfolio, and then a punting fund (usually through a SB a/c) for doing shorter term trades.
As long as the two approaches are totally separate, there's no problem at all with doing both investing and trading, in my view. The problems arise when people blur the two.
Regards, Paul.
referring to TUNG
Buying a company with no earnings and no assets on an elevated mkt cap is a coin-flip . Dont be surprised by the results . I learned a hard lesson on an explorer and won't do it again.
Paul,
I also wanted to add my thanks for your sage writings. I am sorry you have got caught with this one, however I like to think I pay money for a surge of adrenaline and it has certainly given that over the last few days. My weakness in investment is just this as I find the surge totally addictive. That said you are always very clear and I have structured a portfolio in the background which has the characteristics I want from my investments. This is totally down to you providing a back drop for us simple men to think about our own investment. If you are not making mistakes you are not learning. I just make the mistake of falling knives tooooo often.
you might just get your bounce now Paul....
A shame the latest statement (13.15) doesn't indicate how revenue or profits might be affected. But looks like trading's resumed.
The irony to me is that PLUS were accused of sloppy fulfillment of regulatory requirements - one key reason cited by shorters. Since the joining of the ex FSA guy being appointed, they are now tightening up. So this should add to their company strength (albeit short term revenue loss while implemented) - but it seems to be leading to it's weakness!
The USP is their understanding of how to optimise the internet to get new customers. Clem Chambers, ADVFN, is pretty positive about PLUSs tech savvy. It's PLUS competitive advantage so they're not going to disclose how they do it - like CocaCola's secret x ingredient. However, because most of us don't understand how their doing it so we assume it's not viable.
As for liquidity, their highly cash generative, and relatively low capital cost "cash reserves $88m".
Spreadbetters or gaming companies may not be the most ethical, depending on your morals, but it doesn't necessarily make them a bad investment - but they do always seem prone to the volatility of the very industry they're in.
Holding PLUS (which I do, and have since the IPO) you have to expect they will have a short attack - so it can be an emotional rollercoaster. But, I'm still awaiting information that their worth 63% less than they were at the beginning of the week.
Whenever a stock takes a big tumble I steer well clear. The first position I ever put our client accounts into at Goldman Sachs was CBT Group - a US education tech company. It had fallen 50% on basically no news. We put a small position on across the board. It feel another 50% the next day. We sold. Felt pretty daft.
Where there's smoke there's usually fire. Better to wait for the firefighters to mop up a bit before entering the building.
Paul, unfortunately existence of a generous cash dividend is absolutely no guarantee of a company being legit. I bought some Naibu shares last year and got a very generous half-year divi. The rest is history as they say... (luckily I escaped with a small loss that equalled my divi receipt!!).
Good luck with your PLUS holding.
cyberbub,
Re the Naibu Global International Co (LON:NBU) divis - as reported here, I was very sceptical about those at the time. The divis actually were not very generous when you work out what was paid to external shareholders, and it was pretty obvious they only brought in a divi to boost the share price so that insiders could keep selling at a higher price!
It's different with Plus500 (LON:PLUS) - the company has a track record of paying out big divis, so there is little doubt that its cashflow is real, in my view. Unless, as some suggest, it's an outright fraud that has been plundering client accounts to fund divis. But where is the evidence for that? A handful of dissatisfied customers posting critical reviews doesn't amount to much, in my view.
You're right, the client funds hypothesis is too far fetched, especially now that we know they've been under direct FCA scrutiny for several months. Hopefully the regulator did check that client money management was okay.
I'll go back to my mainline hypothesis that it's a stock promotion, with principals planning to exit when they hit the capacity constraints of the creepy business model.
Hi cig -
" especially now that we know they've been under direct FCA scrutiny for several months. Hopefully the regulator did check that client money management was okay. "
Would be interested to know the source of your information. I cannot find an official document that says they have been under FCA scrutiny for several months.
It's in today's clarification statement RNS (linked in Paul's post above). The FCA started investigating them in January, but they were not required to disclose it.
Thanks, cig. It's Friday and I am suffering from information overload.
I think the truth is probably what we already knew - that PLUS is a particularly sharp operator which takes advantage of mug punters who consistently lose money.
Shouldn't it follow that they were/are likely, in some way or other, to treat shareholders like mug punters who consistently lose money (which would not be that inaccurate a description of some AIM investors)?
Re the big dividend as a bull point, it's only so if it wasn't paid out of client funds that they hoped to make up for later. (Pure speculation here.)
I bought back into TUNG at 75p yesterday. I expected to see it at sub 40 this morning. Quietly relieved atm.
Sorry to hear about your paper loss here Paul, I've been on the sidelines for all the reasons you articulated so many times and agree that there is no single smoking gun ...except one.
SB and CFD providers operate only with the regulators consent , if , and it still is an if, Plus 500 have breached AML rules seriously enough to make it impossible for the regulator to allow them to trade then it is game over.
Their model also stank to high heaven as it seemed it was predicated on dredging up a consistent stream of mug punters and fleecing them ...that too seemed unlikely to make the regulators anything other on edge.
Good luck anyhow...just enjoy the irony of losing money going long on a stock you'd long suspected to be a wrong'un!
Paul thanks for the posts. Not only do I think a check list is mandatory in any stock picking but the way you have bullet pointed both the bull and bear points makes this tangled web of news flow if not clear certainly into perspective.
Best wishes to all concerned here.
Not hedging is a very serious matter. The leverage implied is vast and takes the risk profile of such a company to an unfathomable level. The earnings achieved in such a manner aren't real earnings - it's just customer money which the customer has blown up and which the company has kept. That's fine for a while, but if the customers have a winning streak then the company melts down.
It's worth browsing places like trade2win, an important forum for the trading community. You'll find little there to back up the idea that plus500 was a serious player in the market or threatening to become one.
I have a beneficial interest in IGG.
Regarding Tungsten (LON:TUNG), I am currently sitting on a pretty painful paper loss on this one, having foolishly averaged down. I also "over-rode my own rule" by averaging down and trying to catch a falling knife.
However, I am not tempted to sell out as I do believe that this company will make money and be profitable - it will just take longer (How much longer? Who knows?) than I had anticipated or hoped.
The big thing as far as I am concerned though is that in spite of the paper loss I am still in the game. Had I used stop-losses I would have been stopped out by now and the paper loss would have been realised. Had I used gearing I could have been not so much stopped out but wiped out due to the speed of the fall in share price.
I am very glad I used neither.
Steve
Hi Steve,
Sorry to hear of your challenges.
So now you are left with no paper loss (ego intact?) but your money in a questionable share?
For me I'd sleep easier knowing that I'd made a mistake, got out via a stop loss and selected another more favourable stock.
If boothbym (see post 7) had used a trailing stop loss on Plus he/she would probably sold out at £6.
For me ego is fatal in investing but then again I'm not a value investor.
Best of luck with your investments
Phil
Hi Phil,
All fair comments. In truth, TUNG is still a company that I want to be invested in. My mistake was buying at the wrong time and then averaging down when the SP was falling like a stone, rather than wait for the first signs of recovery (like now!) before topping up at a lower price.
In truth, if I wanted to quickly release some funds, either for investment purposes or non-investment purposes, I would sell some or all of my TUNG shares and take the hit, but whilst that isn't the case I will hold on and see what happens, cautiously optimistic.
Steve
Been a bad week for me.
Should add that I have revieved all my dividens from Plus.I bought Plus500 a few times at £3.50 watched it get to £7+ and failed to sell (Well not totaly true sold a few). Eventualy sold the majority at £3.90 for a tiny profit.
Not to self sell half when at 100% profit.
As always Paul, just thank you for copying us in on what you are doing and your thoughts on actions in the market. It is thanks to you drilling into us that we should treat foreign AIM shares with extreme suspicion that I did not buy Plus500. I know you had a punt, but to me that is different. I don't have time to watch the market all the time thus really appreciate your steady-as-she-goes attitude on this website, but to also get an insight into what is happening in the short term trading world is also of use as part of the picture.
"I've not seen anything concrete from the bears to support their allegations that the company is some sort of elaborate scam. The big divis paid suggest otherwise."
There was a mixer load of concrete from a bear / Hedge Fund who is short here:
Your Capital at Risk Part 1: Short Plus500
I have no position in this one myself.
Hi jjjs,
I've read that report, and there's nothing concrete in it, that I can see, which justifies the shares collapsing in price.
You can refute most items quite easily actually. e.g. audit dates - totally irrelevant. Subsidiary accounts are often formally signed off after group accounts have been filed, which is the main priority. It's just a clerical matter, to have them signed & filed, after the figures have been agreed.
Not hedging client positions - so what? There's no requirement to hedge client positions at all, and some other SB cos don't hedge for clients who are consistent losers.
I'm not saying PLUS is a good company, because it isn't, it seems to be a rather spivvy operation. It's certainly not the type of share I'd ever want to invest in (as opposed to doing short term trades in).
But it's easy to read shorting dossiers and think everything is terrible, due to the cumulative impact of apparently negative allegations. That's what they are designed to achieve - to scare people into selling, so the shorters can bank their profits.
However, in this case I can't see very much of real substance in the dossier from Cable Car Capital which suggests that the stock is an elaborate scam, which is what bears are implying. I agree that PLUS is probably a sharp operator, but anything worse than that?
I think the truth is probably what we already knew - that PLUS is a particularly sharp operator which takes advantage of mug punters who consistently lose money. A bit like bookies, and SB cos, arguably.
Regards, Paul.
P.S. A friend of mine had a run of good luck on Betfair, and discovered that Betfair had plundered his account, and basically stolen about 20% of his winnings! When he kicked up a fuss, they said he was taking too much money out of the pool, and that they were allowed to impose this punitive surcharge in their Terms & Conditions.
So if you think that only PLUS is ripping off its customers, think again!
Thankfully I have Mark Bentley to thank for inviting me to join the panel at the ShareSoc Masterclass. As we had to say something intelligent about the stock on the panel I actually did some qualitative research for once and ended up selling my position.
I took a bit of flak for over-riding my own rules... but sometimes gut instinct works out.
Hi Ed,
Yes I've seen the bear attacks, but there's not actually much substance to them in reality.
Certainly no "smoking gun".
It's really ironic that I've ended up being long of this share, over-riding my own rules on not touching overseas AIM stocks, and especially given that I've been a critic of PLUS for ages now! AND that you sold out, over-riding your own rules too!
If you think about it, it should've been the other way around - you should have incurred the loss, from selecting PLUS mechanically, and I should have been crowing about how I'd avoided it due to stockpickers instincts & red flags (which I did, until a couple of days ago!)
Funny how things work out sometimes!!
Regards, Paul.
In a ponzi scheme based on poor audit, you would not expect to see a smoking gun until after it has failed, would you? I am definitely not saying Plus500 is a ponzi, but look at the few things we have known about it: it makes recruitment ultra-easy, it takes cash from those recruits, it pays out dividends, customers are obstructed from withdrawing money, it has no tangible product for the customer except a trading experience, produces very impressive accounts, has a very high revenue per customer which its competitors can't replicate, it has an unusual structure, is listed on AIM and is in an obscure location. Everyone is in a flap now, but the fundamentals have not changed since inception. I am definitely not saying Plus500 is a ponzi, but it has the signs you might expect of one.
Paul, It's definitely been one of those weeks... and I think we all deserve a few days (hopefully in the sun) away from the crazy AIM markets. It's a horrendous feeling checking your screen to see one of your companies down 30% and it really doesn't matter if you are a multimillionaire or a (very) small investor, such as myself. Plus500 (LON:PLUS) was one in which I bought just after IPO and sold at £2.60 for a 100% gain. I then spent 2014 annoyed that I didn't hold on for a 400-500% gain... but something didn't feel right - I signed up to their platform but was very unimpressed and there are much better services on offer from the likes of IG etc. It's a pity that so many small investors loose out in the wild west that is AIM - wouldn't it be in everyone's interests to have tighter regulations in this market to clean it up? Tungsten (LON:TUNG) has been a bad experience for me and I have found to my cost that i'm not very good at picking (gambling on) story stocks but that my strengths are in spotting undervalued / unloved companies which are profitable and have strong management teams to transform and grow the business. From now on i'm going to stick to my strengths and avoid being taken in by bulls**t. Have a good bank holiday weekend.
Cheers.
Ben