Small Cap Value Report (22 May 2017) - KWS, SOG, IDP

Good morning!
I didn't get involved in the RBG story last week but the comments have continued on Paul's thread from last Friday, visible here.
Onto today's updates:
Keywords Studios (LON:KWS)
- Share price: 826.25p (+3.3%)
- No. shares: 55.6m
- Market cap: £459m
This international service provider to the video gaming industry continues to spread its wings, developing its presence in China and Indonesia via acquisition.
In theory, I like the sound of this company. It gets
to take part in the growth of gaming worldwide without
being overly reliant on the success or failure of individual titles as game publishers might be. Instead, it relies on its relationship with those publishers.
The services it provides can be broadly broken down into localisation (text/audio translation), testing and quality control.
It has undertaken a very large of number of small acquisitions, and today marks the continuation of that trend with a further $6 million being spent on this company (in a mix of cash, deferred cash and deferred shares).
Management of the target will stick around, which is good, and it sounds like it might be decent value against $0.9 million in PBT at the target last year.
CEO comment:
"The acquisition of Red Hot further strengthens our fast growing, higher margin art services business, enhancing our unique client proposition which combines operations close to our clients, in the US and Canada, with those in lower cost locations across Asia. Following the acquisition, we believe the Keywords Art Service Line is the leading player in the outsourced market in terms of capacity and breadth of service."
I wonder if art services is a good place to be from an investor point of view - it sounds perhaps quite labour-intensive.
Red Hot has 220 artists in its employ, so this deal values the company at $27k per artist.
Granted that the salaries in its 2nd/3rd-tier Chinese cities will be lower than typical Western salaries, that still seems to be a rather low valuation per skilled employee.
So I would have a little bit of concern in terms of whether this is an attractive segment to be from the point of view of 3rd-party investors. However, it could be the case that art services are highly complementary to the rest of the services provided by KWS, so it's important to beef them up as part of the overall offering.
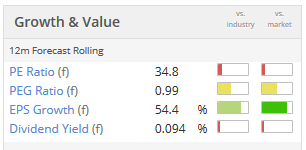
It's a highly-rated stock and a High Flyer according to Stockopedia's StockRank Style, and it appears to have done enough to deserve that, in terms of profitability growth. Worth looking into.
StatPro (LON:SOG)
- Share price: 124p (unch.)
- No. shares: 64.7m
- Market cap: £80m
AGM Statement and Trading Update
It's a confident statement today from the chairman of this cloud-based portfolio analytics software company, serving the asset management industry.
Stepping aside after 17 years at the helm, he includes a summary of the group's evolution and progression over that time period.
Trading is in line:
"Trading in the first quarter of the current financial year is in line with expectations.
"New sales of StatPro Revolution and StatPro Seven have progressed well and the pipeline for the remainder of the year remains solid.
Worth noting that having grown by acquisition over the years, Statpro's 2016 results suffered the stain of very large (nearly £10 million) goodwill impairments, and other "one-off" items, resulting in a net loss of £10 million.
But the impairments were non-cash, of course, and underlying trading continued to grow in a reasonable way, so the dividend was unchanged.
The stock is highly-rated which I guess is a consequence of having sticky customers in the asset management space, its own strong forecast sales growth, and software valuations generally at the moment.
Given it's relatively small size, I would assume that a company such as this would eventually get taken out at a decent premium by one of the giant financial software providers and suppliers to the buy-side industry. Though Statpro has been independent for so long, perhaps there are particular reasons it has not been bought out yet?
Given the current 2.3% yield and 21x forward PE ratio, it's not exactly in the "value" territory (of course, neither was KWS), but maybe it's one to keep on the watchlist.
Innovaderma (LON:IDP)
- Share price: 248.5p (+9%)
- No. shares: 12.5m
- Market cap: £31m
Launch of haircare range and entry into skincare
I mention this in passing as IDP shares are up more than 50% since I first mentioned them in these reports and momentum apparently remains strong as two separate initiatives are announced today.
Signs remain positive with five new haircare products being launched in Superdrug's top 400 stores from August, along with a brand extension to the successful Skinny Tan brand.
It's forecast to make a small profit this fiscal year on c. £7 million of revenue, up from £4 million the prior year, and has excellent gross margins, the only thing I'm not sure about is the size of the addressable market - I've seen an estimate that self-tanning is worth c. £60 million in the UK.
That's not really exciting enough for me to want to get involved. On the other hand, if it were to make progress in the US and Australia, then it could be worth considerably more than the current market cap!
Taking a break now, hoping to add another story later.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Thanks for all comments... and apologies for not adding anything further to this article on Monday.
Paul, re: Cenkos Securities (LON:CNKS), I have held it before and I like it. Great divis and well-incentivised teams. Compensation is more variable than their rivals. I'll need to have a look at the most recent results.
Graham
Keywords Studios (LON:KWS) has currently dropped 4% on the result of a placing. Does anyone know why this has happened considering that £G4M also announced a placing but went up as a result? Is it due to the fact that the Gear4music placing was oversubscribed?
Regards,
tony777x
Hi Tony
I think it's because the KWS placing is a sale by the founders of a substantial % of their holding. I'm v unsure what to do!
Andy
Hi Andy,
I don't think the price will drop below 820p since that was the price of the placing. If institutional investors are willing to pay that then surely that must act as a minimum value for the company?
Tony777x
Thanks Graham.
It's always interesting (but a bit strange!!!) for me to read your reports, as you sometimes cover companies I've not looked at before - e.g. financials & pharmas.
Have you looked at Cenkos Securities (LON:CNKS) ? I've held this one for a while, and get paid monster divis. It's paid out more than its entire market cap in divis in about the last 10 yrs. Earnings obviously feast & famine, but looks dirt cheap to me. Would be interested in your view.
Cheers, Paul.
Paul
When do you expect Cenkos Securities (LON:CNKS) to report its final results for 2016? Last year it was towards the end of March, and the interims were in September.
Cenkos Securities (LON:CNKS) FY results were issued in March: http://www.investegate.co.uk/cenkos-securities--cnks-/rns/final-results/201703310700120983B/
Best wishes,
Imran.
Thanks, Imran - for some reason they are not in the news tab on the StockReport.
Best wishes
FREng
I've been monitoring StatPro (LON:SOG) for a while. To date, I haven't invested as a result of minimal organic revenue growth and cash flow being almost entirely consumed by capex and R&D. The revenue development is difficult to follow as they appear to be growing within high value customers but losing an offsetting amount of revenue from low value customers. If this stops and if the R&D costs subside, it could be very cash generative. To Graham's point on customer stickiness, slide 27 of the full year results presentation says that 76% of their annualised recurring revenue (pre UBS Delta acquisition) comes from customers who have been with them for 6 years or more (32% from customers of 11 years or more).
The acquisition of UBS Delta looks extremely interesting though not without risk. They will have to spend 3 years porting UBS Delta to the cloud and incorporating it into their Revolution offering. They won't own the customer contract until then. I listened to a recording of the acquisition conference call (http://www.statpro.com/download/statpro-ubs-delta/StatPro%20-%20UBS%20Delta%20conference%20call%20-%207%20April%202017.mp3). UBS Delta brings them 100 new customer relationships and a best-in-class fixed income product in need of modernisation. Given the CEO's comments on the call about how difficult it is to acquire a new customer as opposed to expanding with an existing one, this could prove to be a fabulous acquisition if they get it right and can keep the UBS Delta customer base in tact.
Edison and Progressive both have post-acquisition broker notes that are available to the public. The valuation jumped on ugraded acquisition related numbers, heavy director buying and some see the acquisition of BISAM by FACTSet at 7x revenue as supportive (who wouldn't at that price?). Liontrust and Herald own 33% together. CEO has 11.5%.
Thanks for that very detailed and useful comment on StatPro (LON:SOG). Chimes with my understanding of how the industry works and suggests there could be more interesting news to come from this crowd.
Graham
Graham, can I ask you about Avacta. It is a stock I have followed for a while and have a holding in. There seem to have been quite a few positive announcements of late although the share price had receded to around 60p and has rebounded to around 90p. I know its a blue sky story but does appear to have some legs. The problem I am having is they have decided to allow people licences to use their library of affimers. I am struggling to put a value on it and wondered if any of the readers have experience of these types of arrangements. Similar platforms appear to have valuations from a few hundred million to over a billion pounds. But the company don't provide any numbers which isn't particularly helpful. Any and all thoughts welcomed.
Thanks for covering Innovaderma (LON:IDP) Graham. I eventually bought a small amount after researching it following your original note - albeit several weeks after it had gone up a lot! It's becoming difficult to guesstimate what sort of MCap is possible because it's made quite a few new product and trading update announcements in the last few months and this feels like a company that's still at an early stage albeit making a small profit already. What really drove the share price recently was an announcement that ASOS (LON:ASC) would start stocking its popular Skinny Tan product globally from June. I don't know to what extent beauty products sell well at ASOS (LON:ASC) although I note it only stocks one other self tan product currently (on the UK site anyway).
I think Innovaderma (LON:IDP) has good growth prospects. It also announced new European distribution networks recently:
"InnovaDerma secured the distribution of Skinny Tan with the following e-tailers in March:
· Feelunique, one of Europe's largest online beauty retailers
· Lookfantastic.com, Europe's No.1 retailer for beauty which attracts half a million unique visitors a month
The Company has opened up new markets especially in continental Europe for its fast-growing Skinny Tan brand through securing e-tailers which offer European and Worldwide delivery. The Company expects to secure further e-tailers in the last quarter of FY 2017."
Both Feelunique and Lookfantastic are well-established etailers. I expect the broker estimates you've noted to be underestimates but that's more of a hunch than any clever estimates I've made.
The amazon reviews of its products are bit mixed. They seem to be a bit love/hate with lots of Five and One star reviews. Having trawled the internet there does seem to be a bit of a following for the SkinnyTan products which reassured me their products are well liked by the target market.
One risk for me is that I worry the company is trying to launch too many products too quickly and risks taking its eye off the ball. It seems to be executing well for now though.
Glad I helped you find IDP, Paraic, I am tempted to buy some too, though I also worry about their focus. They are a bit small to be spreading into unrelated sectors IMV. If they stuck with haircare and skincare I'd be happy enough!
Best of luck
Graam
Graham Skinnytan started in Australia, they recently moved the factory to the UK as that's their main market. Don't hold - but bloody wish I did!
Yep, I saw they moved from Australia. Good point rtj!
Graham
Keywords Studios (LON:KWS) also announced another acquisition last Friday of a company called GameSim. This is their first acquisition in software engineering services and opens another strand of business for them.
I certainly can't fault their pace and energy in executing their acquisition strategy and so far they appear to have an excellent record of integrating them.
I'm a holder.
http://www.investegate.co.uk/keywords-studios-plc/rns/acquisition-of-gamesim-inc-/201705170700083530F/
Three acquisitions in two weeks seems remarkable. Can the management of Keywords Studios (LON:KWS) have enough time to win and manage the business alongside integrating such a large increase in staff?