Small Cap Value Report (Fri 19 May 2017 - Part 1) - RBG, G4M

I would say good morning, but it's been a lousy morning so far - with a profit warning from one of my largest long positions - Revolution Bars (LON:RBG) . So I'll focus on that mainly.
Graham's doing a separate report today - which is taking shape here.
However, I'I need to get my head around what's gone wrong at RBG, and report to you - plus hear your views too of course, in the comments section below.
Revolution Bars (LON:RBG)
Share price: 139.75p (down 31.5% today)
No. shares: 50.0m
Market cap: £69.9m
(at the time of writing, I hold a long position in this share)
Trading update (profit warning) - covering the year (to date) ending 1 Jul 2017.
This is an expanding operator of town/city centre bars with a premium drinks offering (cocktail-driven).
The share price has been clobbered this morning by a profit warning. Let's dig into what's gone wrong.
Revenues - this sounds alright;
The underlying sales performance of the business has remained positive in the second half with like for like sales continuing to grow by 1.7% for the year to date ...
The company last reported LFL sales at 1.7% for the 8 weeks to 25 Feb 2017
Prior to that, it reported LFL sales for H1 at 2.0%
Therefore, this implies that LFL sales for the most recent 11 weeks to 13 May 2017 must have been lower than 1.7%, in order to drag the average at the H1 stage down from 2.0% to 1.7%.
In order to estimate the most recent LFL sales performance, I've knocked up a simple spreadsheet (NB. this ignores seasonality):
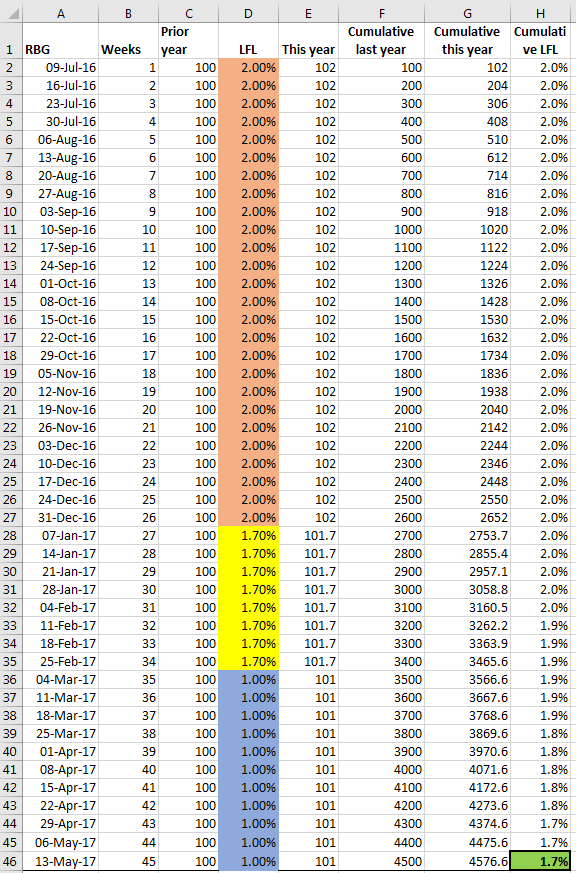
This is all about LFL sales. So in column D I've plugged in the reported LFL sales - the beige section is the 2.0% LFL sales increase for H1, as reported on 28 Feb 2017.
The yellow section in column D is the 1.7% LFL sales also reported on 28 Feb 2017.
The blue section is my estimate, by trial and error, to arrive at a cumulative total of 1.7% LFL for the year to date, as reported today. This is in cell H46 above.
So the key takeaway from this spreadsheet, is that I reckon the most recent 11 weeks trading has softened slightly, but is still positive, at +1.0 LFL. Hardly a disaster.
Gross margins - nothing wrong here. Today's update says;
...gross margins remaining as expected.
What's gone wrong then? It seems to mainly be cost over-runs;
The Company is experiencing the well-publicised sector cost headwinds from the impact of the living wage, the double increase this year in minimum wage, the new apprenticeship levy, as well as the above inflation increase in general business rates. These increased costs will be more than anticipated in the current year.
I've got a problem with this. All those items were already known about. So why is the company now being surprised by these cost increases? Also, why has the company not mitigated cost increases in the way that others have (e.g. Patisserie Holdings (LON:CAKE) which reported this week, and absorbed cost increases through, e.g. more efficient staff rostering).
I suspect the answer might be lack of financial control. After all, Revolution did lose 2 CFOs in rapid succession (for reasons that were not suspicious - as previously reported here). I heard it from the horses' mouth, as the outgoing CFO explained that with young children he wanted a job that involved less travel.
Clearly this is disappointing, but it's actually quite easy to fix. The new CFO needs to sit down with the Area Managers, and thrash out more efficient staff rostering, to reduce costs. Although great care has to be taken to ensure customer service doesn't suffer. Long queues at an under-staffed bar is the easiest way to alienate customers, who may not then come back.
At a previous meeting, management also told me that they deliberately over-staff new sites at first. This is to provide a good initial impression with customers, and to allow staff time to get trained up & experienced. So there are natural savings in the pipeline from this factor.
New sites - this seems slightly contradictory to me;
The Company has opened five new Revolucion De Cubas in the last twelve months (and one new Revolution Bar) and whilst the underlying sales performance of these bars remain on track with an average weekly turnover of £43k (net), these bars are taking longer to mature to full profitability than originally anticipated.
Additionally, two key sites were closed for just under two weeks for major refurbishment (Blackpool in March and Cardiff in May). All these sites will make a full profit contribution in our next financial year.
I'm confused. If the new sites are meeting sales targets, why are they not reaching full profitability? Again, that suggests cost over-runs - which can be fixed.
Overall impact - EBITDA flat;
Consequently, due to the timing of profit maturation at the new Revolucion De Cubas and the industry-wide cost headwinds, the Company believes that the adjusted EBITDA (pre-opening costs) out-turn for the year is expected to be broadly at the same level as last year.
That doesn't sound too bad. However, the company's opened 5 or 6 new sites, so we should expect EBITDA (a proxy for cashflow, which is useful in this sector) to be up on last year, not slightly below.
Roll-out unaffected - how you see this depends on your point of view;
The Directors remain confident in the underlying strength of the business, its brands, the strong customer proposition and the business's capability to deliver high returns on invested capital. Consequently, it remains the plan to open six new bars in the next financial year.
A bear on the stock might suggest that the company stops opening new sites, and puts its house in order with existing sites. However, that would be missing the point. The point is that the pipeline of new sites are on exceptionally low rents. Hence, even if they take longer to mature than planned, new sites will still be highly profitable, and represent a very good ROI (which has historically been 38% for new sites).
Broker updates - I've seen 2 notes so far today.
One broker has downgraded its forecast earnings for this year by 12%.
Another has downgraded by 22% this year, and down by 17% next year.
Therefore a 34% drop in share price today seems something of an over-reaction, possibly. Although the lack of liquidity in this share doesn't help.
Valuation - last year's results showed £15.6m adjusted EBITDA. So it sounds as if we're looking at ballpark £15.0m for this year. That's a very cash generative business, with a market cap of only £70m.
Plus remember there's no net debt here, it has a terrific balance sheet.
That looks an absolute bargain to me.
Dividends - as this is only a mild profit warning, I imagine the divis are probably safe. So about 5p payout, would now equate to a 3.6% yield. Not bad, when you consider that most of the cashflow is used to open new sites. Therefore divis are just a bonus at this stage - but should grow considerably once the business is mature.
My opinion - the way I look at profit warnings boils down to one question:
Are these serious, structural problems (in which case I should sell up & move on),
Or, are these fixable, shorter term problems?
It seems to me that this is a good example of the latter. The main issue seems to be that costs have been allowed to over-run, probably because of disruption caused by 2 CFOs leaving.
A new CFO should make better cost control a key priority. That should then get profitability back on track. The main thing is that sales are reasonably OK - still positive, although a little softer. Margins are fine.
I really don't see any evidence of serious problems here at all. Management just need to sharpen their pencils, and work out how to mitigate cost increases better, as other hospitality operators are successfully doing (e.g. CAKE).
Overall then, disappointing, but at the current valuation, I think this share could end up looking very cheap indeed, once management has got the cost base under better control (which is mainly wages, in terms of controllable costs).
Gear4Music (G4M)
Share price: 723.5p (up 2.8% today)
No. shares: 20.9m after placing
Market cap: £151.2m
(at the time of writing, I hold a long position in this share)
Placing - there have been a couple of interesting announcements from this eCommerce company, specialising in selling musical instruments & audio equipment, globally.
I'm really pleased that the company has raised a small amount of additional equity funding. Indeed, at the analyst meeting last week, I urged the house broker to consider strengthening the balance sheet with a modest placing.
My feeling is that a very rapid organic growth business like this should have the financial strength to spread its wings. Often that requires some up-front cash costs.
So this is a good move. It's been well supported by institutions too - which is great, as new institutions coming in via a placing may become follow-on buyers in the market.
I think it was Mark Minervini who wrote that private investors should try to spot the small caps that the Institutions will want to buy in future. Institutions jostling for position in a growth share that is tightly held, can trigger a huge re-rating - as we've already seen here.
New shares - 610,000 new shares have been issued, at 690p. That has raised £4.2m in fresh cash for the company (less expenses).
Note that this is only minor dilution for existing holders - only about a 3% increase in the shares in issue.
Also note that the price was only a tiny discount to the market price, so again very pleasing, and not a problem for existing holders. It was said to be over-subscribed.
Sale shares - management have again cashed in some chips, with 839,000 existing shares being placed with institutions. Most of these (725,000) are the CEO taking some money off the table. Although to put it into perspective, his remaining holding is 7.16m shares. Personally, I don't begrudge him banking some profit - why not, after having achieved such a stellar result for investors already. He still owns 34.3% of the company, so massive skin in the game still.
A 12 month lock-in has been agreed by the CEO on his remaining holding.
Warrants - I hadn't realised there were any warrants in issue here, but it seems there are.
I can't find any mention of warrants in the last Annual Report. So I've put out a query to ask if there are any more outstanding, and what they relate to.
EDIT: Many thanks to MHP Communications, who have answered my query. The 100,782 warrants (exercisable at the original placing price of 139p - i.e. the original price when the company first floated on AIM) were granted to Panmure Gordon, as an element of their fees.
By exercising the warrants now, Panmures are paying £140k, and in return receive shares now worth £757k (at 751p per share, the current bid price). So a cool profit of £617k for Panmures - good for them! I quite like it when advisers put some skin of their own in the game - it shows they believe in the company.
I have also confirmed that there are no other warrants outstanding.
In my view these warrants really should have been disclosed in the Annual Report, but never mind, it's a historic issue now.
Reasons for fundraising - this is interesting, and it suggests an acceleration of growth plans, which I like.
The CEO says;
"We are delighted with Gear4music's recent performance, but there is much more that we want to achieve as a leading global retailer of musical instruments and equipment.
The Placing proceeds will allow us to accelerate our growth strategy, and quickly scale the business to capitalise on the significant growth opportunities within our markets."
That's music to my ears - badoom, tish!! (I'm here all week, try the veal).
More detail is given;
The Board believes that the Group is ideally positioned to exploit opportunities for further significant growth in its existing as well as new geographical markets. The Board further believes that, having regard to Gear4music's established track record of driving growth through targeted investment in the business, the proceeds of the Placing can be used to fund additional growth opportunities. With this in mind, the Board intends to deploy the proceeds of the Placing in the following areas in particular:
· Accelerated development of the Company's bespoke IT platform;
· Investment in international expansion, including an acceleration of translation activities and additional multilingual resource;
· Supply chain development and inventory investment;
· Further enhancement of the Company's marketing offering; and
· Infrastructure investment, including fitting out of the Company's new UK head office and further development of the German and Scandinavian hubs.
My opinion - this all sounds very positive.
We might have to accept lower short-term profitability, as a result of the accelerated growth plans. Therefore, I don't think PER is a valid way to value the shares during this rapid growth phase.
With more institutional buying likely, it wouldn't surprise me if this share continues rising.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

114 comments
Forgive me a political tangent, that struck me reading your analysis of RBG. The apprentice levy will, as you indicate, incentivise well run businesses to do with less staff, which will tend to be the less experienced. A classic socialist policy own goal from the Tories. Hmmm. What they should better have done instead, is encourage businesses that actually hired apprentices in some way. That would be financed from reduced social security payments.
What they have actually done is cynically introduce yet another backdoor tax, which will raise far more than will be contributed to apprentices. Unfortunately this will also reduce GDP growth.
I too use ATR, along with price channels. One thing I would add in relation to Revolution Bars (LON:RBG) is the spread, so me personally I would add 5% to my opening stop loss (say 10% + 5%) and then double it to set my absolute minimum for a short - term trade target (30%).
That equates to a c.160p target for Revolution Bars (LON:RBG) . I don't think it has much chance of that in any reasonable time scale, so wouldn't trade.
(just musing, I never trade shares with a spread over about 2%, usually less).
For the poster aiming for 15%, on an issue with a 5% spread that really is wasting your time, but each to their own.
I don't understand the arbitrary assignments of % either stop or profit: it makes much more sense to base your risk on units of ATR (average true range) - a measure of the volatility of the stock. That way you are grounding your assumptions in a bit of numeric analysis rather than gut feel or your personal risk appetite
Revolution Bars (LON:RBG) has just gone through a huge volatility event and will be prone to spikes in either direction: coupled wit that it has a relatively low float and trades less that 100K on usual days. ( I had trouble getting a quote and fill 5 minutes after open on high liquidity this am and it wasnt a big position (relatively)). Finally most fo that float are with big institutions who can move the price either way very rapidly given their relative volumes
For a swing position (days to weeks) a minimum of 3xATR is needed just to avoid getting whipsawed out of a position because of intrinsic volatility. 10% S/L at current price sets a stop at 12 points away from the entry. The 10 day ATR is 13 so a realistic minimum stop loss is 39 points or around 30%.
There are much more liquid and better behaved trading opportunities out there: trading reversals are hugely problematic and require enormous discipline and rigid risk management.
Revolution Bars (LON:RBG) could easily gap down or up on open missing any stops or targets
I meant to add that you can still risk manage for the same "target " absolute monetary loss by modifying stake size to incorporate ATR based assumptions of volatility.. i.e. buy a smaller amount of stock that is scaled according to likely ATR based potential loss
Dscollard... not sure who your comments are directed at but personally my stop is based on ichimoku support levels. That could mean that the stop is 12% or 5%. Whichever it is I'm looking for a price target of at least 3x the stop distance.
Indeed a small stop might mean I'm stopped out quickly but that will be because the price has broken a significant point of support plus I'm looking for breakouts and if the price has turned south I've probably got my timing wrong.
Best of luck
Phil
it was a general observation on using very tight stops in highly volatile situation. Ichimoku is essentially based on moving averages which are by definition lagging, it works well in strongly trending markets : in a scenario with a huge price dislocation such as Revolution Bars (LON:RBG) then even the fastest EMA will struggle to allow for a 40% drop in one day.
All systems are good until they are not and the physics of price action tend to prevail, I am more of a fan of price, volume and time as they are the only absolutes and are free from dogma
I have different positions on different stocks. Still running AMO at over 100% profit.....TET 20% profit in five weeks.....happy to take 15% profit on RBG
I don't think a 15% gain from here is being greedy. If you have a stop loss of say, 20% on RBG then I'll be aiming for atleast a 60% gain.
As they say, stick with your winners and ditch the losers
James....because I am not being greedy...and 15% for this share is just dandy.
Interesting strategy ...
You seem to be running losers and cutting winners!
When deciding if I want to buy into a stock I first find a stop loss position which is usually less than 10%. Then I use point and figure charts to generate price targets. Then I discard any stocks that generate risk reward ratios of less than three. I too would be looking for at least 30% with a stop of 10%.
Each to their own!
Why only 15%? If I was entering at these levels I would want a bigger reward for the risk.
I am looking at this from the perspective of how busy are the bars.....are they becoming unpopular.....what is the potential downside.....and also taking on board the fact that the recent announcement does not reflect well on them.
Having asked around...and knowing the Cambridge bar....still busy.....not becoming unpopular....often aiming for sites with a student or young market....which is a self refreshing customer base. Potential downside seems to be therefore pretty limited...in light of the large fall.
So....for what it is worth I decided to buy in....and have set myself an objective of making 15% in the next 12 months....whether that be through a short term-predator......or a gradual recovery over that time.
Should the dividend remain as is....that would give a yield of roughly 3% I think...which is just a little bonus.
"have set myself an objective of making 15% in the next 12 months"
Why would you set yourself an objective over which you have no influence? It's a bit like me setting myself an objective of it being sunny tomorrow.
I phrased it badly....that is my selling price.....I never buy a share without having a price I will sell at....unless it is a long term hold.
If you think about it....none of us ever have any influence over shares we buy...so your comment is a little.....strange in some ways
thats a bit rich coming from someone who calls themselves 'expecting value'. theres nothing wrong with setting price targets. and before you say it, yes i am a 'true gent' in real life ;)
Expect but never deliver, maybe :)
I think the real question, leaving aside the numbers, is whether there is a market for a high-end, national, cocktail bar venue?
Add into this mix that a) real wages are getting smaller (thanks to inflation headwinds), b) consumers tightening their belts and c) other costs increasing, to me it doesn't paint a rosy picture for RBG. And any such venues are notoriously fickle as the customers they attract quickly change their minds, e.g. has there ever been a considistently profitable chain of nightclubs?
Good luck to all holders - undoubtedly there's an opportunity to make money in stocks like these but personally I'm not convinced that they are a long term hold. I don't hold but have held companies like clapham house group - initially did well then it came crashing back to earth. Now, in the sector, I prefer someone like Fuller Smith & Turner (LON:FSTA), relatively low gearing, market leading products, excellent sites. Yes it will never offer explosive growth, it's unlikely to double in six months.
Just depends on your investing style. After a quarter decade of investing and, occasionally losing money on serious 'dogs', I now prefer the slow and steady approach, and only allocate a small % of my portfolio to highly speculative shares.
I have been reading this thread with great interest as I was a bit bearish a few months ago thinking that they may have a few ultra profitable units but their expansion plans were a tad unrealistic. I also suspected a long tail of iffy ones and a problem in finding sites of a suitable profile for further expansion.
I have asked an acquaintance who operates in this market what he makes of them and his quote was "I don't know them personally but they are superb operators and I think this is just a bump in the road". He also mentioned that they needed the right FD. He is a very discreet character so i presume he has heard something to confirm this view.
With this in mind I am going to open a position as the sell off does seem overdone.
A couple of curiosities which are probably due to lax updating, but are still curious.
The Linkedin page that I looked yesterday for Sean Curran (previous FD to most recent resignee) states that he is on gardening leave from Revolution bars with a date of Nov 2016 (he terminated his position in Sept 2016). Gardening leave is a curious term in the circumstances of having resigned. Maybe they didn't want him going to a competitor in his notice period, or didn't want him to work his notice, so put him on gardening leave. But you wouldn't normally put it on your Linkedin page, and then leave it like that, would you? Just seems a bit odd generally.
Can't see anything that links Sean Curran to other business interests at Companies House, but he left to pursue other business opportunities . But others might have more knowledge than I where he went afterwards.
Revolution Bars Group has a couple of subsidiaries that have not yet filed their accounts, and have an overdue accounts filing red flag attached to them at Companies House. Now, maybe the most recent FD assumed this had been done, or was rather focused on the Group accounts and forgot the subsidiary filings. Occasionally it can mean they have been sent to Co. House, but not been received. Generally, however it means a £1,000 fine for Companies House for not filing. Maybe this also speak to a slightly muddled reign by the most recent resignee?
Further to (Paul & others) comments on the opportunity to improve Foods, here is an article about the new Direct of Food at Revolution Bars (LON:RBG) . McDonald was formerly MD at Bills as it rolled out 68 new outlets according MD of RBG McQuater. (Uneasy lies the crown........)
Interestingly, looking at Bills menu not only does the food look good but their is a choice of (only) 15 cocktails - classic "offer an apparent choice but actually limit it for efficiency) . Clearly he should have very relevant skills.
http://www.hospitalityandcateringnews.com/2017/05/revolution-bars-group-appoints-scott-macdonald-as-director-of-food/
For disclosure, I hold and will buy at current super low prices in the expectation of coming up smelling of roses in 2-3 years time!! Some divis and a slow recovery likely to be the journey. For now I nurse my losses.
The leases typically have 5 or 10 yr breaks but upward only rent reviews, any reverse premiums or incentives are spread over the initial period of the lease. As the estate matures this will become a key valuation metric, i.e. what will rents reset to and what refurbs will be required to keep formats fresh
Hth
With RBG, I am amazed that many people are still focusing on trying to work out what is going on, rather than asking why RBG have gone out of their way to be unclear in terms of the information they have provided. If its a short term problem, which it still could be, surely the company would be going out of its way to highlight exactly what has happened in great details and what they are doing to resolve it... ...not leaving investors mystified. All IMHO.
Cheers, Martin
This is why I reckon there could be a 2nd profit warning. They not been clear at all in their statement and I feel they could be covering up more..
I am not a trained accountant, so would appreciate comments on a couple of things I am trying to think through whilst looking at RBG as an opportunity.
Firstly, whilst it may be correct in accounting terms to show that RBG have 0 net debt, is this a little disingenuous when they actually have 60+ long leases on their books that presumably have no break clauses - so effectively these act like long term loans with quarterly payments in advance (albeit I guess there will be turnover aspect to this)? My questions is, if these lease obligations were included as "normal" debt items / bank loans would this make the investment rationale look very different?
Secondly, do RBG account for profit assuming that current rent free periods are a £0 cost, thus inflating near term profits, or do they smooth these out over a longer period, so that a newly opened bar still has to cover its "normal" rental payment post rent free or capital contributions from the landlord.
Appreciate your thoughts
It's probably better to say "currently" correct in accounting terms because this will all change soon.
For accounting periods starting on or after 1 January 2019, change to accounting standards mean that all such leases will be treated like debt, i.e. a liability to recognise future lease payments along with a corresponding asset, both of which reduce over the life of the lease.
In terms of financial analysis, this will show an increase in debt as well as reduce return on capital employed. Whether or not you take that into account or it affects your investment thesis is a different matter, but such adjustments are already made by many professional analysts and credit rating agencies. It aids comparability between businesses who choose to finance their assets in a different way. Some retailers who have large leased estates already reported lease adjusted metrics.
Rhomboid has already answered this correctly. Under accounting standards RBG would have to spread the benefit of the rent free period over the life of the lease, so the newly opened stores will not be over-reporting profits as a result. This is what it means in the accounting policies section of RBG's annual report where it says:
I have been watching Revolution Bars (LON:RBG). For a while and for me if their next statement provides a more detailed report of numbers that dissapoints, how much could that depress the share price? considering today's mild unclarified statement has smashed the share price.
It's a negative view I know but we have to be objective.
I agree as long as sales do not go into reverse. Then the operational gearing (ie fixed rents) would kill the cashflow.
In the last week I have been to Ask Pizza, where the new pizza menu is awful and I went to Wildwood which is trying to be everything to everyone. I was surprised by how poor the offering was in both and how expensive they have become (£12 pizza's!). I guess if you have a few cocktails then you aren't so fussed about the food, but there is clearly an opportunity here for these guys to up their food sales.
I am not keen in the short term on the idea that they will be using the cashflow to open several new sites, 1 or 2 is fine but they should be concentrating on sorting out the labour issues, improving the food side and putting some cash in the bank for a rainy day fund.
IF IF IF they can maintain Ebitda at £15 million and throw off around £10 million in cash post capex and tax then clearly £60 million is very cheap. The next 6-12 months will be critical.
Looking at the Annual report to understand why trade receivables are so high (for a bar!) I found that most of them refer to development cost prepayments of £6.4mm. So it appears that (at least for this year) they are bound into significant ongoing capex.
I don't think all of that £6.4m will be development costs, the comment in the annual report isn't that specific:
I think it's likely that some of this is the quarterly rent prepayment for all the leases. Their rental payments for the year were just under £8.4m so in rough terms, one quarter of that would amount to £2.1m of prepaid rent, given that the year end date falls just after a quarter date. Business rates, insurance and some of the other ongoing premises costs will also give rise to prepayments that are not development-related.
Most interesting part of the admission document was that 25 bars accounted for 86% of ebitda. So 35 plus account for f*** all. Might as well close them.....
I asked the CEO about this point, and he said that due to successful new openings, the profit concentration had since reduced. They're also adamant that they don't have any loss-making sites. But as you say, it does mean that there's a fairly long tail of sites that are not making much money.
This is the beauty of the roll-out though - as the new sites are coming on amazingly low rents (many are former HMV sites that have been empty for a long time).
I think part of the problem is that the cocktail-driven offer is very labour-intensive. I was surprised at how many staff they had on duty, when I visited the Rev de Cuba site in Reading a little while ago. Chatting to the staff, they mentioned that it is labour-intensive making cocktails.
So I think the company needs to do a full review of products, and simplify the cocktails menu - focusing on cocktails which are simple & quick to make.
There's great potential from improving the food offering too - I've not heard any positive comments about the current food offering. People seem to think it's average (at best). That's clearly not good enough, but it provides upside on the shares. The CEO admitted this at the last analyst meeting, saying that future LFL sales growth should be achieved from an improved food offering. They appointed a new head of food recently, I believe.
Even with cost headwinds, EBITDA in future years should be (at least) stable - as new sites cashflow should at least offset reduced cashflow from existing sites.
There's a lot to like here, if management get their act together. So possibly not much immediate upside (unless someone bids for it), but should be a decent recovery situation.
I quite like situations like this, where fundamentally sound companies hit a rocky patch, as it can create superb value, as investors get so emotional after a profit warning. Much better to just put the emotion aside, and focus on the numbers. Bottom line, this is a business that should be able to produce at least £15m EBITDA, and probably more, from now on. Yet the market cap (with no net debt remember) is only £60m.
I appreciate the sector is out of favour at the moment, so I'm probably wasting my breath here!!
Regards, Paul.
On the food issue; my son who is a chef had said they were improving their food offering so today I popped into my local (Brighton, Sussex) for lunch and enjoyed a penang chicken curry which was frankly delicious.
The venue is spacious with two large bars, a clubbing area downstairs and an equally spacious garden area out back and all of this in the bullseye of Brighton's night life area.
I briefly eavesdropped on what sounded like a training evaluation meeting.
So there's my six pennies worth. My only complaint was that I had inadvertently visited on a "half price Monday" and my lunch was too cheap!
Revolution Bars - I'm not sure why cost over-runs were not apparent when the Interims were reported at the end of February (when the CFO reported that everything was in line) but have suddenly surfaced now less than three months later. It simply doesn't stack up in my view.
Surely it must have been obvious in February (which is after all eight months into the current financial year) that there was a potential problem looming. If not, then serious questions must be asked over the robustness of the Company's financial controls.
Let's hope that lessons are learned very quickly and that this mess is sorted out
I don't hold any but RBG has been on my watchlist for a long time, so i have spent much of today wondering if and when to buy. Suffice to say, the more I researched the less sure I was.It may be too soon yet. A slight rally soon led nowhere by the end of business.
I was very impressed when I went to the RB in central Birmingham a year or so back and have used it more than once since. It seemed very in tune with the 40 year old lawyers who first took me there. Although I have to admit I like the booze they serve and the snacks, my wife is less impressed, so I retain an almost guilty liking for the place. My only worry would be that it will, fairly soon, become dated and it looks to be appealing to a limited niche market.
I agree that in outline this is a mild profit warning. But thinking about it more, I find it a little bit hard to believe that the change of FD did not play some part in matters.
I am not suggesting anything untoward, but the last FD stood down on 6th May, and the Interim was an incumbent who took over, pending either their full appointment or the appointment of another.
What if there was a difference of opinion over treatment or accounting of costs that effectively got flushed out when he left. The previous FD could have 'under provided/accrued' for certain costs that he thought were a matter of timing, but which the Interim FD felt differently about. Maybe they didn't want to get beaten up on the issue by either a later appointee, or maybe they were just naturally inclined to be extra prudent.
Its not hard to think that some internal politics might have been flushed out by a new appointee.
What if there was a difference of opinion over treatment or accounting
of costs that effectively got flushed out when he left. The previous FD
could have 'under provided/accrued' for certain costs that he thought
were a matter of timing, but which the Interim FD felt differently
about. Maybe they didn't want to get beaten up on the issue by either a
later appointee, or maybe they were just naturally inclined to be extra
prudent.
I think you are right trident, this is much too big a miss to have really happened in the last 4 months of the year.
Going back to my earlier thoughts on H1 & H2 and overlaying the Numis forecast (had expected 12% increase in ebitda) gives
EBITDA H1 H2 FY
2015/16 8.1 7.5 15.6
Numis fcast 9.2 8.3 17.5 (+12%)
New view 9.2 6.3 15.5(broadly flat)
That surely can't be a £2m (36%) miss in the last 4 months?
This might also explain the jumbled wording of the announcement - I would imagine that the CEO would object to the phrase "because the former CFO was an F-Wit" as it might reflect on him too. Whether or not the former CFO loves his family so much if he hadn't left when he did, he would have left today!
Not easy to see how the CEO can stay on either given that today's announcement seems to be woefully incomplete.
All this said, even on a worst case view of the forward numbers, this doesn't look expensive nor at risk of going bust - but unfortunately I do not think that we can trust the management so I cannot see any upside until there is a full and honest explanation from the management or heads roll.On balance I think I am going to hold on to my small stake here as I don't think there are problems here that cannot be resolved by a competent management team. ( )
Revolution Bars (LON:RBG) ended the day at 121.25, down 40% on the day on a mild profit warning, this looks well overdone to me, so I have bought a few. Yes will be interesting to see if directors buy any.
If I was Director and I saw startling value I might be tempted to buy a few. Director purchases should not be trusted if nominal, and obviously even Directors with inside knowledge can make mistakes, but could be a signal yet to come?
Numis is the Revolution Bars (LON:RBG) house broker, reckon the target of 265p might be optimistic now
Revolution Bars (LON:RBG) does seem to be forming a base around 126p : it is 66% held by insits so wondering where all today's volume has come from ?
- a typical day is around 80K, today is around 4.5m shares so far. May well be some TR1s to come then as 4 big holders have(had) almost 50% of the shares
Tempting as a trade. liquidity may be above normal over the next few days
some fairly chunky buys too and a nice volume profile around the 125p level ... reckon I'll reach for the falling knife ... what's a few digits anyway ;P
took myself out in the opening liquidity: no legs in the brief relief rally, price action is still fairly bearish and bottom picking tends to be messy ( and best left to monkeys as one of my rules says). Reckon this is probably one for the long haul but this is not my area of expertise; I don't even do much "field" research in this sector these days so little experience either. Hospitality may be cruelly affected by Brexit given the multiple whammies of input costs, inflation, lack of immigrant workers and consumer confidence
I was wondering where the volume is coming from too.
I found a page on the company website (https://www.revolutionbarsgroup.com/investor-relations/shareholder-information/major-shareholders/) which gives major holders as having nearly 80% of the stock. True it's as of Sept 2016 but it did make me wonder whether there were a lot of private investors (who hadn't done their homework properly, just following discussion boards) panicking.
There's a lot of institutional names there who've got their homework wrong if not.
I've doubled my small stake at £1.27 odd.
It's not a venue I would want to go to but just like Greggs, you shouldn't discount how popular is it. Yes I live in Newcastle!
Making comparisons with London is difficult because London isn't like anywhere else in the UK but outside the metropolis people do like going out and having a drink. There are lots of people in uninspiring jobs who are prepared to blow their cash to have a good time and currently it seems like quite an attractive venue, especially with its extended opening hours.
I'm prepared to give them the benefit of the doubt for now.
this is current
Thanks. Is that freely available, if so where from?
it's from SharePad, I get that free because I use ShareScope as I am both trader and investor: I just manage my modes. SharePad has a separate subscription but I don't know the cost
Thanks
Looking at RBG's 5 year performance this trading update is par for the course.
Since 2012 they have grown sales by approx. 2% per year & assuming they do hit their revised guidance, profit will have increased by £300k in 5 years.
Paul is right. If the price stays depressed for long enough, a bidder could be interested
How far does your confidence stretch Paul? Surely the decision must be either to sell or to add. Doing nothing doesn't seem a logical alternative to me. Based on your comments I assume you are adding or have a price in mind at which you would?
Hi Cousinjack,
Yes, I've been adding to my RBG position today.
The valuation is now down to 4x EBITDA, which I think is super-cheap for a (still decent) roll-out.
Management clearly need to tighten up financial controls. But there are other things that should help improve LFL sales too - e.g. a drinks ordering App which is due to be launched soon. Plus the food offering could be drastically improved - and mgt are aware of this, and are in the process of revamping that. There's a good opportunity to develop the Rev de Cuba sites into proper casual dining, plus bar sites, which could trigger a re-rating.
As an aside though, I don't necessarily think one has to buy or sell. Holding is a perfectly viable option when something is finely balanced.
Personally I just try to take the emotion out of it, and re-assess the numbers & prospects. In this case, clearly some schoolboy errors were made in forecasting & cost control. However, the roll-out is still attractive, therefore my reason for being in this share (that it will be a much bigger & more profitable company in 5 years' time) is unchanged.
The divis look safe. There's no net debt. In my view there's still lots to like here, yet it's now 40% cheaper than it was yesterday. I think the problems are fixable, and it should then recover.
I appreciate there will be a variety of views, and dumping the shares and moving on is a perfectly valid strategy. I've always had a long-term view on this one though, so for me it makes sense to add to my position at this depressed valuation of c.4x EBITDA.
New sites will bring additional profitability, so even in a downside scenario over the next few years, profits should be flattish. I'm hoping for a much better outcome though, with management hopefully getting their act together to fix the problems.
Regards, Paul.
Hi Paul
What makes you think RBG "will be much bigger & more profitable company in 5 years time", when it is the same size & making the same profit as it did 5 years ago ?
I notice that a few people have been having a pop at management for not doing better. This seems a little unfair.
When you look across the pub/restaurant sector, many of the major players have hit trouble. Tasty (LON:TAST) Marston's (LON:MARS) Mitchells & Butlers (LON:MAB) and others have also warned on profits, attributing the trouble to weakening consumer demand, food/drink price inflation, rates increases, and wage hikes. You cannot mitigate against the level of the minimum wage, food/drink prices, and rates.
Fortunately I sold my RBG shares on the suspicious weakness of a couple of days ago, after the mini recovery from the 190's, with my sales encouraged by the opportunity to purchase CAKE shares after their very decent RNS.
I am perhaps being overly cynical but if some of RBG's statements today are not written clearly or, are clear but, make no sense, the last thing I would want to consider doing is giving management the benefit of the doubt as to what is going on. Any lack of clarity from management is not an accident... ...it is a deliberate decision... ...and IMHO a far from good sign. Just the sort of stuff that could be referred back to in a future negative RNS giving chapter and verse on their problems and their inability to solve them.
I hope for holders that this proves not to be the case.
Cheers, Martin
so agree. the lack of clarity given in the update is deliberate. everyone is making educated guesses rather than knowing absolute facts.
Looks like the investors have been to an RBG for lunch and enjoyed their Cuba Libres so much they decided to buy the company. I opened a spread bet about 1p off what I hope was the bottom... and am currently a whole 92p in profit. Good luck all!
apprenticeship levy, minimum wage, business rates, declining consumer spending power, inflation, fierce high-street competition, input costs from the declining pound all point to a difficult situation for the foreseeable future particularly for premium bar outlets...?
Hi Paul, moving away from vodka bars to an area which your readership are probably more familiar with: movies, guitars and PCs, any views on Future (LON:FUTR) (Future plc) earnings announcement today?
I would normally shy away from looking at "old" industries (i.e. publishing) but they do look rather positive (although some growth has come through acquisition) and the digital transition seems to be going well. Ticks all my boxes in terms of strong increasing revenue and PBT, cash generative, low debt, and probably below the radar.
I think the share could be in line for some further broker upgrades and a subsequent re-rating. Very tempting...
Some highlights for 6 months below include:
- Group revenue increased 35% to £40.9m (2016: £30.2m)
- Adjusted operating profit increased by 375% to £3.8m (2016: £0.8m), more than the £2.8m achieved in the full year FY16
- Adjusted EBITDA* increased by 140% to £4.8m (2016: £2.0m), reflecting margin expansion and Media division revenue growth
- Statutory profit before tax increased significantly to £0.9m (2016: £0.3m loss)
- Adjusted EPS up significantly to 9.3p (2016: 2.5p)
"We have delivered another strong performance with substantial increases in both revenue and profitability, driven by organic growth and acquisition. We are seeing clear benefits from our operational gearing and we continue to focus on cash conversion."
Readers comments welcome if anyone knows this Company !?
watch out for the big buys to come in at 16:30 maybe?
Crikey, all the talk of the fall being overdone but it's now 125.5p to sell. Bottom fishers haven't done well thus far. Looks like a big institution dumping.
RBG. I may be being over-serious, but what about the basic theme concept of this chain? Could that be at fault? Isn't the whole Cuban Revolution a little naff, if not completely discredited? Did Castro not die a billionaire? Can anyone sit and drink a Cuba Libre under a Che Guevara poster (yes, they have them) without looking like a complete buffoon?
Quite the opposite, I think a bit of intelligent yet light hearted humour is exactly what we all need today. Thank you.
I think there is no golden rule for what to do when a profit warning happens, but I always examine how much content is involved with the warning. The more content, context & figures the better.
Take NCC for example - their recent profit warning "The Board has reviewed its third quarter performance to date and the expected financial outcome for the full year ending 31 May 2017. As a result of this review, the Board has concluded that the performance of the Assurance Division will be significantly lower than previously anticipated.The Board now anticipates that the Group's full year adjusted[i] EBITDA will be approximately 20% below the £45.5m to £47.5m range, which it published in the trading update announcement on 13th December 2016"
If you bought them on the day of the warning, at 107, you would be sitting at a tidy profit at 166 today.
the RBG update just strikes me as they dont actually know what the updated figures are going to be, nor what is causing it.
I do wonder whether the Revolution Bars (LON:RBG) statement was rushed out a little on the back of what superficially appears to be insider trading on Wednesday.
Paul - I was reading Phil Oakley's article on Revolution Bars (LON:RBG) again this morning and one of the cautions he makes of results presentations is that the EPS figures exclude "bar opening costs from underlying EPS numbers". As an amateur investor I am not yet sure whether it is better to value a company on basic rather than adjusted EPS for more established roll-outs like Revolution Bars (LON:RBG); after all roll-out costs are likely to continue for some time. Any thoughts?
(I'm long and topped up this morning albeit a bit too early!)
One thing to be wary about, when considering small changes in LfL sales numbers, is that it's incomplete information. What matters from a business point of view is volumes. If they're increasing sales prices to compensate for falling volumes, it's not visible and may show as positive LfL, but can be a precursor to a much larger problem.
BrianGeee commented;
"One thing to be wary about, when considering small changes in LfL sales numbers, is that it's incomplete information. What matters from a business point of view is volumes. If they're increasing sales prices to compensate for falling volumes, it's not visible and may show as positive LfL, but can be a precursor to a much larger problem."
My reply - I'm not sure you're right there. If a company can increase its prices, and still report LFL sales growth, then surely that's positive? Who cares about volumes, if gross profit is rising?
My main worry with LFL sales figures in isolation, is that the opposite might be happening - i.e. the company might be discounting heavily, in order to increase volumes & attain LFL sales growth. The problem with that scenario is that the gross margin would take a big hit.
In today's update, RBG specifically says that margins are as expected. Therefore the 1.7% LFL sales growth, combined with sound margins, is absolutely fine.
The issue with RBG is costs over-running. I still cannot fathom why they were not modelling & managing their costs correctly, given that all the factors pushing up costs were known about beforehand.
Hence why for me, this seems very much like a situation where eyes have been taken off the boil. There's nothing wrong with sales or gross margins. It's the costs that are too high - principally wages, which is a huge percentage of RBG's overheads. They need to mitigate, in the same way others are doing.
Regards, Paul.
"... eyes have been taken off the boil."
Crikey. Someone's having an exotic lunch. I recommend keeping them simmering for at least 6 minutes to keep them tender.
"I'm a Smallcap Investor Get me Out of Here"?
Revolution Bars (LON:RBG)
One of my big concerns in the statement is lack of clarity. Paul highlights a number of statements that don't appear to make much sense and those type of things really worry me.
The message is that turnover and gross margins are okay (although as Paul shows the turnover growth is slowing), so the issue is "all" about costs (predominantly staff).
It should be possible to scale the size of the miss (I haven't got any forecasts to hand, but will look at that later).
They say adjusted EBIT for the FY should be "be broadly at the same level as last year" - ie below.
Adjusted EBITDA last year was 8.1 (H1) & 7.5 (H2) for a full year 15.6
So day 15.5 this year (potentially lower) this gives a split of 9.2 (H1 reported) & 6.3m (H2)
H2 will be c. 1.2m (16%) below last year's and the forecasts were presumably originally for an increase so that is a big miss IMHO.
Especially as they gave no indication of this at all at the end of February so if the fall is actually happening in the last 4 months of the FY it's a much bigger fall yet!
I'm also troubled by this statement :
"whilst the underlying sales performance of these [new] bars remain on track with an average weekly turnover of £43k (net), these bars are taking longer to mature to full profitability than originally anticipated."
So the new bars are hitting the revenue targets (and presumably then GM also) but they're not getting the operating costs down quickly enough - given what was said elsewhere about initially over-staffing, does that mean they are having to retain these higher staffing levels longer? And if so why?
There's a tacit assumption there that these new bars will eventually reach their "in life" targets for profitability, but nothing in the statement really gives confidence that this will actually be the case.
Only a small position for me here and having decided not to sell first thing I think I need to give this more thought over the weekend.
It would certainly be helpful if the management could give a bit more clarity
I followed Paul's enthusiasm for RBG with interest but I have to say, I found this analysis rigorous and pursuasive. It's not by any means a demolition but I decided to wait and see if a lower entry point, perhaps as markets generally blew off a bit, would get me in at a better value. It's still a quality Business IMO, but having attempted a roll out myself once, I can say they rarely go smoothly.
I think this fall IS overdone but as I cautioned in a recent post on another SVCR, I am in the bars business and whilst 2016 was (at least for me) great, 2017 has not followed suit. It feels like the consumer is really holding back. All the industry analysis confirms the trend that people are going out less but that those nights out that do happen are becomming bigger, and in the case of the young, with multiple venues visited. I wonder if RBG is enough of a treat and whether it can hold or increase the dwell times.
Thr cost pressures are well documented but I have managed to proactively manage staff hours right down, to the point where we have mitigated most of the wage cost pressures of the last couple of years. But this has reached the max. To maintain net margin, prices may have to rise - or of course you could sacrifice GP for more volume - always a tough call, and risky. 1% LFL sales increase will NOT be sufficient to mitigate all the comming cost pressures.
I do think that if the share price stays around 130p, it will be in play before long.
It amazes me how people are willing to push their chips in with such uncertainty. There are so many more solid opportunities out there but people can't help but see 30% discount and think BARGAIN!
Also the comment about the CFO leaving and saying it was to be closer to the family ... He's not going to say "I can't stand the CEO and the business model is broke" is he?
Like many MP's who come unstuck perhaps he found that he ought to pay more attention to his family or at least use that as a convenient story.
Perhaps I'm just cynical?
Commiserations to those that have taken a hit today.
Phil
I completely agree Phil. I think the problem is that most people's natural instinct is to buy weakness when they should be buying strength. It was mine too until I read Minervini and others. People love a "bargain". My feeling is that a lot of people make the mistake of treating stock investing similarly to buying bargain products at a supermarket.
Stockopedia study showed that buying on profit warnings is a losing strategy over the long term (Boohoo.Com (LON:BOO) was the exception rather than the norm). Also Paul Tudor Jones's "Losers average losers" quote comes to mind.
A more recent example is Gattaca (LON:GATC) which bizarrely has actually gone higher than its SP before the profit warning!
Hi PhilH,
You're barking up the wrong tree there, re the CFO leaving.
It was obvious at the last analyst meeting which I attended, that there was excellent chemistry between the CEO & CFO, and everyone was very disappointed that he was leaving, as indeed was he.
I often don't believe the reasons given in RNSs for someone leaving. But face to face, I can judge pretty accurately whether someone is being straight with me, or not. In this case, there was not a scrap of doubt in my mind that the CFO leaving was entirely for the reasons he gave - work/life balance with a very young family.
So yes, in this case, I think you're definitely being too cynical!
Always good to question everything though.
Regards, Paul.
Phil, Very, very good point. Something I always try to focus on. The best approach for investors is to find the best possible opportunities. Not to just buy into something because it has gone down.
There are lots of early stage good quality businesses at good valuations. Why buy into Revolution?
This basic thinking is what separates good investors from bad investors in my view.
Hi ratioinvestor,
Why buy into Revolution?
Perhaps because it's a tremendously cash generative business (even after today's profit warning), that is generating enough cash to self-finance its roll-out, plus paying a reasonable dividend on top, that is now dirt cheap?
This type of business is very attractive to Private Equity buyers - indeed it was floated by a previous PE owner.
Its ungeared balance sheet makes it highly attractive to a potential PE buyer. They could finance the bulk of the purchase price through debt. The existing estate is well invested (they revamped all sites a few years ago), so minimal capex needed on existing sites.
I wouldn't be at all surprised if a bidder emerges, if the price remains this depressed.
Understandably, sentiment is on the floor today. However, in situations like this, where the business is fundamentally very sound, it's important not to throw out the baby with the bathwater, in my view.
Regards, Paul.
Paul,
Interesting points but the question to me is can I get a better risk/reward ratio elsewhere? I personally think I can. Yes the question is whether the business is fundamentally sound. I think the update raises question marks about that. You could be right about this stock in the long-term but for me I wouldn't go near it. In my view, there is really no long-term competitive moat. I think where companies do well the offer something compelling and have a strong niche. I.e. Boohoo undercutting the high street and offering its own brand. If you read Dorsey "The Little Book that Builds Wealth" restaurants are a bad place to invest.
But I personally wouldn't have looked at this in the first place because:
1) Restaurants and bars have a very poor stock market track record as a sector. Low barriers to entry, tastes change etc etc.
2) You say this has low gearing but leases are effective gearing and make the costs of poor site selection or a brand losing its appeal very high.
3) Even if this is a "cash generative roll out" is the concept any good? There doesn't seem to be anything original or interesting here.
4) The concept is just bizzare. Revolution de Cuba or something. What does that mean? Serving burgers and Pizza. I.e. this is just a Hollywood style cheesy unauthentic theme.
Having said all this everyone has different views and I enjoy your small company updates. You called Boohoo very well when Tom Winnifrith wrote some bizzare piece saying it had had multiple profit warnings (in reality there had been only one).
Thank for the great analysis Paul. The market jitters this week haven't helped. Hopefully management can get improve their cost control in the next few months.
I was as gutted as you when I saw the RNS as my 18-year-old holds these in her ISA. Part of my plan to educate the kids about investment. I encouraged her to look for stocks she knew something about. Bars and clothes seemed to feature heavily! We've come to the conclusion that this has been oversold and she'll hold in there. Her comment over breakfast when I broke the news was "Well, no-ones going there at the moment as we've all got exams in the next few months". Profits should be back on track in July !
Paul, interesting comments and good of you to update. I seem to recall we spared over Revolution a while ago but I can't find the discussion page. I know this company has lots of fans but I think the restaurant sector is very tough. I also don't really get the brand/niche. It just seems like cheesy Hollywood concept. Just my view and other people may love it.
Thanks for the always helpful perspective. I originally bought into this share following a strongly supportive piece in the Telegraph's Questor column. A week or so later I was researching a place to eat with friends in south west London and came up with one of RBG's sites which I visited to check it out - for the food/location in the first instance. But I noticed that the whole place was very quiet despite it's excellent venue. But I booked a table for 9 and arranged for everyone to meet there for lunch. On the day, the bar was even quieter and on looking more closely just seemed a bit "down at heel". The food quite frankly was awful and despite the staff being perfectly friendly and welcoming, we all left agreeing that we wouldn't be visiting again. I subsequently sold my shares! I know one poor showing doesn't make the whole enterprise poor, but I was left with the overall impression of an eating place that had lost its edge. If this experience is one being repeated throughout the group, I'm not surprised that wider problems are starting to stack up.
Fake reviews are not confined to RBG. My research into distil group uncovered several cut and paste type reviews of their products on supermarket websites. I'm not quite sure of their significance but they stopped me investing.
Mr Market is a grumpy one today, looks like an opportunity taking a leaf out of Joel Greenblatt's Magic Formula book. I note its passing the Naked Trader Esq screen, that is certainly a positive for me.
To put my penn'rth in I have been watching for a while and decided to buy a small holding this morning after the 30% fall. Thank you for your commentary Paul very useful as it has steadied my resolve following the purchase. I wouldn't change my mind but it is nice to know there are others out there thinking like yourself. Isn't that one of the main problems with contrarian investing?? Anyway on the announcement as given I think this level of price fall is over done. I suspect the macro situation has made investors more jumpy and risk averse and we will see any disappointing announcements hit increasingly hard in UK small cap. Too many uncertaintys at present.
I doubled up on RBG earlier at 130p and will use this as an opportunity to go out for a few drinks in one of their bars tonight. I guess I can tell the wife I'm going out to look after some investments.
There's a good discussion on Revolution Bars (LON:RBG) going on over on http://www.stockopedia.com/content/rbg-fall-185338/
On Revolution Bars
It is difficult to judge this one. Paul's review makes a lot of sense. If these are the only problems they should be fixable. But management should have known about them for some time and been able to fix them.
The lesson I am taking from this is to listen to and not overrule my concerns. The thing I didn't like about RBG was the obviously fake reviews on Tripadvisor - lots of almost identical reviews of different bars, all with different names but a similar overall pattern. If RBG are willing to post fake reviews (or pay someone to do this) then how much can we trust their trading updates? I sold out when I saw this and then greed (not wanting to miss out on a good one) overcame my concerns and I bought back in again.
There are so many excellent investment opportunities out there at the moment - Accesso, Bioventix, SSP group, Breedon, Focusrite, Fulham Shore and lots more. Paul and Graham are a brilliant source of good investment suggestions (DYOR of course). No need to get involved with the ones that I am not so sure about.
Will I learn my lesson? Probably not. As Ed Croft keeps telling us, our psychological weaknesses will keep pushing us into making bad investment choices unless we are constantly on our guards.
I sold my remaining holding in RBG this morning. Overall I am doing well enough for this not to be too big a hit to an otherwise very good year so far.
I was concerned after reading fake reviews on tripadvisor , then when the dip started happning last week I just didn't like the direction it was going so sold out totally.
also have visited RBG at one of their sites this year, and it didn't strike me as something I would want to invest in ( I didn't realise this before visiting). the place was kinda empty and the atmosphere felt it was a place everyone was hoping would pack out so they could have some fun (few youngsters there)
no intention of buying back in, and I defo don't think this is no boohoo.com
Re RBG, in response to vik2001, post 23
Yes, that is the key test - a visit to the place. The good thing about investing in Bars and Restaurants is that we can check out the quality of the products and uptake from their customers. I remember years ago walking into an Apple Store. The place was packed. And the share price just kept climbing.
I didn't visit an RBG site because they were too far away. My losses are big enough that a day out would have been well worth while.
I also saw the share price decline and sold half of my holding yesterday, luckily one day before the profit warning.
I agree on the fake reviews. Happily they stopped me investing based on the Warren Buffet dictum "There's never just the one cockroach in the kitchen".
I see the red thumb brigade are out today. Bring it on! I just added added a red thumb to my own post too :)
All the best, Si
Remember it was a late Easter this year, one of my companies is a small bar restaurant hotel and we have suffered this year as it cramps all the bank holidays together, in addition the weather has not helped - people drink al fresco in the sun not usually in the rain. Extra costs are painful at the moment with food costs rising however spirit costs are static so as RBG handles cocktails as a big revenue source these should not be too badly affected. Rates are being phased in so these will go up annually and are totally unfair with no clear formula for me to understand why my neighbour who has 50% of what I have pays no rates and I pay £ 30,000. Costs will simply have to rise and my guess is with people earning more it wont have a huge impact unless you are state funded in which case you shouldn't be in a bar anyway.
What rain, we have just had one of the driest March-April's on record, yes it has rained this week.
In Norfolk rained all week and rest of month just not very nice weather, what I could and maybe should have said is that May has not been full of sunshine and hence not great to get people out. Less important anyway for RGB as they seem to be inside however the late Easter would have an effect
I'm in Suffolk. Yes April was a bit cold, May has been mixed but it was very dry until this week, had 2 large gorse fires near my place, that were burning for days, hopefully this rain will have put an end to that.
Seems to be a general downturn in spending this year.
You must be near the Lord Nelson then, (& the Harbour Inn). Tough life in Suffolk, isn't it?!
I'm about 2 miles away, can't afford those prices. Yes tough life.
Thanks for your very interesting comments and thoughts Paul. I did buy an initial position based on the big drop this morning. Keep up the great work...
There could be a risk at Revolution Bars (LON:RBG) that this profit warning is a sign that management have not been paying enough attention to managing the business and have focused too much on growing it. If so, there may be other problems to be uncovered once the CFO has turned over all the stones to see what's hidden. The recent Stockopedia research on share price performance after profit warnings leads me to decide not to buy more at these levels but to hold and wait for now.
The price performance and volumes ahead of the profit warning makes it seem (with hindsight) that some people knew before the RNS. Maybe we will see the second profit warning coming, if we watch the daily chart closely. I currently feel that I'll get out if we reach 120p and start considering buying more if we reach 150 on good volume.
Hi Paul,
Interesting to hear that your thoughts on the RBG profit warning are in-line with my own. Not all warnings are created equal and the issues seem fixable to me. I was surprised by the size of the drop having read and considered the RNS but you make a great point about the liquidity. I asked a question last Friday about private investors and leverage and that may also have amplified the fall.
It seems we are swimming against the tide of opinion round these parts. I only had a smallish holding and have bought some more. Some people seem to be comparing this with the Crawshaw rollout that went wrong. I don't see it myself but would be interested in your thoughts?
Have a great weekend! Si
Paul, thanks for the write-up. I am now an anxious holder having bought some more at 140-150p, only to see the price fall even lower. It seems people are not looking at the same way as Paul. Could it be they are concerned that forecast profits were previously way out even though the company would have known about the cost increases for the most part. So maybe it's a trust issue and/or sign the company doesn't know what's going on. I hope this proves to be wrong.
There are a few macro headwinds, like the fear of Labour putting pressures on the Tories to raise the minimum wage (and the likelihood of their raising national insurance after the election). Though this drop is ridiculous...
Paul
Re: Revolution Bars (LON:RBG). Appreciate your prompt thoughts. Must be a bit gutting. I have a small holding, but it has put a hole in my returns.
Obviously outside analysis is the only thing we have as a tool at this stage, but psychologically, it is tempting to say Ok not much wrong here. I think inevitably there will be some uptick as people perhaps see a market over-reaction, and go back in.
My main worry is that is Revolution Bars (LON:RBG) seeing something that makes their offering less appealing to the general public, as they roll it out further, and this plus additional costs and/or less well managed costs is taking the shine off.
As Paul says, it has a healthy balance sheet so the management are not caught in the terrible squeeze of excessive borrowings and poorer performance.
I will probably wait on the side lines a bit longer to see which way the wind is blowing.
Helpful review thanks and hopefully the drastic share fall is an over-reaction. I had sold 1/3 of my holding earlier in the week, at a small profit and rebought them this morning to try and soften the heavy loss on what remains.
Commiserations to Paul and others on Revolution Bars (LON:RBG). It's a case of where technical analysis saved me. It didn't satisfy Minervini's Trend Template criteria and I didn't like the double top around ~235p and the recent weakness.
Excellent commentary Paul but I think you may not be sceptical enough about what's being communicated, firstly the CEO is the driver of this business and vastly experienced, he knows how to keep costs under control & doesn't need an FD to tell him what to do. Bars report daily so these trends have been known for a period of time & all the obvious quick fixes will have been discussed & adopted but weren't able to get the results required in their business plan. That suggests it may not be just the obvious costs referred to in the RNS,
From the RNS " Additionally, two key sites were closed for just under two weeks for major refurbishment (Blackpool in March and Cardiff in May)" this wording suggests this was unexpected unplanned for downtime or it would have been in the numbers already. The implication for me is the format needs refreshing more frequently than they thought to keep turnover up. That has implications for maintenance Capex that could be a canary in a coal mine?
Anyhow I've never been a fan of the sector or the company so I may be being overly cynical!
Hi rhomboid,
I would agree with you if LFL sales were say down 4 or 5%. But they're not. LFL sales are still positive - not bad at all, when you consider the pressure on disposable incomes at the moment, due to higher inflation.
My feeling is that a lot of management time is taken up with the roll-out. It's not just 6 new sites per annum. Remember they have a pipeline of about 25 new sites, where detailed planning permissions & landlord negotiations are ongoing. Then when sites do open, they're quite big sites, with £1m fit-outs each, so a lot of work to do that.
It seems to me therefore, that eyes maybe haven't been fully on the ball re cost control.
If there were more serious problems, then I think that would've shown up in reduced LFL sales. In the current environment, still be up on last year is pretty decent.
For now, investor sentiment is clearly very negative, unsurprisingly, when any company drops a bombshell like this.
I have no plans to speak to management. The reason being that I think that could cloud my judgement (it has done in the past, where I've given mgt the benefit of the doubt, or had the wool pulled over my eyes). So when things go wrong now, I like to stay detached, so I can make the right decision on whether to buy more, hold, or sell.
Regards, Paul.
Hi Paul
one point in passing is that LfL is likely overstated by the unplanned ( assumed to be unplanned as they were given as part of the reason for shortfall?) refurbs at Cardiff & Blackpool.
Assuming they were refurbished because they were the 2 sites with the poorest trading (which would seem logical) then pulling them out of the LfL (as I assume they quite properly do so) will flatter the remainder..possibly to the extent of turning "real" underlying LfL negative? There's obviously also the cash cost of the refurbs hitting the balance sheet as well. It might be worth a holder asking some questions around the issues?
Fascinating subject ..chewing over the RNS!
Revolution Bars (LON:RBG) and on a Friday? worrying. I hope drarowen is right.
Seadoc
Reminds me a bit of boohoo Paul and we all know how that tirned out.
Paul,
Thanks for the very useful analysis and thoughts on RBG
On the plus side, £G4M placing seems to have gone well, Being so well received by the insts provides a nice floor to the valuation.
I wonder if you could cover FUTR please Paul? On an initial flick through the interims these look very good value... though I suppose there are a few exceptionals... price up 12% though
I too thought the news was indicative of management taking their eyes off the ball by not knowing about these cost increases, so sold half my holding at about 144.8 with a view to topping up again should the issues be fixable. The question is how fixable are they? How much scope is there to change the rosters?
Do you think the management would be up for one of your recorded interviews?
I think RBG management should parachute you in Paul as a troubleshooter. Are you hoping to arrange a meeting with them for some answers.....?
Here's hoping you are right Paul. I decided to double my (small) position in RBG this morning at a smidge under 140.