Small Cap Value Report (23 Jan 2017) - FLO, STHR, PPB, PHTM, BMS, MYSL

Good morning!
Today, I'm planning to look at Flowtech Fluidpower (LON:FLO), SThree (LON:STHR) and Paddy Power Betfair (LON:PPB), and anything else that seems worth covering. Paul is traveling at the moment.
When he returns to London, Paul will be meeting MySale (LON:MYSL), and I am also planning to cover their trading update from last Friday, later today.
Regards
Graham
Flowtech Fluidpower (LON:FLO)
Share price: 124,6p (-7%)
No. shares: 43m
Market cap: £54m
Trading, Acquisition, Strategy & Notice of Results
There's a disconnect between the tone of this announcement (positive) and the share price reaction (negative), because I think the profit guidance is actually a miss against market expectations.
Somewhat strangely, the company says that it is planning a 5% dividend increase, which is "in line with current market expectations" - but it doesn't say that the profit guidance is below market expectations!
Against difficult trading conditions the Group has delivered a solid performance.
Group revenue was c.19.9% up on 2015 at approximately c.£53.7 million (c.19.3% in constant currency)
The GBP devaluation looks to be culpable:
"...some margin contraction was experienced in H2 while prices were managed upwards on products sourced in Euro and USD and sold in GBP markets.
Checking last year's annual report, I see that Benelux revenue was c. €5 million, versus £30 million in UK revenues. And the underlying operating result from Benelux was less than 10% of the UK result. I'm not sure how this has changed since then, but there is a lot of GBP exposure here.
Significant investment in central and sales resources aimed at optimising cross channel opportunities, and future acquisition integration programme underpinning long term growth.
As a result of these investments and the gross margin contraction in H2, the Board expects underlying* PBT will be in the range £7.0m to £7.2m.
According to the forecasts available to me, £7.6 million was the consensus forecast here. So it's a miss.
The company also announces the acquisition of a Shropshire-based hydraulic equipment distributor for total consideration (including debt assumed) of £2.65 million. There are said to be "several acquisition and product opportunities being actively pursued".
My opinion: More important than the valuation here, for me, is whether I buy into the strategy.
Some companies have grown successfully via multiple acquisitions, but it's not a style of management which I wish to take part in for now - too many things can go wrong, and it's almost impossible to judge how much integration will cost in the end. It can take a long time before the hypothesised synergies eventually materialise.
Indeed, today's statement attributes the company's "future acquisition integration programme" as being partially responsible for the lower PBT forecast.
So I'm going to express my preference for organic growth by not getting involved here.
For what it's worth, the Stockrank does consider this share to be good value.
Share price: 311p (-3%)
No. shares: 128.9m
Market cap: £401m
Final Results for the year ended 30 November 2016
There are times I wish I traded more actively. Looking at the SThree (LON:STHR) chart, a STEM recruitment group which I've studied before a couple of times, I can't help the feeling that Mr. Market is far too jittery on this stock - it was marked down from 400p in July 2015 to a low of around 220p in October 2016, before recovering to the current level.
A lot of this was Brexit-related: SThree earns 49% of gross profit in Continental Europe, and is also quite sensitive to economic and legislative shifts in the banking sector.
In the end, 2016 results have turned out very flat:
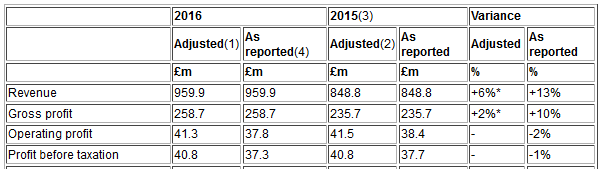
The increased revenue figure is due to the increased focus on Contract, rather than Permanent employees, and FX.
It's a highly detailed announcement - this can be a refreshing change after analysing smaller companies!
Outlook: Despite the high level of detail, the company admits an uncertain outlook (somewhat inevitable, given the nature of its activities and the markets in which it operates):
This has been a year of unexpected developments in several of our key
territories which are likely to impact the future trading environment.
The changed political landscape creates global macro-economic
uncertainties which make this a difficult environment in which to plan.... we will continue to adopt the prudent approach to planning
which has served us well in recent years, but remain poised to respond
quickly to opportunities when they arise.
My opinion: I still think this is a good recruitment business, and I like the strategy of focusing on contract recruitment (now two-thirds of gross profit).
Recruiters are like most brokers (stockbrokers, real estate agents, etc) - they thrive off activity and change. Contract workers are the most active in the job market, so it makes sense for recruiters to gear their business towards them.
SThree has a special model which employs contractors directly, and contracts them out to clients - this looks smart, from a legal/tax point of view.
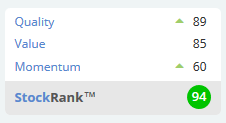
The PE ratio is a little expensive for a recruitment business, but it seems to be offering a decent proposition, in my view. The StockRank is 98.
Share price: 8350p (-4%)
No. shares: 83.7m
Market cap: £7,030m
This is an update for Q4 and for the calendar year 2016 as a whole.
It has been an unusual quarter: customer-friendly results in politics (Trump) and sport (football) resulted in revenue reduction of £40 million.
Note that the above figure is "before the benefit from the re-cycling of winnings" - gamblers tend to bet with their winnings, sooner or later.
Think of PPB like an insurance company: occasionally, there are hurricanes and floods, and the insurance company (or its reinsurer) takes a hit. But that's necessary, to occasionally boost the demand for insurance policies (and to wipe out insurance companies which are pricing their policies too cheaply).
A few adverse results go with the territory here.
Total revenue for 2016 is up 18%, or 11% at constant currency (using pro forma results as if Paddy Power and Betfair had always been merged). That was achieved despite a flat result in Q4. Nothing to panic about here, in my view.
Photo-Me International (LON:PHTM)
Share price: 154p (-10%)
No. shares: 376.4m
Market cap: £580m
Shares were down by almost 20% at one point this morning, giving a trading opportunity as they are now down by just 10%!
The above-linked RNS has been released in response to newspaper articles saying that it may be "curtains for photobooths" - as Home Office rules no longer require photos by a machine or a professional.
These were introduced some time last year, but have only now made it into the media.
Response from PHTM:
The Company believes its latest technology represents a major growth opportunity as the most secure photo ID solutions available and that accepting photos from mobile phones for official documents is incompatible with developing security requirements.
Photo-Me's solutions have been adopted by
ANTS (Agence Nationale des Titres Sécurisés, a national agency linked to
the French Ministry of Transport and issuing secured official personal
documents) as well as by the Ministry of Foreign Affairs and Trade in
the Republic of Ireland where trials are underway for photobooth secure
online passport applications. Furthermore, it is currently in ongoing
discussions with Her Majesty's Passport Office in order to equip its
photobooths in the United Kingdom with the technology used in France.
It's a strong statement, but who can predict what government decisions might be made?
I previously spoke very positively on this company, and won't make a U-turn. I do think investors should try to quantify the risk associated with this. The UK accounted for 19% of total operating profit last year, and since then PHMT bought the UK photo division of Asda. So the UK photo segment is important to the investment case. And perhaps there is a risk that other countries might eventually follow suit with the UK Home Office, despite heightened terrorism risks.
On balance, I'd bet that governments will generally tend to err on the side of caution (better to be accused of being too strict, than too laissez-faire).
This is a difficult puzzle, and enlightened reader comments are more than welcome. I'd still have a favourable overall impression of this business, but maybe the shares should be trading cheaper now, than they are currently, to give investors a bit more upside for taking on the risk of the worst-case scenario?
Braemar Shipping Services (LON:BMS)
Share price: 249p (-15%)
No. shares: 30m
Market cap: £75m
This company has three divisions: the largest one, Shipbroking, is in line with expectations, but the other two have seen performance deteriorate.
Checking back to the company's interim results, it's obvious that we were already on track for a much weaker 2016/2017.
Demand for the company's Technical services has been greatly diminished by conditions in the offshore oil and gas industries. In H1, Technical swung from a £3 million profit to a £2 million loss, resulting in reduced headcount and restructuring costs. Further significant restructuring costs have been incurred in H2
Helpfully, the company guides us for "underlying operating profit before
interest, acquisition related costs and tax" within a £3.0 million -
£3.5 million range. And it intends to pay a 5p final dividend (down from 17p last year). The dividend had been flat for six years.
The chart shows a falling knife but with the company showing net cash (£1.7 million) and with the Shipbroking division apparently doing fine (responsible for 40% of revenues), I'd be inclined to think that this is worthy of further research.
MySale (LON:MYSL)
Share price: 125pNo. shares: 151m
Market cap: £189m
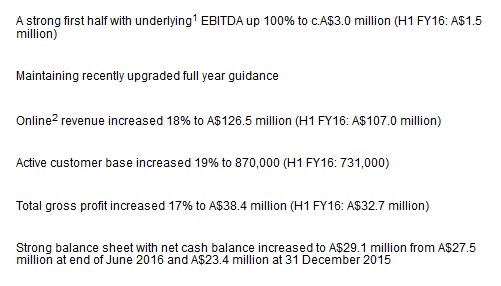
This was a very nice update ahead of the company's interim results.
What's special about this company's original and primary business model is the negative working capital requirement: customers order goods which are in-season for the customer's part of the world (and off-season in their country of origin), using MySale websites as the middleman. MySale doesn't have to hold stock, and gets paid up-front, so there are no working capital needs.
This has changed a little bit via the introduction of higher-margin own-buy inventory. I can't see any reference to own-buy inventory in this statement, but there has been a welcome improvement in gross margin all the same (270 bps).
The cash balance (A$29.1m) is worth c. £18 million, nearly 10% of the market cap. Crucially, the company appears to be more than adequately funded for future growth.
This one is a little bit too difficult for me, in terms of figuring out where it will wind up long-term. But if I wanted a relatively simple way to time my entry/exit into this share, I'd probably value it as a multiple of gross profits. Gross margin is the most important performance indicator for me, and revenues define the overall size of the business, so the product of those two numbers, versus the market cap, is the indicator which I'd be looking at.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
I see MySale (LON:MYSL) are now down 8% according to Stockopedia. Can't see any reason for the fall.
Thanks so much for covering MySale (LON:MYSL), much appreciated. Can't wait to hear about Paul's meeting with the management.
You're welcome Paraic, thanks for being a regular reader & commenter
Roger. Sorry didn't read your blog but its nowt to do with management betair and paddy power have the best in the game bar none and are head and shoulders above the rest bar 365. As I said single events kind of look after themselves generally as the books balance but that doesn't mean the books will win as the amount of money wagered isn't equal. A bit like a horse handicap. All the horses are meant to finish in a straight line ain't they? A book of 8 horses will often have two losers and 6 winners. That's before mentioning best odds guarantees, price promises, enhanced place terms when that book could easily turn into 8 losers!!. You've also got to remember the odd compilers are humans which is what us punters prey on. if they get it wrong then it won't matter how much the shorten or lengthen the odds they can't win. Take the kinloch/coral case currently happening. All of this squeezes their tiny margins and some books will run at a loss it's just how it is. Bookmaking in this day in age is simply a turnover game. Punters have never had it so good.
You only need man city, Arsenal, Man U, Chelsea, Rangers, Celtic all to win on the same weekend and no bookie could cover his liability. They're happy to lay these bets because they know long term that won't always happen but imagine it happens 4 weeks on the trot. It's not an excuse it's simply bad luck and is IMHO a completely viable excuse when we're talking about a business that relies on good and bad luck!!
The exchange you are talking about is exactly right. They make 5% on every book but that makes up a small percent of the betfair paddy power business and is completely different to normal bookmaking but remember the exchanges now dictate the markets on course. In the olden days bookies could send money to the track to shorten up a horse if they needed it to. That simply can't happen now so add that in to the fray and you should be able to see why bookies don't always make money.
ds1980: As I pointed out in my blog post, for individual large risks bookies can "lay off" the risk (I.e. reinsure it with others), or they should not be taking them on. The really amusing thing in the case of Paddy Power Betfair is of course that in Betfair there should be no risk at all - this is what their web site says: "Betfair is a betting exchange - an online marketplace for punters to bet against themselves on sporting and cultural events around the world . Customers bet against each other not against Betfair".
I suspect that with public bookmakers they are now adjusting the odds in reaction to what their competitors are offering so as to maintain volumes and profits, with the result that they are now losing big time on certain events.
It certainly raises a lot of questions about their management when they continually trot out the excuse of "unlucky/unforeseen" events.
PHTM. All very helpful to one, who was a long term shareholder; bought at 40p. Dividends and special dividends have been excellent. Successful laundry business to diversify. Now, "sitting on the fence", awaiting future news of Governmental action. Michael G
Surely the issue for PP was that they paid out on a Hillary win early. Ended up as very expensive "free" publicity.
Re Paddy Power , really hate these stories about bookmakers suffering from the punters winning. It should not matter who wins or loses if their "book" has been constructed based on the weight of money wagered. I wrote an article on this about William Hill claiming the same - see https://sharesoc.wordpress.com/2017/01/10/how-bookmakers-lose-money-william-hill/ . It's just nonsense in my view, unless they are betting against their clients, which they should not be doing. Comparing bookmakers to insurance companies is inappropriate.
I suppose the unspoken subtext is that those punters are likely to plough most of that money back in the near-future.
You've obviously not been a bookie rog. Margins are wafer thin. Yes books balance but that's only for individual races / events it's the accumulators that can't be balanced and this is the majority of where losses occur. Bookies can't lay off everything. If you make a book at 120% round but everyone backs the winner it don't matter what your percentage is! Take a look at the bookies who went to the wall when frankie got 7 up. With all the offers (money back second, money back if thistlecrack wins the King George etc then it's impossible to balance books sometimes. Long term of course the bookies will always win ( well not from me ;-)) but short term there will always be these stories you hate. Long may it continue.
With gambling companies like Paddy Power/Betfair there is always a risk from govts.Ironically although Trump has made his money in gambling his VP is a Born Again Christian and the Republican Religious Right are the clowns who in 2006 banned Americans from gambling online and as such the share prices of all gambling companies who allowed Americans to gamble were hammered .Betfair were rightly cautious before 2006 but that was with a different management and before they became an IPO .
At this moment there are people in the UK regulation industry worried about the way that gambling companies are maximising short profit by banning any regular winning smalltime punter.I`ve been a regular small time punter for 25 years and have had 6 online betting accounts closed in the last 2 years. in the previous 23 years none
3 that have closed my account are listed on the stockmarket:Bwin.Gvc (Sportingbet) ,Ladbrokes
There used to be a view by the bookmakers that allowing small time winning punters was a smart long term policy.
If the word can get around that one cannot win with a bookmaker why bet with them?
Regarding PHTM I have to agree with peterg. It looks like a business where there is an effectively free and far more convenient alternative. If I am right the value of the business falls to nearly zero bar any dividends they can pay out in the next 5 years.
True the government may require a certain standard of photo but if so both
a. PHTM will need significant upgrades to security and the fact these machines seem to be often in run down and scabby ends of stations would be somewhat worrying, would they need to replace almost their whole current stock of machines, would they need to install security cameras outside the machines? and
b. suddenly this area becomes much more attractive to potential competition; I do not believe PHTM has any particular patents on photo machines and if there were to be a government required type they cannot exactly patent it can they (At least not without government price restrictions which the current government will not want)?
All in all this would need to be a seriously cheap proposition for me to get interested; print newspaper level cheap.
Also biometrics will be implemented instead of passports by the sounds of it. Fingerprints. Retina scanners. Boat recognition etc. People will still need a passport I think though? No position
Re Photo-Me International (LON:PHTM), people are assuming that a photo booth is more secure than the system that the Home Office has rolled out, but I think not. On the contrary Photo Me will have to upgrade their systems to match the security offered by the new Home Office system if they are to remain accepted and even then the home taken photo will erode their market share as it is free for the technologically literate to use.
I have been following PHTM off and on on for years. The threat of obsolescence was,an ongoing concern particularly when the rapid shift to digital photos happened and again with the rapid take up of smartphones, However the company seemed to innovate fast enough to stay ahead and the financials were pretty good so I bought in a couple of years ago. Maybe this time they really are heading for obsolescence but the demand for security compliant imaging is not going to go away. Probably PHTM will be adding on biometrics and holographic imaging next. So I shall hold wait and see.
Graham, I think other countries have already gone down that route, I'm reading about Germany and Ireland.
http://www.dailymail.co.uk/travel/travel_news/article-2929980/Travellers-submit-SELFIES-use-new-international-passport-cards-trout-pouts-belfies-not-recommended.html
The US is not happy about number of fake passports and has warned 5 EU countries to clamp down on it, I can see this becoming more of an issue.
Concerning PHTM my inclination is to agree with Graham, as logic suggests that Governments will err on the side of caution and increased security regarding the integrity of important documents such as passports, given the proliferation of international terrorism.
Concerning PHTM my inclination is to agree with Graham, as logic suggests that Governments will err on the side of caution and increased security regarding the integrity of important documents such as passports, given the proliferation of international terrorism.
Though given that they have recently relaxed the rules I'd think that may be an optimistic view. Do PHTM have any business that is not heavily dependent on photo booths? What else does anyone use them for in the age of the selfie? The only time I've ever had anything to do with PHTM has been for passport photos and similar. It looks quite likely I'll never use them again.
If this really works itself through I can't see PHTM having much chance of surviving in current form at all.
Peter
Thanks for the comments on Braemar. Interesting "value stock" or "value trap" I think?
Long term the shares are back to their 1998 levels...
So the company hasn't benefited from the growth in global trade over the past couple of decades.
It's now from Friday but I'd love to hear thoughts on MySale (LON:MYSL) update - although I appreciate you may want to leave this one to Paul as he has followed it closely.
I'd be interested in your thoughts on Braemar profit warning
http://www.investegate.co.uk/braemar-shipping--bms-/rns/trading-update/201701230700077730U/
Structural or cyclical?
Top marks to them for including a profit estimate range ("£3.0 to £3.5 million") rather than the "results for the year ending 28 February 2017 will be materially lower than 2016" in the RNS last summer.
If you take the mid-point of their profit estimate, that would lead to full-year EPS of around 10p which is more than 50% down on last year. However, the shares have only fallen 38% since that first profit warning back in August (before which they were trading at 406p), including the 14%ish fall today.
In my view these have got further to fall before they recover, even if the company's problems are only cyclical. The RNS also trumpets cost savings and "management actions", and I would want some comfort that these won't have a long-term impact on their ability to profit from any recovery when it does come along.
On the bull side, the company's balance sheet is rock solid, and "resetting" the dividend now means it could start to creep up again as and when conditions improve. I get the impression management know what they're doing as well, so it is an investable company for me. I would just want to see some signs of recovery before I dipped my toe in the water.
I'm not so sure the Braemar balance sheet is rock solid. The biggest asset is £77m of goodwill, followed by £60.5m of receivables (compared to six monthly revenue of £70m so it is taking over five months to get paid on average).
There's not much debt, but the stockreport says it had negative free cashflow in 2014 and 2015. 2016 better but free cashflow not quite enough to cover the dividend. Also there's a (admittedly smallish) pension deficit. So burning cash and the balance sheet doesn't give it much staying power?
In shipbroking business, much of the revenue is fixed "forward", for example the brokers conclude a time charter but the revenues are a commission on charter hire paid monthly for the duration of the charter, which may be years. Very seldom are commissions paid up front. In the case of shipbuilding contracts or shipsale transactions, the commission is usually paid only upon successful delivery of the vessel, which again may be months or years ahead. As a result you have to adjust your evaluation of receivables in the case of a company which derives a significant proportion of its income from shipbroking.
B2V
thanks that's interesting and not something I knew.
Netdimensions (NETD) up c.20% today on no news. Paul commented on SCVR 23/12/16. Take over speculation!?!?
LPA also produced great-looking results today if you have time.....
Does anyone have an idea why PHTM is down 12% today? I see no announcements.... :-(
Guessing you have probably seen the thread by now but here you go...
http://www.stockopedia.com/content/photo-me-just-crashed-168124/
Yes, I have seen that, thanks. Will add something useful if I can.
Thanks Graham.
The link was in reply to Andrea in the first post but I'm definitely more than happy to hear your take on it all.
The company have released an RNS stating trading is inline and they feel "accepting photos from mobile phones for official documents is incompatible with developing security requirements."
The cynic in me say's 'they would say that' but the SP has record approx. 50%.
It's just a matter of deciding if this is new news that affects the investment case, or is it just a case of old news hitting a wider market and people panic selling!?
It feels to me like the market sentiment has shifted for now at least and people are taking profits at the first sign of an issue.
Thank you very much 'Weasel'; hadn't seen the thread