Small Cap Value Report (24 Feb 2017) - RMV, BJU, COA, PURP, TBCG

Good morning!
Paul is off today. I'm planning to cover Rightmove (LON:RMV) and anything else that pops up or is requested in the comments. Let me know what looks interesting to you.
Best regards
Graham
Rightmove (LON:RMV)
Share price: 4065p (-4.2%)
No. shares: 93.1m
Market cap: £3,785m
The market was more than a little disappointed with this announcement at first.
It's obviously a highly rated stock, which makes for volatility even when results are quite positive:
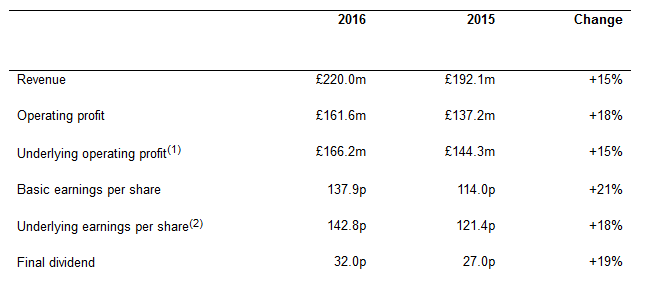
Annual percentage revenue growth over the past six years has been within an 11%-23% range, and the last three years have been 17%, 19% and 15%, so today's result is nothing special in that regard.
The operational highlights are fairly impressive, including the claim that Rightmove has a third more residential properties than any other portal. The CEO claims it is "the only place you can see almost the entire UK property market", and appears to have some justification in this claim, despite well-publicised moves by competitors in recent years.
I've tended to think that Rightmove deserved its premium rating in recent years, and that remains the case for me now.
It looks really shareholder-friendly too, with £131 million having been returned to them this year. I'd just have a slight concern about the mix of buybacks within that - I'll need to find out what the rationale wasfor including £88 million of buybacks. They must think the shares are good value at an average price of £40 each!
CEO retirement: This explains why the shares were so weak on the open. The co-founder CEO is retiring after 16 years. He'll be replaced by the COO, who is also highly experienced at Rightmove. See separate RNS.
Outlook: Nothing specific in the outlook statement, just that the BoD is "confident of continued success in 2017".
ARPA: This is a slightly unusual argument and I'm not sure how it works exactly. Rightmove says that the average revenue per advertiser per month for newspapers was £2,500 in 2007, while Rightmove's ARPA today is just £842 per month. While I'm sure that ARPA growth is possible, I don't see the relevance in terms of what newspapers were doing back then!
Commercial property: Rightmove claims to have 86% market share among the top 3 commercial property portals. A number as big as that is a natural monopoly and highly valuable in my book.
My opinion: I'm going to have to move on and look at some other companies instead of reading the entire statement right now, but I personally don't think that the company is overvalued here, and wouldn't be averse to having a small position in it.
The free cash generation is real, even if I'd prefer to see that cash being used slightly more toward dividends than buybacks. The trailing PE ratio is 29x, or perhaps less than 27x on a forward basis. Market leaders are expensive and in the current stock market environment, that doesn't look exorbitant to me!
Brainjuicer (LON:BJU)
Share price: 742.5p (unch.)
No. shares: 12.2m
Market cap: £90.7m
Just a quick note on Brainjuicer, the branding agency which I like to report on from time to time.
Unfortunately, it might not be called Brainjuicer for much longer, as there is a proposed name change to System1 Group.
I quite like its quirky name but I suppose good things just don't last!
System1 refers to the emotional, instinctive ways people are thought to make many decisions according to behavioural science, which Brainjuicer uses to help their clients succeed.
Separately, there is a new LTIP proposed which will reward gross profit growth at a rate of up to 30% p.a over four years. The minimum achievements required for vesting aren't mentioned in the RNS, so it's hard for me to judge at this point whether this is something I could vote for if I held shares.
The max award "will result in dilution of up to 8.5% of the company's issued share capital" - would that be fair compensation for gross profit growth of 30% p.a. for four years? I guess so, but it will be up to shareholders to decide.
Coats (LON:COA)
Share price: 55.5p (-4.7%)
No. shares: 1407.6m
Market cap: £780m
I'm afraid this isn't one I've looked at before, but thanks for the comments suggesting that I mention it.
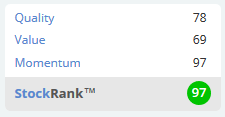
From a quantitative point of view, it has a mighty StockRank of 97, and passes 5 investments screens! (for its momentum, value and growth characteristics.)
Anyway, the results today are sturdy: revenue up 2% on a constant exchange rate basis, but adjusted operating profit increases 16% thanks to "market share gains, cost productivity, controlled overheads and raw material price benefits". Sounds good.
What's even better is the company's pride in its excellent return on capital employed, which improves to 39% from 33%.
Another highly relevant KPI which the company uses is free cash flow (it's own, non-statutory measure), which improves 10% to USD $78 million. That's worth about £62 million, or 8% of the current market cap (i.e. the trailing free cash flow yield is currently 8%).
It describes itself as "the world's leading industrial thread and consumer textile crafts business" - and has been around for over 250 years.
Debt and pensions: Coats is carrying an accounting pension deficit of $627 million, though at least it has net cash at the Group level of $78 million.
Checking footnote 14. (c), I see that the company added back its pension scheme payments of $99 million, as well as several other important costs, to get the adjusted free cash flow mentioned above - which sorts of takes the shine off the adjusted free cash flow measure.
Outlook
The outlook seems a bit nervous in relation to H1 comparatives, which might go a large way toward explaining the share price softness today:
We enter 2017 on a solid footing however remain cautious about market conditions. We expect to continue to deliver growth in line with management's expectations through our initiatives to deliver market share gains, productivity improvements and tight cost control. This growth is likely to be weighted to the second half of the year due to strong profit growth in H1 2016, and may also be subject to further foreign exchange headwinds on translation that have been seen in recent periods.
My opinion
Coats claims that one in five garments made in the world today are sewn using their threads - and that's only the apparel division.
So it sounds like a fantastic business. The market cap is worth about USD $1 billion and if we naively add the pension deficit to that we get an enterprise value of $1.6 billion for a business which just produced (after-tax) profit from continuing operations of $76 million.
I could get behind investing at that sort of multiple for a business with this sort of competitive position.
You do need to have some view on pensions, though. There were actuarial losses this year of $325 million. If you hold this for the long-term, you'll be sharing the company's real free cash flow with the pension fund, and interest rates and investment returns will have an enormous impact.
While not claiming to know the future path of interest rates and investment returns, I'd tend to give the company the benefit of the doubt and have a positive view on the shares, based on what I know so far.
Purplebricks (LON:PURP)
Share price: 260p (-1%)
No. shares: 270.5m (including 22.7m placing shares)
Market cap: £703m
By multiple reader request, let's see what I can make out of this Purplebricks situation.
It's relevant to my Rightmove coverage, as Paul wrote in December:
Also, if PURP became really dominant in online estate agency, then why would it need Rightmove? It could cut out Rightmove altogether (or offer it as an optional extra), and create its own property portal.
And yesterday, Paul wrote:
I think estate agency is clearly a sector ripe for internet disruption. I did some googling the other day, and found about a dozen or so online estate agencies. Then I checked all of them on Alexa.com . Sure enough, Purplebricks is the clear market leader, by miles - it was claiming about 62% of the market, but in last night's RNS that has gone up to 67% (based on listings on Rightmove).
I think this illustrates why it's much too soon for Purplebricks bulls to announce the impending death of Rightmove - the overall property market is still measured in reference to Rightmove!
(In a similar way, stale gold bulls like myself have had the occasional temptation to announce the death of the dollar - by referring to the price of gold measured in dollars.)
Conquering the Web
Since we still compare agents according to their Rightmove listings, Rightmove remains the barometer. And while purplebricks.com is undoubtedly a valuable domain, with a UK Alexa rank of c. #2,500, it is simply nowhere near the rightmove.co.uk rank of #37!
Such a high ranking means that we can consider rightmove.co.uk to be an essential part of the internet experience for vast swathes of the UK public, and that doesn't simply vanish overnight.
Yahoo! has been considered uncool and out-of-date for many years, and yet it still has a global Alexa rank of #5!
So while Purplebricks might be making great headway in the estate agency business, achieving the online feats of Rightmove is a different task.
The way I could see it playing out is in some kind of consolidation or collaboration between Rightmove (or Zoopla) and Purplebricks (or another new-wave estate agent). But that would only happen if the thesis turns out to be true that one of these new-wave estate agents is going to achieve an unassailable competitive position.
Conquering the US
This is the key paragraph in the rationale for me, since it explains why Purplebricks might be able to disrupt a new territory:
The Directors believe that real estate agents in the US will want to become LPEs, given the compelling customer proposition and the benefits of the Purplebricks model. The Purplebricks model should allow agents to spend more time focusing on looking after customers and selling homes, rather than a significant proportion of their time being taken up prospecting for the next listing. This is possible because a sustained marketing and advertising campaign is intended to drive listing appointments to the LPEs (see below). The Purplebricks platform and business model is designed to result in improved LPE productivity which provides LPEs the opportunity to earn more revenue than they would as a traditional real estate agent.
So the idea is that centralised marketing campaigns in the chosen states will enable US real estate agents to spent more time with customers and prospects and less time marketing - makes sense.
It's hard for me to imagine that £50 million would be enough to bring the businesses to a self-sustaining level of activity, but I guess the devil will be in the detail in terms of which states they are targeting and how much advertising will cost there.
My opinion: It's not really my style to buy into something like this, I'm a bit too boring and tend to go for companies which are at a more mature stage of development, so I miss out on these types of opportunities. But I can see there is a rationale for continuing to hold Purplebricks for the long-term possibilities - I'd try not to watch the share price too closely though, to avoid getting too stressed or excited!
TBC Bank (LON:TBCG)
Share price: 1424.5p (unch.)
No. shares: 52.5m
Market cap: £748m
I'm taking liberties now by covering a mid-cap financial based abroad, but there was a reader request from Ric so hopefully I'm justified! And it had final results out today.
This is the largest bank in Georgia, market share c. 37-39% after a recent acquisition, depending on how you measure it.
Some financial highlights, key metrics in bold:
- Net Profit for 2016 up by 36.4% YoY to GEL 298.3 million
- Return on equity (ROE) amounted to 22.4% (20.6% without one-off effects) and Return on assets (ROA) to 3.9% (3.6% without one-off effects)
- Cost to income ratio stood at 45.8% (42.9% without one-off effects), compared to 43.9% in 2015
- Net interest margin (NIM) stood at 7.8% in 2016, unchanged from 2015
For a quick comparison with a British bank: Barclays had a Return on Tangible Equity of 9.4% in 2016, a cost to income ratio of 61%, and a net interest margin of 3.6%.
So by all of these primary financial metrics, the lowly TBC had a much better year than Barclays.
It may have done this in a somewhat riskier way than Barclays, however, holding tier 1 capital (equity plus reserves) of 10.4%, compared to Barclays which reached 12.6% by Dec 2016 (it started the year at 11.4%).
Acquisition
TBC bought rival Bank Republic in Q4 2016, which had a market share of about 7% in Georgia. This is now consolidated within TBC.
My opinion
Thisis a new listing since August 2016, and has been a success for investors so far. The market cap in Georgian currency is worth GEL 2.4 billion, whereas the balance sheet equity is just shy of GEL 1.6 billion.
I haven't got any insights into the outlook for the Georgian economy but in principle I don't see anything wrong with paying 1.5x book value for a bank with metrics such as TBC has achieved.
I'm going to have to go now, thanks for the suggestions and apologies for not getting around to all of them.
Have a great weekend!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Purplebricks (LON:PURP) have as good as confirmed in the placing RNS that the £50m raised will not be sufficient, so there will be further placings to come.
"The Company's strategic growth plans through expansion into the US property market is also expected to involve significant operating cash outflows and capital investment, which is likely to exceed the net proceeds of the Placing received by the Company."
Hi Graham,
Many thanks for covering today's report. Very interesting it is too.
As regards Purplebricks (LON:PURP) - it's very early stage, so any thoughts of it displacing Rightmove (LON:RMV) are clearly extremely long-term. I don't think anyone is suggesting that's an imminent issue, because it clearly isn't. Rightmove is very dominant in property listings right now. But will that last? I'm not so sure. When you look at Rightmove's massive profit margins, they are so high that it's bound to attract the attention of major internet corporations, sooner or later.
So I think the big risk RMV shareholders face, is if they wake up one day to find that Google or Amazon, is launching a property listings site for free, along with some neat new features, and lots of publicity. That could kill Rightmove, Zoopla and the other one, inside a year, I would guess.
I believe Google did look into doing this a few years ago, but decided not to proceed with it - I think they mooted the idea of integrating property listings into Google Maps.
So in this age of rapidly moving technology, I'd be wary that RMV has now become the incumbent which may suddenly face a big competitive threat from someone with deep enough pockets to steal their business. The growth is unspectacular now too, and the rating is high, so all in all risk:reward doesn't look great to me with RMV. Things just don't stand still, and therein lies the risk.
PURP is very much a punt, and I agree they will probably need to raise more cash to do a big roll-out in the USA. The current £50m is only for starters, in a few states. But they have already proven up the business model in the UK, reaching EBITDA breakeven, and of course if you exclude marketing costs, it's already nicely profitable.
So a fascinating sector! If PURP can keep its market cap enormous, then raising the odd £50-100m say, for further expansion, won't dilute existing holders much, so it's rather exciting I think. Probably a binary outcome though.
Regards, Paul.
Many thanks Paul and Graham.
Another stock that operates in the house transaction space that you may like to take a look at when there is news on them is Mortgage Advice Bureau Holdings (MAB1). (Sorry -couldn't get the thing that turns this into a hyperlink to the stock to work).
Disclosure - I hold a long position in this stock.
This is the largest intermediary in the UK market supplying the back office function for mortgage brokers. Their advisers may trade under their own name or the Mortgage Advice Bureau name.
A reason that they are interesting is that they have gone down the technology route to take a lot of the admin burden of transactions off the face to face adviser and are also into the on-line and telephone services as well. They are growing quickly as more and more advisers switch to using them and are highly profitable. They pay a nice dividend already, albeit lightly covered but I don't think that is much of a problem as they have little capex need. As more advisers join the revenue from them converts very nicely into profits and cash flow.
What the diligent may also notice is that Purplebricks are partnered with them, so if Purplebricks does well then this company will benefit. Purplebricks has recently gone into Australia and MAB have set up a joint venture down there to go in with them. So, you might say that MAB is piggybacking onto Purplebricks' marketing spend.
On the robo-advice side the disrupter Tussle is also partnered with MAB.
I would agree with Graham Ford about Mortgage Advice Bureau as their financial fundamentals look very attractive. They also have cosy relationships with a number of major estate agents and at least one estate agent (Chancellors) has a major stake in Mortgage Advice Bureau. When buying a property through Chancellors I was therefore unsurprised when Chancellors suggested to me that I should use the broker for a mortgage as it would make things easier and quicker, even though I did not need a broker for a mortgage. Not sure about the ethics or regulatory implications of this, but I am sure it must make the broker quite a bit of money in commission.
Coats (LON:COA)
I notice that coats quote their ROCE as being over 30% while stockopedia quotes it as just over 10%.
Are coats using some sort of adjusted measure or is stocko wrong?
Yes Doug, Coats must be using a different way of calculating ROCE to that used by Stockopedia. I am yet to find a company which calculates ROCE in a conservative manner, they always seem to arrive at a better ROCE than Stockopedia. Even a well regarded company such as Halma, which sets great store by ROCE, reckons it has a significantly better ROCE than indicated by Stockopedia. I think it must be a bit like adjusting profits to make them look better.
Hi Graham or anybody who can help
Does any one know the best website to go on to find out directors total holding I currently use
http://www.directorsholdings.com/company/RB./Reckitt+Benckiser+Group+PLC
but I believe they are closing down
Hi Tony,
Not sure if this does it for you, but plenty of information on the Morning Star website - question is finding it sometimes! Maybe start from this link and explore:-
http://tools.morningstar.co.uk/uk/stockreport/default.aspx?tab=5&vw=dd&SecurityToken=0P000090MG%5D3%5D0%5DE0WWE%24%24ALL&Id=0P000090MG&ClientFund=0&CurrencyId=GBP&TransactionSize=0
Let us know how you get on.
Best,
Gus.
Hi Gus ,
Many thanks for the link it was very helpful.
All the best
Tony
Thanks for covering Coats - a further look through the reports and previous RNS' will show that the company are in advanced stages of settling their three pension legacy issues. This will leave a well capitalised company, hence why they have reinstated the dividend, I expect this catalyst to rerate the shares in due course. The company have been around since 1735 and were one of the original Footsie 30 members in 1935. I own shares in COA.LN
Not a problem !!
My one comment on Rightsmove; it does a lot of business on lettings. When charges to tenants by letting agents are finally banned in England what then? Who pays for all the current costs e.g on portals and local press etc? I am a landlord and I certainly don't intend to pay more. I think this entire area is bloated and a lot of the easy profit made over the last few years by agents charging both the tenant and the landlord is coming to an end and costs will need to be cut drastically. Whether R can resist this inevitable pressure is a moot point.
Hi Graham,
Thanks for your recent contributions it's great to see you part of the team. I just have a question that most likely covers both Paul and your comments. When you say small position or medium/large what do you mean in term of ranges. Due to the nature of the small cap market it would be very different versus FTSE stocks. Does this mean in the range of £2-5k for small, £10-15 for mid? It is not a specific to right move nor will I be making any trades on the above but was more for clarity and understand scale for when you and Paul comment.
Many thanks
Hi Phil, great question. When I say small I mean as a percentage of my portfolio - my individual positions can range from anywhere between 2% to 25% of my portfolio, so for me a small position would be about 2%-4%. You're right to ask me to specify, because other people would have a different perspective on this.
Thanks Graham much appreciated and great review on PURP. I'm a similar boring investor, companies like PURP can give you a heart attack whether it rockets or sinks. Have a great weekend.
Hi Phil,
For me, my 2 biggest positions are 17% & 13% of my total portfolio - these are things that I am super-confident (hopefully, but not necessarily right!) about.
Then I have about 13 positions which are between 2-6% of my total portfolio each - these are things I like a lot, and have researched thoroughly, and usually held for a while.
After that, I have entry level positions (sub-2%), which are companies where I'm not necessarily particularly confident, or don't feel I understand the company well enough yet, or just want to see what happens before making a decision on whether to increase, or dump them, depending on the next set of results.
Everyone does things their own way, so it's important to just work out what works best for yourself.
I'm generally quite long-term with my main holdings, but it depends on the newsflow.
Regards, Paul.
P.S. of my top 20 positions, only 2 are loss-making (PURP - which is loss-making by choice, and could easily switch off the marketing spend which makes it loss-making, and WAND - which is a bit of a punt based on recent improved newsflow).
Generally I find it's best to invest in profitable companies.
Hi Graham re. Rightmove (LON:RMV) the one thing that has always struck me in awe is this company's operating margin (and I mean operating margin and not gross margin). Today's results show 75% and I believe this ratio has been above 70% over the past few years.
This underlines the monopolistic power that you mentioned. They are just dominating this sector.
Unfortunately I have never overcome the feeling that it's paper is expensive and have stayed on the sidelines. Maybe I need a mental reset.
Regards. Ram
Thanks for the suggestions!
Investegate is the source I use and link to in all the reports here so I recommend that everybody goes there for the primary material.
I'll make a few comments on Purplebricks (LON:PURP) later but it is a stock I've commented on before. I didn't claim to know what it was worth then, sorry! Here's my thoughts in December:
http://www.stockopedia.com/content/small-cap-value-report-5-dec-2016-pla-purp-rxb-161039/
Thanks
Graham
Hi Graham
Thanks very much for your contributions. I particularly enjoy your commentary on financial sector stocks as that is an area where I will occasionally dabble.
I was wondering if you could take a quick look at TBC Bank (LON:TBCG) which is relatively newly listed Georgian bank (with a full listing). It has put what appears to me to be a good set of 2016 results this morning. Growth in nearly all key areas. Banks are tricky to analyse so just wondering if there are any red flags I am missing.
At nearly £800m market cap it might be beyond the scope of this report.
Many thanks
Ric
Hi Ric, TBCG is covered now.
Cheers
Graham
Thanks Graham - much appreciated. Great to get your views. Have a good w/end
Hi Graham,
if anyone wants to check out my original research note on Bank of Georgia, it has got quite a lot of background on the Georgian banking sector and economy. Out of date, but people can see the story - concentrated banking market, with good growth prospects applies equally to TBC. Think Irish banks in the 1980s.
http://brucepackard.com/wp-content/uploads/2014/10/Bank_of_Georgia-Oct-2011.pdf
Disclosure - Seymour Pierce did the GDR conversion to main market listing. And then I bought a large chunk when Lansdown Partners and Tosca said they weren't interested in buying a well capitalised 20% RoE bank, which was on 5x earnings at the time.
Thanks Bruce
Second vote for your views on PURP please Graham
Hi Graham, I've been looking at Digital Barriers (LON:DGB) which looks like a falling knife but at some point may be a buy. Are they just a story stock giving the directors lots of jam today at the expense of shareholders? Accounts seem a bit smoke and mirrors to my untrained eye and I sense a fund raising (again) but they seem to have lots of IP, are selling lots but losing money. Not urgent but if you have time sometime.
Thanks very much for the request but I can only afford to focus on stocks with recent news. Cheers!
Graham
Yes, just to reinforce Graham's post above - these reports are driven by each day's specific RNS announcements - trading updates & results statements.
So we're not "tipping" shares - we're just giving an opinion on each day's trading updates & results statements.
So share price movements, when there hasn't been any newsflow, are outside the scope of these reports. Also we generally don't comment on day-to-day announcements about contract wins, etc, unless they are highly significant.
We don't comment on nano caps either - our usual cut-off is £10m mkt cap - because they're so illiquid, that readers probably couldn't trade them anyway, so there's no point in commenting on them.
I try to keep the focus on small to lower mid caps, so £10-400m mkt caps mostly, although occasionally we stray into larger caps. But my view is that readers can get news & views on larger caps from many other sources. Whereas few people cover small caps in a meaningful way, which is our specialism here. And we're pretty good at it - well, getting better as we go along, anyway.
Regards, Paul.
Hi Graham,
I know Paul covered it yesterday, but as you're covering Rightmove (LON:RMV) today I wonder what your views are on Purplebricks (LON:PURP) ?
I'm a happy holder but it strikes me it could be a binary outcome - it could be a great success or it could crash and burn so not one to take too much exposure to given the current valuation. What do you think?
Hi Graham
I would be interested to know what has caused Shoe Zone (SHOE) to take a sudden drop. Nothing in the news I can see
Ron
Shoe Zone (LON:SHOE) it went ex div for 14.8p yesterday, lots of small investors dip in for the divi and sell out after so price is just back where it was..no dramas!
Thanks rhomboid1, I'd forgotten about the divi and you saved me from panic
Graham, good morning.
RPC Group
I'd be interested in your views on the recent purchase of the multi-plant US plastic packaging company, Letica, by the UK company RPC Group. The purchase has necessitated a further Rights Issue, the share price has since fallen by 10%.
I hold these shares.
Michael
Hi Graham,
What is the best way to access the RNS directly? I'd love to be able to read them myself BEFORE reading your /Paul's daily analysis, to see if I can spot some of the things you guys do.
try http://www.investegate.co.uk/
RNSalert.com is excellent, emails and tweets you at the time of any RNS from any companies you select, and gives you a link to the actual RNS on the London Stock Exchange site.
I use VOX markets app. Like RNSalert, it will provide notifications in real time when they come in in the morning (or indeed for those cheeky BODs that try to slip them out late in the day!) It's esp useful if I'm not at my comp and have forgotten / am surprised by an announcement from a holding of mine.
Otherwise, when on PC, investegate shows you the morning's line up very clearly.
HTH
Hi Graham
Could you look at Tarsus (TRS) .
Thanks
Thanks for the suggestion Tony but I need to prioritise shares with recent news flow. Apologies!
Morning Graham
http://www.investegate.co.uk/coats-group-plc--coa-/rns/2016-full-year-results/201702240700087389X/
Coats (LON:COA) , would be nice !
Thx
Re COA - second that please Graham