Small Cap Value Report (24 Mar 2016) - BRY, TRCS, ABDP, IEH, AFN, NAR, CHH, FJET, LAKE

Good morning!
Brady (LON:BRY)
I'm busy preparing for another interview with Gavin Lavelle, CEO of Brady (LON:BRY). He asked for an opportunity to respond to the points I raised in my report here on 21 Mar 2016, which was critical in parts.
If fundamentally sound companies want to engage, then great, I'm happy to do so. Indeed I enjoy helping sound companies and private investors communicate with each other, whether or not I hold the shares personally. I won't waste your time with dodgy resource stocks, or blue sky nonsense. Let's see if Gavin can be persuasive enough to tempt me (or you) back into Brady shares!
EDIT - all done - here's my new interview this morning with Brady's CEO (audio, 26 minutes)
IT improvements
Good news re the annoying HK tickers that sometimes pop up in these reports - Ed has tweaked the coding so that the £ symbol before a ticker will now only pull up UK companies. Hoorah!
Also, I was given some re-training yesterday on a better way to insert pictures into my reports. So hopefully we should not get a repeat of past technical problems where sections of the reports disappear. It's fair to say that my relationship with computers is, at best, an uneasy truce!
Timing
At 12pm I have a (non-recorded) call with another company CEO to learn about his recently floated company. So if it sounds any good, I'll let you know. Therefore, timing-wise, most of this report will get written this afternoon, and possibly this evening.
Incidentally, I added loads more sections to yesterday's report last night. So please do have a recap on that report here whilst you're waiting for today's report to gestate. It's so busy at the moment! I can't cover everything, but do my best to report on the most interesting announcements.
Tracsis (LON:TRCS)
I should also mention that the CFO of Tracsis emailed me yesterday to point out that the deferred consideration creditors on their balance sheet should be self-funding. So the deals have been structured as earn-outs. This means that challenging profit & cashflow targets have to be hit, in order to trigger the payments. To be prudent, the company has booked the maximum possible earn out onto its balance sheet.
This is a really important point, as it means that the company's cash pile should not be eaten into by those liabilities, as I incorrectly stated in my first draft of yesterday's report. Am happy to clarify this point, and yesterday's report has been amended to include the CFO's email. It's great when companies engage like this, to clarify or correct misunderstandings.
I suggested that they include a bullet point in the highlights section of future reports to flag up the self-funding nature of the earn-outs, which they took on board.
Ab Dynamics (LON:ABDP)
Share price: 382.5p (up 4.5% today)
No. shares: 17.3m
Market cap: £66.2m
(at the time of writing, I hold a long position in this share)
Trading update - there's an upbeat report from this company today;
Revenues and operating profits for the six months to 29 February 2016 are expected to be significantly ahead of the same period last year. Sales in USA, Europe and China performed exceptionally well. In addition, as the industry increases investment in new models with a focus on advanced safety systems, sales of both our track and lab testing products has remained strong throughout the period. It is expected that revenues for the full year will be considerably ahead whilst operating profit will meet or marginally exceed market expectations.
All good, but the upshot is in line, or "marginally ahead" of market expectations, so it's not something to get wildly excited about. Positive yes, but only modestly so. Therefore I think the market has got it right, with a 4.5% increase in share price.
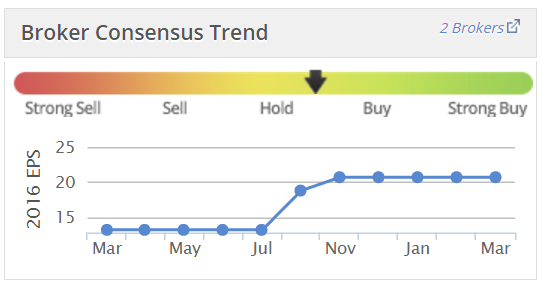
The company looks on track (geddit?!) to do about 21-22p EPS this year. That's a PER of nearly 18, so the price is looking quite full now. I've taken this opportunity to sell half my personal position this morning, to lock in some nice gains, and am happy to run the balance for the foreseeable future.
Nice company this one, and it seems on a roll. Broker forecasts have already been raised quite a lot earlier this year;
Intelligent Energy Holdings (LON:IEH)
Share price: 9.2p (down 80% today)
No. shares: 188.3m
Market cap: £17.3m
Update on funding position - I've not looked at this heavily cash-burning company before, and judging from today's announcement doesn't look like I'll need to. This is probably about to go into Administration I'd say;
The Company refers to its announcement on 26 February 2016 which included an update on the Company's proposed funding process.
The Company announces that, in light of recent and unexpected developments in the discussions with various parties, the Company will not be able to complete a funding process, in sufficient quanta, by the end of Q1 2016. Further, at this stage, there can be no certainty that an appropriate funding plan can be implemented at all.
The Company is reviewing all options and further announcements will be made in due course.
That sounds terminal, and imminently. Expect the shares to be suspended later today, or next week perhaps.
Over-ambitious, heavily cash-burning business models are very rapidly going out of fashion right now. Not before time either.
ADVFN (LON:AFN)
Share price: 27p
No. shares: 25.4m
Market cap: £6.9m
Interim results - 6m to 31 Dec 2015 - as this RNS was slipped out at 5:45pm the night before a Bank Holiday, I'm going make a special effort to shine a light on it.
The figures are poor. Turnover is down 11.1% to £4.3m for the 6 months. The operating loss was £538k, slightly less bad than £647k in the prior year H1.
Balance sheet - looks stretched;
NTAV is negative at -£604k
Current ratio is weak, at 0.69
Cash is only £784k (down from £1,510k a year earlier)
Outlook - costs have been cut, and the current trading comments sound a bit more positive;
More cost cutting benefits have been felt in the new calendar year as contract and headcount reduction periods have passed with January and February showing good levels of operational performance. This has been helped by a pickup in advertising sales.
At an operational level we have seen improvement in the first few months of the calendar year of 2016. Our aim is to capitalise on last year's hard work to build upon the good start seen during January and February and continue to improve performance on a running basis in the final half of this financial year.
My opinion - this is clearly a lifestyle business for the Directors. It doesn't pay divis, and has never managed to extract any value from its large database of investors, nor gain traction from overseas expansion.
Talking of that user database, it's probably not worth very much, because it clearly contains many fake, multiple accounts set up by rampers to abuse its bulletin boards. Also the drivel posted by many of its genuine members suggests that they're (a) not very bright, and (b) haven't got much money.
It would certainly need new management to stand any hope of creating any shareholder value, in my opinion. What's the point in it being listed?
Time is short now, so I'll go into snippets mode;
Northamber (LON:NAR) - another company where the burning questions are what's the point in it being listed, and why does it actually still exist at all? Its interim results today show a worsening trading picture - an H1 loss of £547k (prior year H1: £292k).
The only saving grace is a solid balance sheet, with NTAV of £19.9m (versus a market cap of £8.9m at 32.5p per share currently). However, you might ask, so what? What is the value of assets which are just being tied up in a completely unproductive activity?
So it's another lifestyle business I'm afraid. The only value for shareholders would be if they decide to do something radically different with the company. In the meantime it's just dead money tied up. There's been a small dividend in the past, reduced to only 0.6p per share in each of the last 3 years.
Management need to bite the bullet, and come up with a new strategy for the company, as currently they're just treading water, and shareholder value is slowly leaking away with losses each year.
The Chairman holds 61%, so there's no chance of any activists being able to get involved here. The company is his plaything, and I don't think he has any idea what to do with it. My suggestion would be to wind down the existing, loss-making activities, and instead use the company's facilities & expertise to reverse in an e-commerce business of some kind.
Churchill China (LON:CHH) - good figures from this UK manufacturer of crockery, mainly for the hospitality sector. I often see their products when eating out. Basic EPS rose 20% to 37.3p, which is a little ahead of expectations (of 36.6p).
The company also has a super balance sheet, with plenty of cash - this rose to £11.8m, with no debt. That's material to a market cap of about £84m (at 767p per share currently). It owns the freehold to its main site too.
The shares look fully priced to me, on a PER of about 19.
It says that "the current year has started well".
Fastjet (LON:FJET) - I see that the CEO, Ed Winter, stepped down on 18 Mar 2016. Good job too, as he's been a complete disaster. Another Director stepped down at the same time. The Chairman has taken over until a CEO can be found.
Therefore EasyGroup Holdings requisition for an EGM to oust the CEO has lapsed, as its objective has been achieved.
The latest twist in the saga, is that EasyGroup (which owns the Fastjet brand), and is a 12.6% shareholder in Fastjet, has published a letter (publicly) accusing Fastjet of being in breach of the brand agreement. So it sounds to me as if EasyGroup has given up on Fastjet, probably doesn't want to put in any more funding, and maybe wants to kill it off (why else would they take such a provocative public stance towards it?)
Fastjet has put out several responses, saying it is considering the matter with its advisers.
In my view, if one of your major shareholders appears to be actively trying to destroy the business, then private investors should probably dash for the exit and salvage what's left of your failed investment. This is not a viable business, although it could perhaps stay in business for a little while longer by doing a sale & leaseback on the aircraft it owns.
It seems to me virtually certain that this company will go bust within a year, so the shares are probably worth nothing.
Lakehouse (LON:LAKE) (at the time of writing, I hold a long position in this share) - another company where board room battles are underway, with the founder (Steve Rawlings) having joined forces with Slater Investments to requisition an EGM to replace the Non-Execs (strangely). Lakehouse has published its response today, here.
My view is that this is a mess, and that it's a great pity all this dirty laundry is being aired in public. However, as an investor, I'm far more interested in how the company is trading, and the most important line in today's RNS is confirmation that trading is alright;
"The Board confirms that the Company remains on track to deliver its revised expectations for the current financial year."
The forecast is for adj. EPS of nearly 10p this year, so the PER is staggeringly low, at only 4.5. I think this could turn out to be a terrific bargain at the current level, indeed I tried to buy more today, but didn't get a fill unfortunately, as I tried to be too clever on price.
The board room issues will get resolved, one way or another, and for me are presenting an opportunity to pick up a fundamentally sound company at a price which looks dirt cheap.
I'm not sure it was wise of LAKE to put out this document today, which rubbishes the skills & experience of the founder, and the other 2 suggested new NEDs. However, I don't think the requisitionists have behaved sensibly either. They should have thrashed out any disagreements in private, not embarked on this daft public spat.
Anyway, let's see how it plays out, but for me, the shares are a bargain & I'll be buying more next week.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Thank you Paul for your rationale on Next. I can see that there might be a nice bounce in the share price, and it's a safe bet if it's a share you are happy to hold anyway. I'm not really a trader, so I'm looking longer term,and I can see that it might be worth starting a holding at this price. Will probably open higher though, and I do still have a concern about whether they are maintaining their product quality - so patience will be my watchword.
Re Next (LON:NXT) I don't agree with their outlook I don't think the high is anything like as grim as 2008 at the moment, yes it could get that way but I think that is some way off still, even if China goes belly up it will take a while to affect the UK consumer, anyway thats my opinion. Did they not issue a similar outlook last year? Yes Bretix may cause some cause problems. I wonder with the switch to online shopping if Boohoo.Com (LON:BOO) will be a takeover target?
OK had a quick look at last years report and they were a bit downbeat, said forecast pretax profits would be between +0.4% to 6.7% Well they have come in at +5% so towards the higher end of the forecast. Anyone would have thought the profits were down 10% from the reaction.
Finally had the chance to read through the extensive Next (LON:NXT) earnings release. It is a very clear and thorough document. What I particularly liked was the way in which they provide a metric, say change in operating margin, and then drill down into it anticipating the sort of issues an analyst might raise and addressing them. The historic figures are generally excellent and even where they aren't at face value (e.g. Fall in Directory margin from 24.5% to 24.4%) the reasons are consistent with the strategy and if anything underline how it is working (e.g. Expanding international sales and size of the high margin credit book).
What seems to have spooked the market is the section at the end on expectations for next year and their view that (a) the economy may slow; and (b) the proportion of consumer expenditure allocated to clothes etc., compared to eating out, travel etc., may reduce. While neither would be a good thing, the impact would hardly be confined to Next (LON:NXT) alone and is only an opinion of what might happen and what a prudent company should prepare itself for. It does seem that absent a more meaningful problem (I recognise the TAs see a number of technical challenges in the Next (LON:NXT) chart patterns etc), a 15% fall that hasn't immediately spooked the rest of UK fashion retail (I note the likes of Marks and Spencer (LON:MKS) were down a little bit but others such as Boohoo.Com (LON:BOO) where up in a generally bad day for the market) seems to be an over reaction.
Interesting to see what happens after investors have had a long four day weekend to reflect on things.
Gus.
Re: NEXT, I know it's a big % fall, but is it really cheap at the current price? It might be just one disappointment, and it might have been unseasonably warm, but they have had a very long and steady run in what is often a volatile industry. M&S never got their mojo back. Wolfson seems to be talking about clothing having times when less is spent on it, and a lot of companies have been trading less well. Directory prospects not as good as they were. Personally, I think they have been trading off their reputation for quality while the quality of their clothes has been gradually falling - more shades of M&S. I do see the positives, but I have thought it too dear to buy, at least for the last year when I was looking for opportunities, and I'm not sure if it is suddenly cheap enough. A lot of anchoring going on.
Hi xcity,
For me personally Next (LON:NXT) is not about anchoring to previous share price - as I've previously thought it was too expensive when in the 7000-8000p range earlier this year. Also, the published buy price for share buybacks concerned me, as it acts as a one-way ratchet, which traders were gaming, to create a non-stop upward trend. So there was always a risk that it would smash through that floor on some unexpected bad news, as it has.
So I started buying when the price got to a PER on 2015 figures of just below 13. That seems a good price for a fantastic business - although its earnings growth will be a lot slower in future than in the last few years.
The narrative tends to be overly pessimistic in tone with Next I think. When actually they will in all likelihood do what they do every year - execute well, and produce good numbers.
The really interesting thing though is how the company does big share buybacks, year after year. This has led to the number of shares in issue falling by almost a QUARTER since 2010 - remarkable stuff. Good divis on top of buybacks too, so the shareholder return has been fabulous.
After the big drop recently - it's fallen by about 30% since the peak in Dec 2015 - I think it now looks decent value. Bear in mind too that the company will itself presumably now be going into overdrive with its share buyback programme. That provides a nice tailwind for the share price to bounce back somewhat.
Price target for me is a 10% gain from the current level - it's just a trade, rather than an investment for me.
Regards, Paul.
Re: LAKE, the prospective PE is low - but only if their expectations are met. They have already had to reduce them once, just 2 months after the results and positive outlook. They have been taking over businesses quite rapidly, so lots of scope for rot to be discovered in the woodwork and imaginative accounting to make everything seem OK to the customer. I'm not suggesting that any of that has gone on, just that it would be harder to see from outside than in a stable business.
And this statement clearly shows that it is personal between them and Rawlings. Makes it hard to believe that current execs will stay if he wins or that he will just sit on his shares if he loses. You'd imagine he'd be followed by Slater and maybe another institution or two. And it doesn't look rosier for the business if he wins, if the Board's statement about direct involvement is true.
Possibly some current execs are very frustrated with the Board and would love Rawlings back; I don't know, and will be interested to see the Rawlings/Slater response. That will have to be more measured with Slater on board, so would need to peer deeper beneath the lines.
I don't hold the shares and haven't listened to the recording of the presentation, but I don't expect that to sway me either way. They may have been unimpressive at the start, but would have to have been affected by the amount of emotion swishing around. I did place a small limit order after the warning, but it never got down to that level and then went up. I think I would go lower now but, even if I did, I don't think it would reflect the risks involved.
Re your twitter joke:
Q. What do you get if you pour boiling water down a rabbit warren?
A. The cell next to Adam Johnson.
Have a good break.
Lakehouse (LON:LAKE) to me seems like Entu (UK) (LON:ENTU). I held both, I got out of Entu (UK) (LON:ENTU) before the profit warning because I did not trust the management. Lakehouse (LON:LAKE) I got hit but stop loss saved me from the full fall. Although both look good value I doubt I will be investing in either again.
Paul, the problem with LAKE is corporate governance. I personally don't believe the reassurance from the company that they will meet the revised target.
When a company issues a good trading statement as they did in December and the sp keeps falling, it tells me that the trading statement was massaged to get the people in the know to sell on a high. I don't accept that the bod were not aware that the company was not doing well and deliberately misinformed the pi, so for me it's a bargepole stock until the corporate governance is sorted.
I was a holder from 93p but sold out a few weeks before the profit warning because the chart was telling me something that didn't match the December trading update.
Remember MAR, it started with similar sort of issues and ended in the dustbin.
GL and thanks for the report
This is what happens when you open a thread on AFN on the ADVFN bulletin board:
ADVFN is closing this thread. Please do not open any further threads for this company, as doing so will result in your banning from the BBs.
Regards,
John
Says it all, really.
"Also the drivel posted by many of its genuine members suggests that they're (a) not very bright, and (b) haven't got much money."
LOL.
I sometimes find insightful comments and analysis on ADVFN BB's but it does seem that every single corrupt bargepole stock that's heading to zero attracts the most zealous variety of fact and reality resistant investors.
Good afternoon Paul
I have never used this board and I'm not sure if this is the correct way. I have recently purchased some SPH shares after having seen an article in the 'Shares' magazine which ties in with what the latest accounts state and namely the fact that the company has sold part of the business, repaid all debt and is now left with the high growth aesthetic arm, which as we are still in an offer period, might also be sold. It almost looks as if this could be packaged by institutional holders (Toscafund etc) for a sale of all assets and related value maximization for the shareholders. I was wondering what you thoughts were overall ? Thanks and Happy Easter
Paul,
Thanks for making that clarification on Tracsis re the deferred consideration payable on the deals we did last year. As you now know, all of our earn-outs are largely - if not entirely - funded from the profits generated by those businesses and our mantra is always to protect investors on the downside and share a large proportion of any upside (i.e. super profits) with the management of companies we come together with. This model has worked well and keeps people motivated.
As I've said in the past, if any Stockopedia readers have further questions on Tracsis please email me or my CFO (Max Cawthra) directly on j.mcarthur@tracsis.com or m.cawthra@tracsis.com.
Best regards
John
(CEO, Tracsis Plc)
had a look at Next (LON:NXT) as well: it has pierced a few key technical levels today though any name below its 200 DMA seems prone atm (Next (LON:NXT) dropped below that in Dec 15).Has been showing a topping pattern for a while. Might well be that difficult transition as it goes ex-growth given competition in the online retail space.
I've put it on a watch list as it may well test the 5200-5300 region yet. Now below its 50 month MA just as it was in 2008: will see if it retakes this first
Paul re ABDP surprised you have top sliced at this stage. I reviewed my position this morning and came to a similar view to yourself, however after taking into account the asset position, particularly the cash in the bank, it seems prudent to adjust the PER to reflect that. Based on adjusting for the cash I'm getting a PER of around 14. Given there looks to be more growth in the tank, I don't see many better opportunities out there.
I assume you considered this in your decision?
Lee
Lee,
Like you, using an adjusted target PE ratio of 14, I value ABDP at almost exactly the current share price. Given the likelihood of further upgrades implied by the outlook statement, and supported by historical precedent, I am very happy to hold for now, albeit would not look to add.
Here too is a results presentation by Gavin Lavelle Brady (LON:BRY) CEO, a webinar recorded by their PR.
http://www.piworld.co.uk/whats-new/2016/3/24/brady-results-presentation-bry-21st-march-2016
Worth a listen in conjunction with Paul's interview.
Intelligent Energy Holdings (LON:IEH) another blue sky story stock. The SP was 100p not long ago on "Apple' rumours in the papers. When will people learn?
Morning Paul,
It's an interesting development with the F1 team that Ab Dynamics (LON:ABDP) announced today. It would be interesting to see whether any readers had the inside track on these developments.
Management were also flagging continued momentum, leading me to believe that the company may well beat again in the not too distant - despite the Brexit and US election obstacles on the horizon - time will tell I guess :)
Regards,
Sully.
HI Paul,
I know it's outside of the SCVR remit, but It would be interesting to hear your thoughts on the Next full year results today, especially as you covered the Jan trading update. FWLIW I just bought a few at £58 and will look to add if it drops much further because it's still a quality company with great management, so worth paying up for. Do you think it will have any read across to Boohoo.Com (LON:BOO) which is currently only off 1-2% ?
Great work making the Brady interview available so quickly. If only I could listen to it at work!
All the best, Si
I agree about Next (LON:NXT) think they have been oversold but anything negative at the moment is harshly treated. The figures did not look too bad +5%, considering the weather last winter its not a disaster. The outlook is not so good though and thats what has spooked the market, maybe over cautious management, no bad thing. If NXT is negative then the whole sector could be affected. Note Sports Direct warning also. I'm not sure I see it like that, people should have more money to spend with living wage increase, tax cuts and petrol prices falling?
Hi Simoan,
Next (LON:NXT) looks a terrific buying opportunity to me - I've just backed up the truck & bought heavily at 5660p.
Just my opinion, not advice, as always.
Regards, Paul.
I have added as well.
I thought they would be down but I think 13.0% is an overreaction and whilst my assassin’s rifle is ready and loaded I have decided in this case, to be a hunter!
Lord Wolfson, has done an excellent job in lowering expectations for the year ahead, so much so that at the bottom of his range of forecasts, the shares are now valued, on my calculations, at around 13.0x January 2017 likely earnings per share. It is also on a prospective dividend yield of 6.2%, although with the share price weak, much of that, (more than half), is likely to be returned via share buybacks, which of course enhances earnings per share and shareholder value. It could of course get cheaper but this looks a reasonable entry point to me.
Like you just an opinion and certainly not advice. It could go down further!
HI Paul,
Glad to hear reverse gear is working on your truck :-) I am of the same mind. I think the market has taken fright at the reference to the year 2008 and has maybe incorrectly assumed this indicates 2016 EPS will be 168p!!
I have to admit, reading Next results is an absolute pleasure... why can other companies not provide such detailed information with such clarity? In particular, their use of tables to show the full breakdown of various figures such as margins is a model that all other companies should aspire to... take note Laura Ashley.
All the best, Si
I'd be interested to know what affect the Next result will have on BOO and their recent supply contract with Next re low cost unbranded garments.
Will Next see it as an opportunity to offer more low cost (but presumably higher profit potential) goods or will they go in a different direction and offer higher quality etc.