Small Cap Value Report (24 Nov 2014) - NBU, AVG, MPOW, GBG, ECK, SOLI, FLOW

Good morning! In case you missed it, I published another audiocast interview this weekend with renowned investor @WShak1 - click here to listen, sorry for the sound quality not being great, I have a cunning plan to fix that issue next time.
I am flying to Las Vegas in the morning, for a short holiday, so I apologise that there will inevitably be some disruption to these reports this week, mainly due to the time difference, as I will be 8 hours behind. Therefore my plan is to write tomorrow's report as usual from the departure lounge at Gatwick, then Wed-Fri reports this week will be published in the evening UK time.
Naibu Global International Co (LON:NBU)
Profit warning - this Chinese maker of sports shoes warns on profit today, blaming a sales slowdown leading to overstocking by distributors. So margins will be hit in Q4 of 2014, and Q1 of 2015 as stock is cleared by discounting.
Dividends - this company has paid dividends before, but from memory I think they had stopped. However, it says today;
Naibu has substantial cash balances (RMB 315 million as at 31 October 2014) and the Directors are confident that the Company has sufficient resources to implement the programme referred to above.
There seems to be a technical glitch stopping me from copying any more of this accouncement, but there is another section saying that Naibu, "intend to resume the payment of dividends in 2015, once the overstocking issues referred to have been resolved".
My opinion - personally I wouldn't put any reliance at all on any stated intentions, nor the accounts, from Chinese companies on AIM. I remain of the view that the inevitable end game here is likely to be a de-listing, probably in 2015.
Of course, if the numbers were real, then insiders would be massive buyers of these shares, given that the forecast dividend yield is about 50%, and the PER is 0.35! Funnily enough though, they are not buying. What does that tell you?!
Avingtrans (LON:AVG)
Share price: 104p (down 24% today)
No. shares: 27.6m
Market Cap: £28.7m
Profit warning - there seem to be so many profit warnings happening at the moment - which is the main reason that I don't like over-paying for any small cap, as you can end up horribly off-side if you pay top dollar for a company, only for it to disappoint on trading.
The profit warning doesn't look too bad to me;
However, as a consequence of these short term issues, the Board now expects Group revenue and profitability in respect of the current financial year to be similar to that reported for FY14, excluding the revenue and initial losses from the RMDG acquisition. The steps set out above will improve operational efficiency and we expect the full year impact of these actions to be approximately £0.6m, the full benefit of which will be reflected in FY16.
Bear in mind that the company has a 31 May 2015 year end.
The progressive dividend policy is re-stated.
Valuation - actually, looking at the figures, broker consensus was for a big increase in profits this year, so if that's not now going to happen, then it's quite a big profit miss after all.
As my article of 1 Oct 2014 detailed, the accounts at Avingtrans are complicated by lots of adjustments. Hence it's not really clear to me what the true level of profitability is.
The Balance Sheet here is sound, and the dividend last year was 2.7p, so that probably means this year's dividend is likely to produce a yield of c.3%, or just below - not too bad.
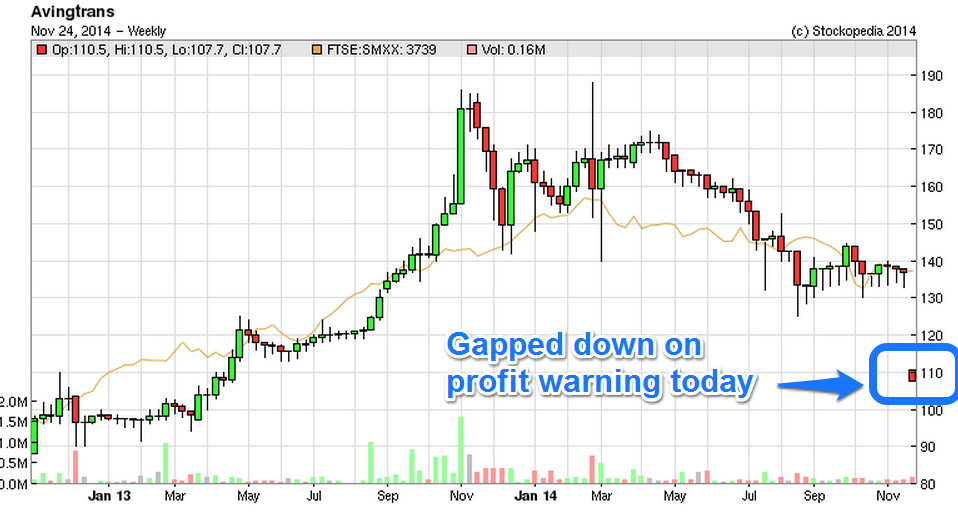
My opinion - today's profit warning gives more detail about reduced demand meaning they will have to make more site closures. So that will no doubt mean another load of restructuring costs, so the accounts are likely to remain messy for some time to come.
I'm going to wait for the dust to settle here. It doesn't look a particularly good quality business, on the Stockopedia metrics, and there are too many adjustments to the reported figures. Although with the share price now back down to a level not seen since the spring of 2013, this could be a reasonable entry point for anyone who likes the company & is prepared to take a long term view, if you think it can recover from the setbacks announced today.
I don't have a strong view either way.
MoPowered (LON:MPOW)
Profit warning - yes, another one!
The company today says that revenue for the year is likely to fall short of market expectations of £1.6m. Honestly, how ridiculous having a stock market listing for a company that can't even manage to do £1.6m turnover in a year.
The company is therefore doing more cost-cutting.
On a more positive note, it has recruited a new FD, and says that it's in the final stages of a "major new product release".
This company did a rescue fundraising only about a month ago. So it's really a question of how quickly they are burning through the cash, and whether the company can turn itself around before running out of money.
It looks a basket case to me. However, micro caps that do manage to turn the corner can become multi-baggers, so who knows? It's too risky for me.
GB (LON:GBG)
Share price: 144p
No. shares: 120.6m
Market Cap: £173.7m
Interim results - for the six months to 30 Sep 2014 are published today.
The headline figures look good, but I'm uneasy about several things. Firstly, and most importantly, the high valuation - it's rated at about 24 times forecast EPS for this year.
Secondly, the profit growth seems to have mainly come from an acquisition. Adjusted operating profit for the six months is up from £2.6m to £3.8m, but note 17 says that a newly acquired company, DecTech, contributed £833k to adjusted operating profit. Strip that out, and the original business only increased profit from £2.6m to £3.0m, not very impressive for such a highly rated share.
Thirdly, there are too many adjustments to the profit figure, and non-recurring items which seem to happen in every half year. Share based payments are stripped out, but this is staff remuneration, and it's running at about 10% of profit. So a material cost, that should not be ignored, in my view.
Taking the clean figures, i.e. ignoring all the adjustments, earnings (i.e. post all costs, and post tax) here are quite modest. Only £3.5m last year, and £1.7m in H1 of this year. That's not a lot for a company valued at £174m.
So overall, I reckon the valuation here has probably got well ahead of reality.
Eckoh (LON:ECK)
Share price: 42.3p
No. shares: 223.1m
Market Cap: £94.4m
It's much the same story at Eckoh - another growth company which looks considerably over-valued to me.
Interim results - for the six months to 30 Sep 2014 are out.
Revenue is up 24% to £7.8m for the six months. Profits? Take your pick, do you want adjusted EBITDA, adjusted operating profit, or conventional profit? Call me old fashioned, but I lean towards conventional profit, and on that basis Eckoh doesn't make any profit at all! Consider this table from today's results;
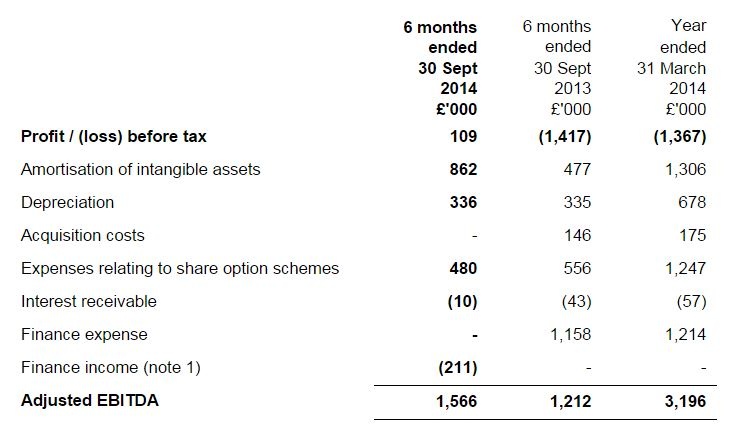
Again, the same issue with share-based remuneration - the company is trying to adjust it out, but it's a material cost here. The way I look at it, the company was loss-making by £1.4m last year, and that was mainly due to the £1.2m cost of giving cheap shares to staff & Directors!
Outlook - the company today says that the seasonality is for stronger trading in H2, and that is expected to be the same this year, and hence the company is confident of meeting market expectations for this year (ending 31 Mar 2015).
My opinion - I think the current market cap is crackers. It isn't supported by what I would consider to be real profits, and so the shares are effectively already pricing in considerable growth in profits in future. Why pay up-front? A bit of bad news could easily derail this valuation by a large amount. So it's too risky in my opinion.
Solid State (LON:SOLI)
Share price: 720p
No. shares: 8.3m
Market Cap: £60.0m
Interim results - for the six months to 30 Sep 2014 are issued today, and look excellent. The big win has come from a £34m Govt contract to provide electronic tagging equipment for hoodlums.
What a refreshing change to read a set of figures with no adjustments, no exceptionals, or highlighted items. Just a single, clean profit figure. This is how it should be done - straightforward presentation, and real profits, not adjusted profit conjured out of thin air!
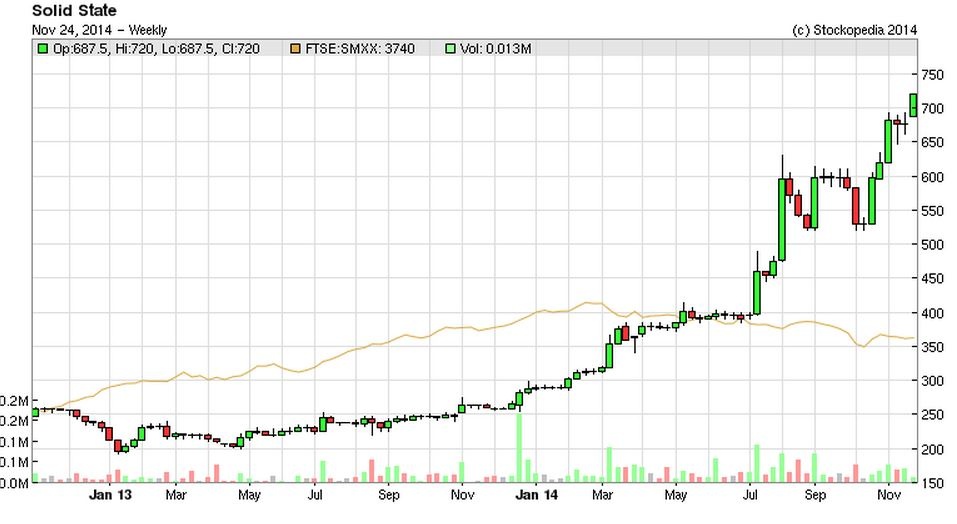
So profit before tax jumped 175% to £1.55m, and basic EPS came in at 16.7p. Double that to annualise it, and 33.4p is the result. The 720p share price is therefore 21.6 times - yikes, that's a very rich rating for a small company like this.
I note that a big jump in EPS to 53.8p is forecast for next year, so the PER drops to 13.4 times, therefore all that profit growth is already priced-in, hence no scope for any disappointment.
More acquisitions are mooted, and a quick review of the Balance Sheet passes my simple tests. A small point to note is that the cashflow statement shows £244k of development costs were capitalised in H1 this year, whereas nothing was capitalised at all last year. So that has helped boost this year's numbers somewhat.
My opinion - I like the business, and the shares have done remarkably well, but the price looks fully up with events now, and there's no room for disappointment. So personally I would be thinking about top-slicing after such a great run, if I held these shares. That's just an opinion, obviously it's up to each individual to decide for themselves.
Flowgroup (LON:FLOW)
Share price: 47p
No. shares: 239.5m
Market Cap: £112.6m
Normally I would rip apart a heavily loss-making company with a blue sky product, at this kind of valuation (over £100m). However, there might be something interesting, albeit highly speculative here.
Flow has developed a new type of gas-fired domestic boiler, which generates electricity as a by-product. Manufacturing is starting around now, using a large outsourced manufacturer called Jabil Circuit Inc - who are US stock market listed (NYSE:JBL) and have a market cap of $4bn, so a sizeable business.
The contract terms have been amended to increase production from a total of 390,000 boilers to 500,000 boilers. So these two companies are not mucking about here.
I will be watching this company closely, to see whether commercial success is likely, as the numbers could be large if this product takes off.
Very high risk, disclaimer, disclaimer, etc.!
That's it for today.
Tomorrow's report will be shorter, and earlier, as I'll be luxuriating in the Club World lounge at Gatwick, but the flight is boarding around 10:30am, so hopefully I can get some meaningful thoughts published by then!
Best wishes, Paul.
(of the companies mentioned today, Paul has no long or short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
£1200 seems to be the minimum, my consumption is far lower, electric is about £200 a year. With price of oil dropping won't price of gas also fall?
That's probably why they advise my consumption is too low for them. My electric is about 3kw per day which should fall when I replace electric cooker with gas cooker and hob. Also my gas should fall when I have cavity wall insulation and a new boiler. As an investment I tend to agree with Paul's comments, it's an interesting company and one I will add to my watch list. I think there is a lot of potential but what about others producing similar products. If heat pumps and heat inverters come down in price, you would not need a boiler?
As has already been stated - the Flow website is very poor about explaning the cost savings to prospective users. It answers none of my queries.
Hi test pack,
Thanks for your response, ok why did Flow say it was not suitable for me then, and it was quoting what they said. Really who uses over £1000 on electric if they have gas central heating, esp. In 2/3 bed houses.
Herbie, I have no idea why it quoted you those figures. The figure that I have seen quoted by Flow is £1200 pa, gas and electric. I would drop Flow an e-mail asking for explanation. The co is starting surveys now, for installation in New Year. The survey is primarily to evaluate if enough electricity would be generated to enable Flow to recover cost of 'free' boiler. and make profit, and be suitable for property. Approx. 100 pre-production boilers were installed in 'test' properties, and Flow stated the feedback was 'Heavenly'. It is highly doubtful the co would contract for production of 500,000 units if the business model was not sound. Claire Spottiswoode is an Exec Dir,, Richard Griffiths has a 5% stake, Aviva 22%, and I'm sure their DD &R was more exhaustive than mine. DYOR & GL
I did send them an email, believe they have an office in Ipswich, thats where I cam across them on the local radio. Anyway I gave them my gas usage figures and they said "We really suggest that you should be spending between £1213 and £2691 on your home energy every year, with between £667 and £1480 of that being on gas". Hmmm I don't think I should be spending £2,000 on energy thank you, I thought people were meant to cutting down? So anyway it seems their boiler are for larger users. If you have an boiler maybe its worth it but then how much do their boilers cost compared to a condensing boiler?
Hi Herbie
You could not be farther from the truth. The 1st generation Flow condensing boiler being manufactured now, is aimed a 2/3 bed properties. Larger property boilers ( ie more output) are currently being developed. The main market is the 2/3 bed property. See above for answer to other concern. GL
They probably don;t realise that this is sales benefit. Also it would be a very different business with ordinary boilers. It would effectively be a finance company and this may not attract the same level of investor interest.
"The biggest selling point of the Flow boiler is the finance."
Then why they don't do this deal with any random boiler? If that's where the value is (and I agree there may be some value for some people here), they could just buy off-the-shelf boilers from the cheapest supplier they can get a group deal with every year. Conversely, if their boiler is any good they should sell it to anyone who'd like to buy it on its own merits (if any). The combo business model is bizarre.
The biggest selling point of the boiler is the 'scroll'. Plse research and see what it does, and then look at other application in which can be used .. Not a 'one trick pony company' Yes, customers can buy it outright.Cost should be revealed early New Year. GL
Do you have independent evidence that the "scroll" is better (in net economic terms) than existing exhaust heat reclaim technologies?
My impression is that it's a me-too technology which, while neat, does not offer a material enough improvement, in a field where the mainstream state of the art is already really good; hence the funky business model instead of licensing the tech to existing boiler (etc) manufacturers.
I'm a PI in FLOW cig, not an employee. All your queries can be answered at Flow's website. GL
The point is I don't trust them to say the (complete) truth, hence the need for third party sources.
When you find a BOD in any company that tells the complete truth it will make history,lol.
A German energy supplier is evaluating boiler now, and reporting results early New Year. That is as independent as you will ever get, a German co evaluating a British designed and manufactured product, If their report is positive, and it enters into a JV agreement, sp N and rapid, and a large USA energy supplier (NRG), already signed as JV partner. Worst case scenario, Germans do not give good report, sp tanks bigtime. You pays yr money, u takes yr pick. Many 'insiders' believe this will be a £1B co in 3 years. sp =£4+. Might be 5p. All in MHO of course. GL
"The facts of the matter is these boilers are being sold."
That's not what they say on their website: the punters are effectively renting the boilers as part of the boiler+bills deal. Would anybody buy them outright? I certainly wouldn't -- it's just too tiny an enhancement compared to mainstream boilers, which are already very efficient, for the risk and hassle of a proprietary solution where you may not be able to use your local plumber and where the manufacturer can rip you off on spare parts, or just disappear and leave you with a lump of scrap metal.
The deal with Jabil looks like a stealth takeover, ambitious targets, short deadlines, punitive covenants (if I recall from last time I looked at it) means it seems likely they'll just own Flow sooner or later with the shareholders not left with much.
Hi cig, Would a large USA based mfg co want to own a retail gas supplier in UK? Furthermore, why would BOD sell co and leave shareholders with 'not much'. Doubtful if Flow would sell patent for under £300M, (All SH, Happy Days) If customer stays with Flow for 5 + 5 years ( the latter when both parties share the benefits of elect, generated), free servicing and maintenance. No rip off. If customer does not like Flow's Thames Tariff, he can choose to purchase outright, enjoy the FIT, and have the boiler maintained by whoever, ( 2 yr guarantee still applies), Flow provide finance, if required, for purchase. DYOR. GL
I am not aware of any short deadline to mfr 500,000 boilers. Info on this would be appreciated.
The more boilers they make the cheaper the parts should get. Today they have appointed Nigel Peter Canham as Chief Financial Officer (CFO) as of 10th December, who has a good track record behind him. He should be a great help to the company, & get them a decent finance deal sored out.
Regarding Beginner's comment that your heating engineer has seen this sort of thing before, with respect it is only one persons opinion. All manufactures try & hype up their figures.
The facts of the matter is these boilers are being sold.
In the not too distant future the potential for millions of them. Because they are a new patented idea a similar boiler would not have all the benefits this one has.
The finance deals available is certainly a big selling point. The fact that it generates it's own electric as well is another good selling point.
If they can get a good write up with the WHICH? report then things could really get going.
That at least would sort out how good they really are. I would like to have seen at least a 5 year guarantee with electric side of things instead of just 2years. This could be built into the price at minimal extra cost.
Apart from that all systems look good to go.
Lightningtiger
I think Igotts has asked all the right questions. High energy prices and expensive spares & service could probably make this quite expensive for the customer.
The biggest selling point of the Flow boiler is the finance. It will probably appeal to people who have no interest in the technology but have difficulty in finding the upfront cash for a replacement boiler.
I hadn’t realised that the boiler needs a hot water storage tank as well? I guess that this is because it lacks the output for instant hot water. Obviously heat loss from a tank would also have to be factored into the equation.
Also from the same site above is another video showing ITN with a customers satisfaction with his new boiler. This has taken 10 years to develop. They know from their research that their boilers have customer appeal similar to solar energy giving something free from the clever engineering incorporated within the boiler.
You can see it recirculates a fluid that drives a generator for the electric & also has a built in heat exchanger which makes the boiler 92% efficient. It also has a patent on it.
There must be a better way for a lender out there somewhere given a "Dragon's Den" business plan of this company, that can come up with £2M or £3M to get them started off!. Clearly over 9% is far too much. Is there any Bank managers out there that can cut a sensible deal for them better than that?
Lightningtiger
I enquired with the guy that does my heating about these type of boilers. He has seen similar systems before, and has also looked at these. He is convinced they simply do not work at the figures supplied by the manufacturer. Overall they provide no real saving to the consumer at all. this is posted just for info.
Clearly lightningtiger, you have misunderstood the business model. Rather than being told what is, as in Dragons Den scenario, DYOR and come to a conclusion on your misunderstanding. GL
Hi lgotts, I have been talking to Flow today. Their head of marketing Alex confirmed the increase in production at a more favourable rate than before which appear to have been a huge 9.5% (which I got from another source). The website to see how it works is http://vimeo.com/106474107.
Soli has been in my watch list for a while now & has a nice double bounce just below 550p.
Thanks for superb write up Paul.
Lightningtiger
Just trying to understand what Flow actually have. Their website doesn't state the technology they use, but it is probably the Stirling Engine version. The future is in Fuel cell versions, but probably a way off. Baxi already have a Stirling engine version on the market which generates 1KWh of electricity, and I saw a comment saying German firms already sell them. What none of them say is that they only generate electricity when the boiler is on, so very little in the summer.
What seems to be different about Flow is that they don't charge for the boiler (unless they load it heavily into the installation cost, which you do pay), but you are committed to FLOW Energy for 5 years, at whatever prices they charge. They also make it appear that they are talking to other devices electronically, so inveigling their way into your house infrastructure?
So to the consumer the cost of a new boiler seems a lot less, but presumably you get stuffed on tariff later, but FLOW therefore are footing the manufacturing cost of each boiler up front. Interesting business model, but how reliable is their technology? Or do you get stuffed by them being the only ones who can repair it at this time, as your average central heating man won't touch it? Might be tricky outside London until they get enough scale to have local fitters. I've seen similar situations with underfloor heating where the callout charge starts at £250.
BTW I didn't see anything saying over what period they were calling off these boilers from Jabil: did I miss it?
Hi igotts
!) Not a sterling engine version. DYOR
2) Obviously only generates elec. when boiler is on. As you know, the most efficient way to run central heating is run the system for 24 hrs per day in Winter ( or cold snaps), at whatever temp you decide as background warmth.
3) You can be committed, or not. If yes, the Thames Tariff is one of the cheapest in the market place.
4) 'Inveigling their way into yr house' It's called The Internet of Things.From yr mobile, through a smart device ( incorporated in the boiler), control your boiler, alarms, cooker, lights, swimming pool temp etc.. If of no interest, do not fone smart device.
5) At present have over 3000 trained installers and maintenance ( to include Calor, Mears, and independents), Most of these, believe it or not, are outside London. Yeh, shocking isn;t it. The yocals getting something good. lol. Bad news though, Flows HQ is in Lancashire, or some other backward north country county.lol, btw, If customer takes the 10 yr deal ( 5 years to 'payback' boiler cost, and 5 years when elec, generated through Feed In Tariff is split 50:50 between customer and Flow, NO maintenance or service costs. Gets better, yes.
6) 500,000 offtake agreement with Jabil. ( who btw, finance all of the production costs, and with that amount of capital expenditure, on a new mfg plant in Scotland, have done more DD than you, Paul and me. I doubt if it is into high risk ventures. $4B MCap says not. The factory output can be variable., 1, 2 3 shift production? Market in UK is 1,6M replacement/new boilers pa. Unlikely to get 30% of market within 3 years ( ie. contracted offtake over 3 years). No figures released on max output since plant has only just started full time production. Best case scenario is that production cannot meet demand.
With agreement already in place for JV in USA, and major Eu gas supplier ( German) evaluating boiler now, exciting times ahead for shareholders. All in MHO of course, and DYOR. GL
Yes it maybe best to run heating 24 hours a day but that does not mean the boiler is running 24 hours a day, if temperature reaches the temp. Then boiler will cut out. Also when you go to bed most reduce temperature on thermostat, if I reduce mine to 15c then the heating does not come back on until at least 8am unless it's cold at night, last night it was freezing but thermostat did not come ont until 8. Also this is only in winter ie December until March in my area even then if it's mild or sunny you don't need much heating on.
DYOR, but my impression is this: You are contracted with Flow for 5 yrs, G&E. You pay on a monthly debit, say £25 ( actual figures being released in Jan), to purchase the boiler in 5 yrs. Flow credit yr A/c £25 every month, irrespective of the amount of time the boiler is running, effectively, the boiler is free. After 5 years, customer and Flow split income from Feed In Tariff. Flow take the 'risk' that yr gas consumption ( weather dependent) is sufficient for them to make profit. It is looking at World wide sales of boiler, it will not be 'mild' everywhere.. There are smaller and larger models being developed now. The scroll has other industrial applications. Check out website in detail. GL
I understand these boilers are expensive, Baxi do one that costs about £6,000, I'm struggling to understand how Flowgroup will make any money out of this, if they do it will be a long way down the line?
get a grip Paul. holidays should be free from work of any kind. I had a week on holiday with no internet getting back to basics last week. It gets the mind working in different ways and refreshes mind body and soul.
Im astounded that people seem bound to work and internet when on holiday. Those who somewho cant free themselves are missing out on the rest of lifes experiences.
Enjoy what time you have on holiday. I think your mental though, in a nice way!
paul.
Hi Paul,
I don't see the markets as work!
A couple of hours per day doing the markets, then switching off the laptop & doing other stuff, is the perfect balance for me, when on holiday!
Although the time difference is going to be a real challenge with Vegas - the RNSs will start at 11pm Vegas time, and the UK market will open at midnight Vegas time, which will probably coincide with me reaching peak alcohol levels. So this could get interesting.... !
Regards, Paul.
"I really love that Rob Terry, he's my bestest mate. What a diamond geezer. Just gone long £10,000 a point on QPP. Cheese!"
Or not, as the case may be. Have a great time in Vegas and wipe the floor with those damn Yanks poker-wise.
:-)
Steve
Enjoyed the audiocast - in case others haven't already tried, I found that changing the balance (increasing volume of right hand speaker) made a big improvement to quality.
Best of luck in Vegas from me too, Paul.
My favourite song about Vegas and gambling:
https://www.youtube.com/watch?v=8uJqoIVC9hI
Steve
Best of luck in Vegas Paul-financial report eagerly anticipated on your return!