Small Cap Value Report (25 Feb 2016) - SOLI, TIDE, LVD, MLIN, CWR, IDOX

Good morning!
Lots going on today, so I'll probably be gradually updating this article all afternoon, so please feel free to refresh the page later.
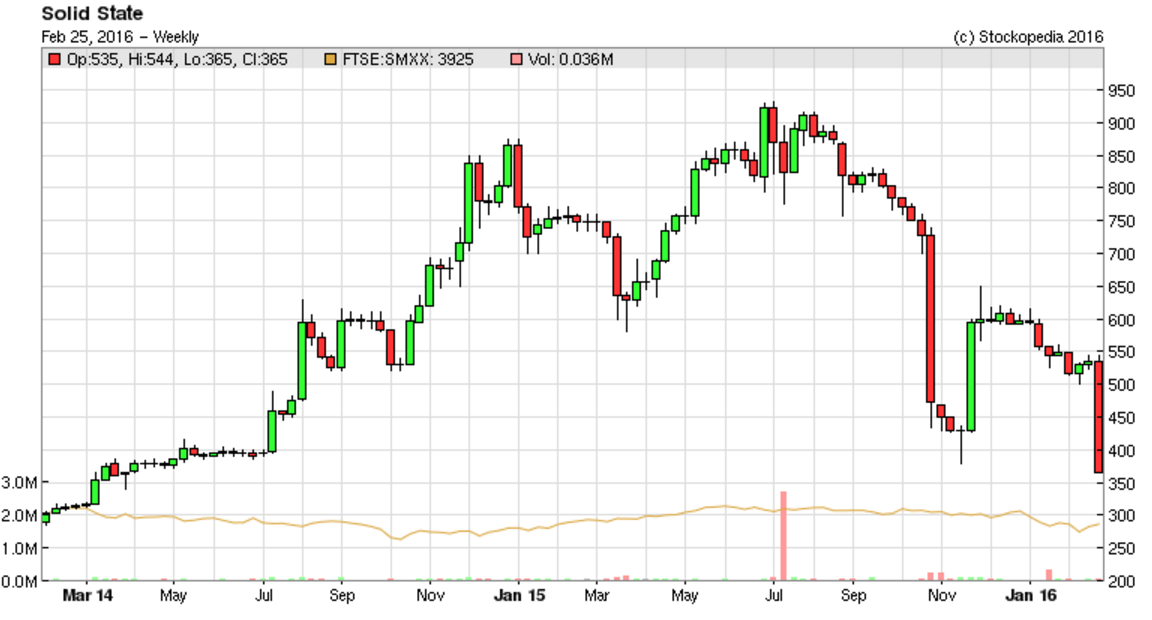
A bad morning for investors in this one, my commiserations;
Solid State (LON:SOLI)
Share price: 367.5p (down 30% today - very volatile)
No. shares: 8.4m
Market cap: £30.9m
I last wrote about this company here on 29 Oct 2015, when it issued a profit warning for H2 (Oct 2015 to Mar 2016), blaming "contract variations and general market softening" - the contract concerned being a highly material MoJ contract for electronic tagging for offenders.
This led to a substantial reduction in broker forecast EPS, down from 56p to 36p. It seemed very strange to me that the share price rebounded from a low of about 390p on Nov 18, to around 600p in Dec 2015. The revised forecast clearly didn't support such a big rebound to 600p, as that equated to a PER of 16.7 - very high for a really ordinary company, with lumpy revenues.
MoJ Contract Update - it's bad news. The delayed contract is now cancelled;
Solid State plc (AIM: SOLI) has today been informed of a decision by the Ministry of Justice (MoJ) to terminate the MoJ's contract for Electronic Monitoring Hardware with its subsidiary Steatite Limited. Steatite Limited is to enter into discussions with the MoJ regarding the terms on which the relationship will end.
The last bit is presumably to discuss if, and what amount, of compensation the company can negotiate. That depends on factors which are only known by the company, and not us - what were the contract terms, why was it cancelled, etc. If the cancellation was due to poor quality or service, then SOLI may not be entitled to any compensation at all. Or if the company did everything they were supposed to do, but the MoJ just changed its mind about wanting the product, then compensation may be payable to SOLI. We won't know until SOLI updates us again.
In terms of valuing the company, personally I would assume no compensation, to be on the safe side.
Financial impact - the house broker has put out a note today, saying that they had already removed the MoJ contract revenues from their forecasts (to be prudent), hence forecasts are unchanged on today's news.
Is this a market over-reaction then? The EPS forecast for this year is 36.0p, and next year 36.5p, so it all depends what PER you think is appropriate.
For this type of business, personally I would not go higher than say 8-10, so I'm arriving at a share price in the 288p to 360p range.
Balance sheet - the last one looked alright overall, with only a modest amount of debt. Although the worry now is whether there will need to be any write-offs from inventories and debtors, relating to the MoJ contract, which could be material. Until this is known, it might be safest to apply a further discount to the shares, to cover any losses that might yet come out of the woodwork and may not be covered by compensation - we don't know yet.
My opinion - at the time of writing, the share price is 367p, which is slightly above what I consider to be the right price for this share, of 288-360p. Therefore it doesn't interest me as a knife-catching situation.
The reality as I see it, is that the share has been significantly over-valued for some time, and is only now coming down to a more realistic price, for what is really a very ordinary business. It's very illiquid too, so we'll have to see where the price settles in the coming weeks.
Sorry if people think I'm sticking the boot in, but I've been very consistent about this share, warning in the past on a number of occasions that it looked over-valued. A lot of last year's momentum darlings are crashing down to earth with a bump this year. That's the trouble if something goes wrong, at a company which has snowballed up to an irrationally high valuation.
Crimson Tide (LON:TIDE)
Share price: 3.5p (up 25% today)
No. shares: 445.5m
Market cap: £15.6m
Trading update - this is a new company to me, but today's update looks potentially interesting, so thought I would get some notes into the system, to refer back to in future.
It's a tiny software company, based in Tunbridge Wells. I've had a look at the company's website, and the software seems to be a mobile app, which enables employees to submit information to head office, about deliveries, jobs that have been done, need to be done, etc. Looks interesting. Also there are some impressive logos on the website, of big name companies that are existing clients. This has piqued my interest.
Today's update sounds really good;
The Company expects that Profit before Tax will be higher than market expectations and significantly higher than for the previous year. Turnover is expected to be in line with market expectations.
Trading in the early part of 2016 has been robust and has seen a number of new transactions being progressed both in relation to contract wins announced in 2015 and also new subscriber transactions for the core mpro5 service. In addition, new pilots are being rolled out in respect of potentially significant client contracts.
The Directors are confident of further growth during 2016 and beyond.
My opinion - it all sounds great until you look at the numbers. Turnover was only £673k in H1, and pre-tax profit was £60k. Sure that was 140% up on H1 last year, but £25k wasn't exactly a challenging target to beat.
It's impressive that the company can be profitable, when so small - suggesting that it's a Mom & Pop type company. Expanding would I'm sure mean taking on more overheads, so it would be a mistake to assume that increased sales on 90% margin will drop straight through to profit.
Overall, it looks potentially interesting, but to my mind the company is far too small to command a £15.6m market cap. There must be numerous other companies offering similar software products - although very impressive that TIDE has won some big name clients.
So it's one I will certainly be looking at in future, but for now I think the price is way too high.
Lavendon (LON:LVD)
Share price: 136.6p
No. shares: 169.7m
Market cap: £231.8m
(at the time of writing, I hold a long position in this share)
Results y/e 31 Dec 2015 - just a quick review of these numbers, as everything looks fine, and I'm pushed for time.
Revenue almost flat (up 1% to £248.6m)
Profit before tax up a much stronger 13% to £38.5m (I'm working from the "underlying" numbers.
EPS of 17.95p is up 15% on last year, and seems to be about 5% ahead of broker consensus of 17.1p, so a positive surprise on earnings today.
Statutory EPS is only 4.91p, so a huge difference. This is mainly writing off exceptional goodwill - a non-cash item, and "well flagged" in advance according to a broker. So no concerns there - the adjustments look fine to me.
Full year dividends - up 17% to 5.4p in total (interim + final) - giving a fairly attractive yield of 4.0%
Net debt is up 33% to £119.2m, again as expected, due to increasing size of hire fleet. This looks reasonable relative to £284.2m in fixed assets
Balance sheet overall is very good - net assets are £222.9m, take off ££45.5m goodwill, and £6.6m other intangibles, and NTAV drops out at £170.8m. Therefore the P/TBV is 1.36, which is low for an equipment hire company (nearer 2x is more normal).
Outlook - sounds alright to me;
Trading in the current financial year has been in line with our expectations and, whilst recognising the recent increased uncertainty in the economic outlook, the Board looks forward to delivering another year of progress in 2016.
Valuation - the PER is only 7.6, which looks remarkably cheap when you compare it to other hire companies, once you adjust their net debt to be comparable anyway.
So why is LVD such a bargain relative to other hire companies? I think it's because the group is so reliant on profits from Saudi Arabia, and fears that this region could collapse if the low oil price continues.
The share price here at LVD therefore already discounts a collapse in M.Eastern earnings, yet there is no sign of such a collapse happening (yet, anyway). If the market turns out to have been too cautious, then this share could re-rate higher. If M.Eastern earnings do fall heavily, then arguably it's already in the price. So risk:reward looks favourable to me.
Overall then, I like it a lot, and think it looks great value - providing the M.East earnings remain reasonably sound.
Molins (LON:MLIN)
Share price: 67p (down 14.6% today)
No. shares: 20.2m
Market cap: £13.5m
Results y/e 31 Dec 2015 - if you ignore the pension fund issues, this share looks superficially cheap. However, the "Pensionschemes" section in today's results is arguably the most important bit to read. It shows that the pension funds are gigantic, dwarfing the size of the company, and that £1.8m payments were made by the company in 2015.
However, this bit sounds scary;
The Company is also responsible for paying a statutory levy to the Pension Protection Fund. The quantum of this levy is dependent on a number of factors, including a specific method of calculating a pension deficit for this purpose and a credit assessment of the Company, the methodology for which is also specific for this purpose. The levy that will be paid in 2016 is largely linked to the Group's financial information reported in the year to 31 December 2014 and it is expected that this will result in a payment considerably in excess of the 2015 levy.
Dividends - the final divi has been cut from 3p last time, to 1.5p this time. Although a 2.5p interim divi was also paid, I suspect that might also be cut, or passed, next year.
Balance sheet - this looks superficially alright, but it really doesn't reflect the true position, because of the ridiculous rules on accounting for pension deficits.
My opinion - in an era of apparently now permanently low interest rates, pension deficits get worse, and don't melt away. For this reason, with such huge pension liabilities, relative to the size of company, I think Molins is now uninvestable. So it's going on the Bargepole List I'm afraid, as being now too high risk.
Also I have major ethical issues about anything to do with the tobacco industry, which is a large part of Molin's activities.
Ceres Power Holdings (LON:CWR) - scary figures out today, for the 6 months to 31 Dec 2015. This is a hugely cash burning company and there's only enough cash left to last about another 12 months. The company says;
The Company ends the period with £12.8m in cash and cash equivalents and short-term investments (2014: £22.7m) and we have a good expectation of raising further funding before the end of 2016, which is required in order to continue our activities and to fund the growing opportunity we see in the higher power markets, and supplements income from customers and government grants.
Too high risk. It's going on the Bargepole List.
Idox (LON:IDOX) - an upbeat-sounding trading update today. The company looks to be on a roll, so is possibly worth a closer look in my view.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
I would suggest that the premium rating of Solid State before today's news was justified by the company's financial performance since 2010 which includes the dividend per share increasing by around fourfold and the reported and normalised eps increasing by around fivefold. When you combine this with the fact that the company's return on capital employed has been between 20% and 30% for nearly all those years I think you can see why some investors think the company deserved a premium rating. The problem with the MOJ contract is a major one but as far as I can tell, it does appear to be an isolated one. I await more information with interest to determine the extent to which management was to blame.
Small Company Sharewatch have been a continuing supporter of this share. even when the SP has been falling. This is one of their more interesting comments from May last year - they have made on average 6 monthly comments pa for some time on LVD and I would guess they are as perplexed as the rest of us!
I find their comments in the last few paras - from 'At current share prices.....' onwards - particularly interesting and I am holding for this - and of course the 4% divi!
Thoughts anyone?
May 15
Lavendon - UK trending higher
174p Epic code: LVD
(Sharewatch) A confident Q1 trading update from Lavendon. Despite relatively modest growth in revenues of just 1%, efficiencies mean that Lavendon expects much faster growth in profitability, margins and return on capital employed. Keynotes were the UK trending higher towards the end of the quarter whilst efficiencies have driven profitability; the Middle East has continued to storm ahead (+11%) with the weaker oil price environment not really affecting activity. Other European territories are unchanged on last year.
At current share prices, Lavendon’s days of independence really do look numbered. Additional equipment has recently been added (ahead of schedule, temporarily lifting net debt to £103m) but the wider investment community hasn’t picked up on the fact that the frantic investment programme will start to peter out towards 2017 as a huge chunk of the fleet will have then been refreshed, after which this company will throw off a tidal wave of cash.
Any would-be-predator would be wise to bid now whilst the shares remain so undervalued. Buy.
Hello ridavies
Seems like a very positive opinion piece- deffo glass brimming to the top, i always get a little worried when the good ol' days are a couple of years down the line - i guess the Broker forecasts for 2016 and 2017 should give us some clues.
The accounts state that 40% of the rental fleet has been refreshed over the last 4 years - i look at this and say 60% of the rental fleet is over 4 years old. I am not sure how long fleet can last but it still seems like a material amount of stuff is older (ok this may change over the next 24 months)
With regard to net debt this increased by £30 mill - with £95 mill of investment in plant this year.
They mention this will trend down to £55 mill in the future - "largely being self funded" as they say.
So an improvement of £40 mill a year - lets say £10 mill positive debt reduction - add on £8 mill of divis paid and that's £18 mill of real cash generated per year - acceptable but not exactly rolling in cash i would say. Ok that's ignoring any excess investment in the fleet but i am not presuming this fleet investment is going to deliver extra earnings until i see it in the Broker note :)
Looking at the depreciation policy - this is the biggest number in the accounts and the most important figure with regard to potential for overstating profits - closing NBV = 303 mill - add on depn 41 mill - take off half of asset adds this year -46 mill = 298 mill. 41/298 = 13.8% - this is a very low depreciation % rate IMHO - maybe my calcs are little unscientific but anything below 20% seems low to me when using a prudent philosophy that anything over 5 years is more likely to be old tat than anything useful - hopefully with LVD their plant is stuff that will run for 10 years with no bother but i am not presuming that it will.
In summary i don't believe the hype but am hoping that the hype will come true. As Paul mentions there is enough wriggle room in that it is priced in at a low level that even if there is no jump in profits and no miracle excess huge chunks of cashflow there is a reasonably solid underpinning of the current price as long as the profits maintain a reasonable degree of stability.
This is probably a good time to applaud the balance Paul shows in his articles nowadays - the articles generally always show a good warts and all opinion even when he does hold the shares - i think its always good to be skeptical even when one is positive as sometimes looking for the first chinks of trouble ahead makes one better placed to act fast when things start to change for the worse.
Hi rmillaree
"Looking at the depreciation policy - this is the biggest number in the accounts and the most important figure with regard to potential for overstating profits - closing NBV = 303 mill - add on depn 41 mill - take off half of asset adds this year -46 mill = 298 mill. 41/298 = 13.8% - this is a very low depreciation % rate IMHO - maybe my calcs are little unscientific but anything below 20% seems low to me when using a prudent philosophy that anything over 5 years is more likely to be old tat than anything useful - hopefully with LVD their plant is stuff that will run for 10 years with no bother but i am not presuming that it will. - See more at: http://www.stockopedia.com/content/small-cap-value-report-25-feb-2016-soli-tide-lvd-122297/?comment=17#17"
I'm not trying to be argumentative but I think you've got this totally wrong , powered access platforms are not generally hard worked, their role is to get the operative to height and keep them their safely whilst they accomplish the task.
Compare that with say an airliner , BA will typically keep an aircraft for say 15 years and during all this time it is working flat out.
In 2014 , Lavendon lost £37k in total on equipment de fleeted, that suggests their depreciation policy is pretty much bang on...especially as the average fleet age is diminishing.
You're right that this one of the key issues but I trust an experienced mgt with skin in the game to be suitably cautious.
"This is probably a good time to applaud the balance Paul shows in his articles nowadays - the articles generally always show a good warts and all opinion even when he does hold the shares -"
Having read Paul's stuff for over a decade, I am all for applauding. He is reliably both rigorous and honest - an extremely rare and valuable combination. And these days he seems to keep "going off on one" to Twitter, although I always enjoyed the late night, lubricated posting ;)
Jon
I think part of the re rating will be when the oil price recovers and thus de risks their ME earnings, the other part of the re rating is in mgt hands , ie.when they can demonstrate that remedial actions in Germany and to a lesser extent Belguim are paying off. My view is both issues will unwind over this year and will combine with the improved and enlarged fleet profile to give us a substantially higher shareprice by year end.
Meanwhile I get paid 4% so I'm happy to wait
Thanks very much for your reply, Glen. Puzzling why it hasn't re-rated. Regards, Clive
Hi Glen. Are you saying that you don't believe M&G have been selling substantial quantities of Lavendon stock? Or could there be another big share holder selling instead? Thanks.
Hi Clive. I don't believe they are selling LVD stock. I was looking at LVD RNS list. I use the investigate.co.uk site, its free registration and you can set up alerts to send news for the companies you follow to your email account. One major shareholder Kames was selling in June last year and had to issue an RNS. There have been no such RNS from M&G, so I can only assume it's not them selling the stock.
I own shares in LVD for the last couple of months and I am at a loss to see why it isn't re-rating.
When I was a teenager, the M&G recovery fund was one of the star performers. It encouraged me to invest in unit trusts. It took me 5 more years to see the light.
NI
Paul,
Regarding SolidState, you did suggest the 600p as an upper limit if someone held the view that it was just a wobble. (EPS of 50p with a PER of 10-12)
Perhaps some thought that was the case?
NI
According to their website M&G holds 19% of Lavendon. Presumably this is held within the M&G Recovery fund, one of the largest and worst performing funds in the UK All Companies sector. M&G Recovery assets at 12/14 £5.01bn; 6/15 £4.5bn; 12/15 £3.7bn thus M&G most likely has been and will remain a forced seller until they can turn around the fund performance and thus flows. I think this explains the lack of upwards momentum in the share price despite the positive newsflow and cheap valuation.
If M&G are selling they would have to put out a TR-1 RNS when, according to the FCA website, their shareholding ...
"(1) reaches, exceeds or falls below 3%, 4%, 5%, 6%, 7%, 8%, 9%, 10% and each 1% threshold thereafter up to 100% (or in the case of a non-UK issuer on the basis of thresholds at 5%, 10%, 15%, 20%, 25%, 30%, 50% and 75%) as a result of an acquisition or disposal of shares or financial instruments falling within DTR 5.3.1 R"
Paul, to put Saudi into context for Lavendon for the benefit of other readers I thought I'd quote from the RNS which says:
"As reported previously, the geographic drivers of revenue growth in the [Middle East] region have changed with strong growth in the UAE, Qatar, Kuwait and Oman more than absorbing a revenue decline in our higher margin Saudi Arabian business. This was particularly evident towards the end of the year, where the delivery of additional fleet capacity was largely into markets other than Saudi Arabia and delivered an accelerated rate of year on year revenue growth of 10% in the final quarter."
I imagine LVD share price also remains a bit depressed because of concerns about the growth of construction in the UK and globally more generally.
Interestingly there are a few companies who have recently reported reasonable or good figures (in contrast to their share price) where the share price remains relatively static e.g. like ENTU (this had an initial spike post results which now seems to have come back down). It's a bit disappointing LVD also hasn't risen more at the time of writing.
Regarding Lavendon (LON:LVD) and Saudi, there's an article in this week's Economist about the complexity of the Syria situation. The article puts forward a scenario where Saudi wades in with their troops. They're already undertaking war games on the border apparently.
Paul,
Do you plan to comment on Alternative Networks (LON:AN.) in your report today? Share price down 30%+ on trading update from this top ranked (QVM), Telecom sector, company. Would be interesting to have your perspective.
It's unusual to put out a trading update at 5pm.
I would have expected the increased pressure on margins in their mobile business to have been anticipated, yet SFAIK they gave no forward guidance (and have not forecast profit or cashflow in the update, only revenue and dividend).
Alternative Networks (LON:AN.) paid 16.4p dividend last FY (14.5 p according to ADVFN) and the update says this year it will be 10% higher, so that's a yield of around 5% at the current SP, but the cover was 1.42x last year, so it may be uncovered this year, and debt is already quite high.
I know Alternative Networks a little from my previous job and think they are a very good business. Their customer base includes a high share of City and international business users so their explanation that they have been hit hard by the regulatory restrictions on international roaming charges strikes me as entirely correct. The trouble for them is that that isn't going to be reversed any time soon unless just conceivably at some point post Brexit if the EU rules were to stop being applied.
Awaiting the Lavendon Update with interest presuming one will arrive, tricky company to put a value on - i have bought a small stake as it seems a reasonably well run outfit that has a reasonable Niche and the shares have some good value characteristics.
Being honest though with this update it strikes me that they are struggling to stay still, i would be a much happier bod if they didn't "need" to invest more than they make to generate the profits they are making - this may pay future divis - but as a reasonably mature business debt going up a wad without a matching increase in profits is not ideal. I am not saying management should be doing anything different but these results do give the reason why the market is allocating such a lowly rating.
I am always particularly skeptical relying on reported profits with a company like this as its sooooooo easy to take a non conservative depreciation rate that only catches up with the business at time when turnover decrease/plant gets older or when bods don't want to hire that dilapidated asset.
To be fair to the company they have clearly given a future with regard to future investment in their Plant so hopefully that's a debt peak but looking at the numbers it doesn't strike me that there will be much positive cashflow free at all over the next couple of years on a year end position (I.e ye net debt).
The wording isn't saying they are going to shoot the lights out this year, so i have to look at Broker Forecasts to see that there doesn't look to be a big spike up at present in 2016 EPS - i guess once we have some updated Broker notes for 2016 and 2017 this is time to see if the company is worthy of holding onto. I am a little nervous with their business type that if business is doing the opposite of booming in their marketplaces generally, they may be liable to struggle more than your average business - more of a niggling worry based on how quickly it has gone wrong for other stockmarket companies - mostly probably due to the fact they mostly start with their beer glasses 80% full which makes it harder to outperform expectations than under deliver - ho hum.