Small Cap Value Report (26 Jan 2016) - Credit, TRAK, RST, XLM, MCGN, OPM

Market wobbles & credit conditions
Just when we thought it was safe to get back in the water! Things are looking wobbly again - the US rally has fizzled out for now, and the S&P500 futures are now hovering around a key support level of 1867.
The rally in oil has also quickly reversed, and China took another tumble overnight, see this chart courtesy of IG;
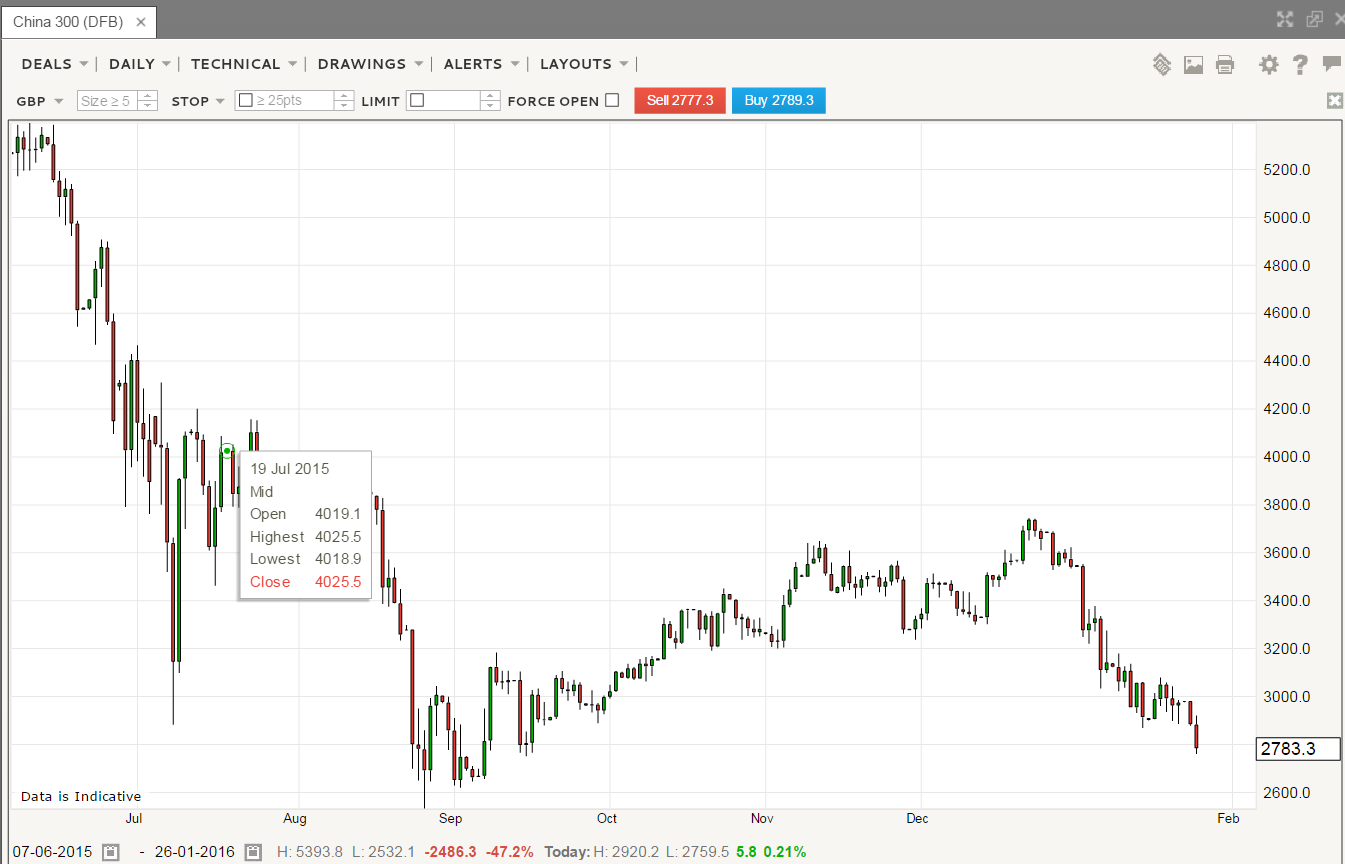
Market gyrations are one thing, but more people are becoming aware of the pressures building up in bond markets - where junk bonds are problematic, and there are likely to be widespread defaults in bonds related to the resources sector.
Have you looked at the share prices of banks lately? They are down very heavily. That is a warning sign to my mind - clearly the market thinks that there's trouble ahead. I think that makes sense - as mentioned the other day, 7 years of near-zero interest rates has undoubtedly caused gigantic misallocation of capital (e.g. apparently China has 65 million empty flats!), and when some sort of trigger occurs to start defaults happening, then bad debts begin to appear.
At that point everyone starts worrying about contagion, and counter-party risk, so credit availability tightens, and weaker financial institutions get into solvency trouble. In other words a re-run of what happened in 2008. I'm not saying it will necessarily be as bad as that, but I am getting increasingly worried about credit conditions.
Bank balance sheets are much stronger than they were in 2008, but I think we could well see tighter credit availability - which would be likely to push us into another recession. Therefore I think it's a good time to look closely at everything in your portfolio, and consider whether earnings might now have peaked - does the valuation still stack up if earnings were to drop say 20-50%? Almost certainly not, in many cases.
This could be scaremongering, and everything might turn out fine, we don't know. I always like to consider what-if scenarios though, and at the moment I'm wavering between thinking things are probably going to be alright, and waves of worry about the risks.
I'm keeping my eyes peeled for more cautious outlook statements from companies, as that is one of the canaries in the mine, along with forward-looking economic data, such as PMI reports each month.
Oil
Not my area of specialism, but I want to flag an excellent post from one of our top commenters here, janebolacha, in the comments section of yesterday's report. Jane pointed out that US shale producers had greatly lowered costs, and can quickly stop & start production. This might therefore cap the upside on the oil price in the future, as when it rises to a certain point (perhaps $50-60?) then the shale producers will crank up production to meet demand.
That changes the likely earnings & valuations of oil companies in the future, and means previous profits may never be reached again.
Furthermore, we are probably fairly close to a tipping point where electric cars become commercially viable - it's all about the price of batteries, and the range, and it's getting close now to being economic. If you haven't seen it, this video from a Stanford University lecturer about the future for oil is absolutely riveting - investors that I've sent the link to before have loved it, so highly recommended. Here is the link - do watch it if you can find the time, or indeed I suggest making the time, as it's well worth it. He suggests that virtually the whole oil industry will have gone by 2030!
Trakm8 Holdings (LON:TRAK)
Share price: 240p (down 9.4% today)
No. shares: 34.0m
Market cap: £81.6m
(at the time of writing, I hold a long position in this share)
Director audiocast - it took a lot of time & effort to put it together, but I recorded and published a one hour interview with the Exec. Chairman (and with FD standing by, but not needed in the end) of telematics company TrakM8 last night. You can listen, if you wish, using this link.
Unlike other, commercial, company interviews, my interviews are done by an investor, for investors. So the questions are sourced from the investor community itself - anyone can ask questions, whether bullish or bearish on the company. I just put the (often tough) questions to the company, and occasionally pose a follow-up question. So it's not promotional, it's informational, and so far the response to this series of interviews has been very positive, so I'll keep doing more of them.
There was an amazing response, with 50 questions submitted. I eliminated 3, as one was silly ("where can I short this share?!"), one was just personal abuse directed at me - it happens, I'm used to it, the shares world just seems to attract some very odd characters who enjoy spouting venom towards anyone who has a profile, and the last disallowed question was something pointless & irrelevant.
The other 47 questions were posed by me to the Chairman of TRAK, and I thought his answers were thoughtful, clear, and intelligent.
The bear raid was basically shown to have little basis in fact, specifically;
Net/gross cash - the company accepted that they made a mistake, in the bullet points with recent interim results, incorrectly describing gross cash as net cash. They apologised, and so this issue is now put to bed. The figures on the actual balance sheet itself, were of course correct.
Discrepancy between reported Box accounts, and the reverse takeover RNS of Box by TrakM8 - the c.£115k discrepancy was due to audit requirement to change from GAAP accounting to IFRS accounting. So a complete non-issue.
Lack of free cashflow - incorrect. The company explained that its cashflow is positive. Its business model involves low margin up-front sales of the telematics units, but there then follows a high margin, sticky monthly revenue stream. So rapid growth means short term depressed cashflow, which then reverses as growth slows. Again, not an issue.
Growth is all by acquisition - er, except that it isn't. The company achieved over 70% organic growth last year.
Route Monkey acquisition was crazy, along with its accounts - the Chairman calmly explained that of course they had done detailed due diligence, and that the odd revenue recognition policies of RM when in private ownership would be restated. Although he explained that the company had a history of good cash collection on its extended debtor book - which was due to the company working on extended projects for customers, and then eventually billing them at the end, when the client was happy with everything. That's a poor way of doing things, and I'm sure that within TrakM8 a better structure (e.g. with stage payments) will be agreed. The price paid for RM is based on expectations for what it will earn in future, not what it has done in the past.
Therefore, I think that covers all the bear points, which have clearly been shown up to be a storm in a teacup. I do wish people would properly research these things, and give a company the chance to explain questions, rather than firing off an ill-judged dodgy dossier online, designed to make novice investors panic sell their shares.
Hopefully I have redressed the balance, and given everyone an opportunity to ask the questions they want. People can then decide for themselves what to make of the responses. I remain bullish on the shares, but that's just my personal opinion.
I'm not planning on entering into any more public dialogue with bears on this share, as it's just been a can of worms, and has caused me a lot of unnecessary & unpleasant stress.
Restore (LON:RST)
Share price: 286.5p (unchanged today)
No. shares: 96.0m
Market cap: £275.0m
Trading update - for the 31 Dec 2015 full year.
I do like it when companies put a simple first paragraph giving the key conclusion - performance against market expectations, which is what Restore has done today, so thank you for that - to the company and its advisers. All companies should follow this approach please.
Restore plc, the UK office services provider ("Restore" or "the Group"), confirms that trading for the year ended 31 December 2015 was in line with expectations.
This approach is very considerate, and shows understanding that investors have a one hour window between 7-8am, when we're still cranking our brains into action after usually not enough sleep, to absorb maybe 10-20 different company announcements, and form a view on which (if any) we need to take buy or sell action on.
Therefore a key conclusion at the start, allows us to check it, then move on, and revisit the detail below at our leisure.
There should of course also be outlook comments either at the start, or the end of the announcement (not buried in the detail, in the middle).
Outlook - a fairly generic positive-sounding comment, but reminding us that visibility of earnings is good, because a lot of business they do is on recurring revenue contracts;
"We are pleased by another year of good performance by the Group, with significant increases in revenue, profits and earnings per share. As expected at the time of acquisition, several acquired businesses have required substantial restructuring and these are now showing a marked improvement in profitability under our ownership. We continue to strengthen our position as a key supplier of services to UK offices and we have an excellent platform for further profitable growth with strong visibility of earnings."
My opinion - this company looks quite good, but I'm not keen on groups which grow by acquisition, hence creating an appearance of growth, but all too often funded by increasing debt.
It's on 19.3 times forecast 2015 earnings, which considering it has some (but not excessive, last time I checked) debt, looks on the pricey side.
It's not for me - the price looks too high in my view, although that's probably because the market is factoring in improved profitability at acquired companies (as noted above), and rewarding a company that appears to be well managed, and making sensible acquisitions.

XLMedia (LON:XLM)
Strategic review - the company is basically saying that it's fed up with its low valuation, and points out that it has performed well;
Since the Company's initial public offering in March 2014, the Company has consistently reported strong financial performance, continually invested in organic growth opportunities, completed several successful earnings enhancing acquisitions and declared $21.25 million in dividends to shareholders. Notwithstanding this and the Company's financial strength, the directors of the Company (the "Board") have determined it is appropriate to evaluate opportunities to maximise value for the Company's shareholders.
So today's announcement flags up that anyone interested in either buying the company, or coming up with merger proposals, should get in touch with Canaccord.
My opinion - this is all very well, but it's no wonder the market ascribes a low valuation to XL Media, because (a) it's Israeli and on AIM, and (b) the company is not transparent about where its profits come from!
So it's hardly surprising that investors don't trust it, as we've been burned so many times before in situations like this.
I have to understand a business model, and verify it, to invest in a company. In this case the profits seem to come from promotional websites which drive paying customers to other companies. Great. Let's have some examples then - what have they got to hide? Something doesn't smell right here to me. I think the figures are real, but possibly not sustainable. We need more transparency from the company please, on where specifically its profits come from - website names, and amounts, so we can check them out.
Microgen (LON:MCGN)
(at the time of writing, I hold a long position in this share)
Trading update - an in line update for 2015;
Trading in the final months of the year continued satisfactorily and Microgen anticipates reporting results in line with Board expectations
Net cash is £5.4m
This business has historically been an absolute cash cow - paying out bumper special divis, from memory. It's a while since I last looked at this company, and as I am rushing for a train this morning (a day of meetings in London), will have to come back to it at another time. All looks fine in this update though, so that's good.
Carpetright (LON:CPR)
After many years of being seriously over-valued, the valuation is finally coming down to earth, and is actually starting to look quite sensible now.
This one may be worth a look - it fell today, but the update showed sales in Jan 2016 returning to good growth after wobbles in Dec. Margins were down, due to promotional activity. I'll come back to this one when time permits.
1pm (LON:OPM)
Interim figures look good today - strong growth in profits.
This company has been successfully plugging the gap left by the banks in SME lending.
Am not sure this is the right time of the cycle to be buying into a company like this - if we do see a recession, then its bad debts are likely to rise.
Overall, I'd be reluctant to get involved in this, unless & until the macro clouds have lifted. Remember that profits quickly turn to losses at lenders like this, if a recession bites. Banks shares are in freefall at the moment, as mentioned in the preamble above, so that makes me worry that credit conditions are getting worse, not better. Whether that filters down to SMEs, who knows? I'd say it's likely to, but perhaps after a time lag?
I know the company has personal guarantees, etc, from borrowers - but those are often unenforceable when people's small businesses go bust, as entrepreneurs have already sunk all their assets into the business, and the courts might block any enforcement of a PG if it would involve making a family homeless.
If the economy remains sound, then 1PM is likely to continue growing, and reporting better profits. So if you're sanguine about the outlook, then this could be a nice company to own perhaps?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Re XLMedia (LON:XLM) I saw this recommended back in 2014 but decided not to take it any further when I couldn't find a single example of their work.
Just realised that the clue, which accounts for part of the answer, to my initial question in my previous post is in the name...... duh...... :(
Thank you Paul for your always interesting opinions on the various stocks you look into.
As a relative newcomer and subscriber to your newsletter, I'm interested in how you sort out the shares which you actually look into, from the few thousand available. I guess that you look at approx 500-1000 shares, every year (250days x ~3/day) out of all those which you could consider evaluating.
As a Chart person I've only recently looked over the fence at the 'dark side' :). I personally don't think it's a good idea to buy a share which is in downtrend, such as trakm8 is in at the moment.... albeit a short term one; so far. Better to draw an alarm line over the peaks of the downtrend and wait for the price chart to move through that line, before parting with your money IMHO. There's been quite a bit of trading volume in the last week or two, so something may happen quite soon.
Finally,as a newbie, I don't understand why the StockRank momentum for trakm8 is 90 when the price has been dropping since the middle of December! Perhaps the calc just averages over the year. Perhaps it would be more helpful if the Momentum calc gave more weight to recent events, rather like an exponential moving average.
regards
Frank
Hi Frank,
Here is my personal filter for stocks to make a manageable universe, which for me is c.500 UK stocks (this is as of Nov 2015, so prob needs updating)
This is on my website, but buried in the detail:
Morning Frank. Welcome over the TA fence!
I think your comments on Trakm8 Holdings (LON:TRAK) illustrate one of the issues of looking at charts in isolation, i.e. away from following some of the underlying commentary and events in the market. This particular stock announced a proposed placement and relatively small acquisition in December. There was then some confusion as to whether this had taken place absent a follow up RNS, compounded by some profit taking in the general market fall at the start of Jan. There has since been a bear raid led by a blog poster on another site criticising both the acquisition and casting aspersions about the underlying financials of Trakm8 Holdings (LON:TRAK) which in turn led to Paul S. doing an interview with company management to address these issues.
As you can see, quite a lot going on and probably more to come which will probably be magnified given the smallish size of the company share float. Not sure a chart in and of itself necessarily captures all this, although it does at least provide a record of the impact on the share price evolution.
Gus.
Should one take a long or short position if one wishes not to bet against him? Do you know if he will use his shrewd operator skills to short change minority shareholders, or will he be nice to them?
Hey Paul
Interview with XLM would be fantastic. Lot of people with a lot of interest in this company. Get them on and let's put the investor communities questions to them. I also notice they are presenting at the Innovators & Investors forum on Feb 2nd. Wish I could be there. Always good to meet face to face with top brass at these events. I personally think Ori Weihs and XLM will surprise to the upside out of all of this. Ori is a shrewd operator. I wouldn't bet against him
cig 13 - thanks very much for that hel[pful advice
Re demise of oil and gas.
47% of UK power stations are run on natural gas so unless there is a big change the electric cars will still be part powered by fossil fuels. http://www.energy-uk.org.uk/energy-industry/electricity-generation.html And electric cars powered by gas derived electricity waste a huge amount of power in the generation process so petrol cars are actually more efficient.
And there are other demands in the pipeline ie a huge forecast increase in the use of plastics - plastic could consume 20% of current oil use by 2050 if its use isnt curbed (due to really bad effects on the oceans ):http://www.iflscience.com/environment/plastic-ocea...
I'm going to run out of envelopes, but 60% efficiency for a state of art combined cycle gas power plant, 15% transmission loss, and a 60% efficient electric car still gives you 30% full-cycle efficiency which beats handsomely a 20% efficient petrol car.
Is anyone arguing for the demise of the natural gas industry? Oil can become the next coal while gas prospers -- indeed it's a complementary argument: known reserves and the oil found on gas projects might be all the oil we need for the foreseeable future.
You need to add in charging losses. Tesla owners report warm garages while charging.
Paul, Re XLMedia (LON:XLM), why don't you organise a call with the CEO? I'm sure there are a lot of people who would contribute questions, and would benefit from understanding the business in more detail.
Hi webclick,
Why don't you organise a call with the CEO of XLMedia (LON:XLM) ?
I would be very interested to hear what he has to say.
Regards, Paul.
Re XLMedia (LON:XLM) - I note that unlike the Chinese stocks the "insider" VC's still hold just over 50% rather than dumping stock into a falling price and the CEO still holds around 5%. Meanwhile some fairly well respected Small cap managers like Slater Investments and Hargreave Hale hold 4% stakes, while River & Mercantile & Investec hold around 5% each. The only other declarable holder was an outfit called Inflection Point Investments, LLP who held just over 3% but have recently declared due to going under 3%. So presumably they'll all be looking for them to deliver shareholder value. Nomad is Cenkos - not the worst AIM adviser? Guess it will be interesting to see what, if anything comes out of this strategic review - but looks like they might want to sell out if they can.
Re Oil Industry demise by 2030!
I haven't watched the Stanford lecturer but I suspect these academics need to get out of the ivory towers a bit more! Electric Vehicles and theire ongoing development will certainly replace a significant portion of petrol and diesel over the next 15 years but as other people have commented there are a lot of 'legacy' issues out there (e.g 1-1.6 bn ICE and supporting infrastructure, etc.) which will need addressing and replacing with EV infrastructure. There is also the small matter of other forms of transportation and their fuel uses - will we have electric/battery powered airliners and nuclear (fisson!) powered military jets/drones or a totally nuclear powered shipping fleet (commercial and military) by 2030 - I think not. Renewables might really take off if battery storage develops sufficiently but there just won't be enough Wind, Solar, Hydo, tidal energy to meet the world's demand and as the UK government has demonstrated it will take decades and huge cost to implement a nuclear based energy environment. Consequently the world will still need plenty of natural gas. Then there are all the other chemicals and products that we use in our every day lives which are derived form crude oil or gas. It will take decades , not 15 years, for the global economy to change to such an extent that there is zero need for oil and gas. The oil and gas industry will change significantly by 2030 but it will still be here in some shape or form - unless the world isn't!
Paul, I don't know if you saw Avon Rubber (LON:AVON) issued a trading update today which did not go down very well, shares are down 16%, if you have a chance would appreciate your views.
Trading statement for Avon Rubber (LON:AVON) was a bit downbeat and seemed to reflect a great deal of uncertainty about near & medium term order prospects in key division for profitability. Also dairy industry continues to be difficult - no doubt courtesy of supermarket prices for milk and the knock on effect on dairy farming and their supply chain. On the other hand could this be the newish CEO lowering expectations so that things look good when results reported! I fear unless there is some upturn tomorrow I will be a seller to at least realise some of the profit on this holding. As herbie47 says would be interesting to hear Paul's views
Like rhomboid1, I have a holding in Restore. Bought at 146p in October 2013. Currently at 290p. So happy.
I viewed their recent acquisitions as an opportunity to strip out costs, obviously Wincanton were not making much of a return. The "sheds" acquired will be revenue generating from day 1 -assuming they are largely full of document boxes. The alternative for Restore would be to build new sheds- takes time to build and fill up with boxes!
Let's hope they get it right.
I also own LOK and SAFE. Why? I did some work many years ago for an American version of these companies. Basically, the revenues just roll in as companies fail to destroy old records, so just keep paying! Even if they do destroy, these companies earn money from their destruction activities.
I can also understand the business model
Hi Paul, I found the interview with the Exec Chairman of Trakm8 somewhat stilted. He didn't seem to have the relaxed aura about him as that which came across in the video presentation in the last Q4 period, having said that though he came across as professional and I continue to have confidence in the coy but glad i have (rightly wrongly) reduced my position until the dust has settled. TW seems to have a large following of what I regard as short term investors and can see the market dragging them further down before stableising.
1PM, afraid I don't subscribe to your views Paul, I am very positive about the future of the "second stream" lending business. Being an ex banker my experience is that an SME is a much safer risk than their larger counterparts and also I don't see the UK sinking into recession in the foreseeable future. On the strength of this mornings report I may well add to my holding. Money lending is one business where you are earning 24/7/365, great business to be in! Take a look at Burford Capital, another specialist lender!
Thank you, Paul, for the link to the Paul Seba video. It is the most thought-provoking hour that I have spent for a long time. I suggest it is essential viewing for all investors, as the points he make are relevant far beyond the confines of his specific examples.
Paul, Thanks for the link to the excellent TRAK interview; it provided a fairly balanced view of the company and the CEO clearly has a total handle on the Company the business & the competition. Certainly going on my Watch list. Thanks also for the obvious amount of effort required from you to provide it.
I too hold Marstons, what is impressive is the way they are moving from wet led pubs to casual dining with a marked improvement in margins. The new establishments are also creating an immediate unrecognised valuation gain on completion of iirc £100k per site. So in essence not only are earnings growing but the quality of earnings is improving and the Balance Sheet getting stronger. Debt is high but goes with the business model in a way that is seldom the case.
I have a core holding in RST which was initially bought to my attention when Charkes Skinner took over. He is a top guy and increased shareholder value substantially at Brandon Hire if anyone can remember those days. So I bought in on 19/1/2012 at 80p and have held since.
Listening to David Stredder on Share Radio I know he is a great believer in investing in the management team as well as the business. This is a case in point .....whilst Paul I know you are not a fan of growing by acquisition, this is something that Charles seems to excel in.
Finally I have to say I am saddened and disgusted by some of the commentary on ADVFN re TRAK and Paul thanks for all your hard work. One thing that would really help me (as I spend a lot of time in the car) would be if I could download these recordings to my mobile. Maybe I have just not worked it out, so if anyone can elighten me I would be grateful.
You can download the mp3 files of the interviews from Paul's site:
http://qualitysmallcaps.co.uk/wp-content/uploads/2016/01/2016-01-25-TRAK-Pt-1.mp3
http://qualitysmallcaps.co.uk/wp-content/uploads/2016/01/2016-01-25-TRAK-Pt-2.mp3
I found the URLs looking at the debug view of the audio player widget (right click, "Inspect Element" in Firefox).
Cheers to Paul for doing the interviews! It's almost as good as meeting management ourselves, without the hassle and personal relationship biases risk!
on Oil price, everything suggests that the price decline is more SUPPLY driven and not wholly DEMAND driven. If it was mainly demand then indeed there are grounds for concern and calls for recession. If it is more supply driven then it is a big discount on input costs which is ultimately a good thing
some data to inform opinion on supply/demand dynamics in oil
https://www.eia.gov/forecasts/steo/report/global_oil.cfm
The views on this thread are probably a good microcosm for market behaviour ATM. Hysterical swings based on oil price fluctuation
On EVs no doubt they are the future with the right infrastructure build out etc; There are around 1 million EVs on the planet : there are various estimates on ICE vehicles but it is north of 1 billion and may be 1.6 billion. Much as I love disruptive technology, i reckon oil will be around for bit longer especially in the emerging economies
again on data as a DYOR take a look at BPs 2035 outlook
http://www.bp.com/en/global/corporate/energy-economics/energy-outlook-2035.html
price dislocations always bring opportunities.
I hold some Microgen (LON:MCGN).
The trading statement shows that they generated in the region of £6.2m or 10.5p/share FCF excluding the acquisition consideration which given how stable their cashflows have been in the past strongly underpins the current share price.
Historically they have struggled to find opportunities to re-invest those cashflows at their current levels of ROIC to drive growth hence the large returns of cash to shareholders. The upside potential comes if they can find those opportunities.
Meanwhile in a parallel universe...
Great numbers from Marston's this morning with more outlets being rolled out this year. I think the effect of the living wage is being overplayed and this is one of my favourite shares at the moment - good management and nice 4.5% dividend. What's not to like?
All the best, Si
Hi Simoan, I'm long of Marston's (LON:MARS) and think they offer decent value, the results looked good this morning, especially the 21% volume increase in own-brewed beer, no doubt helped by the Thwaites acquisition, and a great christmas performance, especially so given the awful weather in much of the country over the period.
I think the share price has under-performed the market - I'm a happy holder and as you say, a great yield. Debt is a little on the high side, their balance sheet is not as robust as say Fuller Smith & Turner (LON:FSTA) (I've held them for many years, expensive but a great company), but if they make more from the new openings than the cost of debt, then it's worthwhile.
And remembering Paul's comments recently about retail / consumer stocks benefiting from the low oil price and associated reduction in household costs, I think Marston's (LON:MARS) is exactly the kind of share to do well.
Hi Cisk,
Agree the debt is a little higher than I would like but then no share is ever perfect! I have quite a large position (for me) and it's not one I lose any sleep over. I am happy to hold the kind of shares that benefit from extra cash in consumers pockets due to cheaper petrol prices, and who knows, even from the the living wage in due course.
Overall, I believe the net effect of the latter will not be as bad as people are making out on the profit margins of a well run pub group like Marston's. Even if you ignore the macro stuff, it has good management who are continuing to grow the company (as evidenced by today's Trading Update) whilst providing a nicely covered 4.5% dividend yield on a PER of 12-13.
All the best, Si
Interesting article in the Telegraph yesterday re: oil http://www.telegraph.co.uk/finance/oilprices/12120946/Opec-pleads-for-Russian-alliance-to-smash-oil-speculators.html
Two main points jumped out at me:
1. Margin between current production and peak capacity is thin, so it would take only a small increase in demand before significant investment would be required to increase production further
2. Shale producers have been supported by hedges that are beginning to expire, possibly leading to a squeeze.
A lot of things going on that might push the price lower, or higher, and who knows how quickly it might happen.
yes JE I was think that the other day RBS may have got it right with their comments. many alike was hoping it was just a correction in the market, but things are looking a lot more serious.
at the heart of the collapse of oil price has been a slowdown of demand. so to get a real bottom in oil prices we need to take production out of the market. That’s an nice way of saying that oil companies have to go away. There has to be massive liquidation. For that, the oil price doesn’t have to go any lower. It doesn’t need to go to $20 or $15. If in June/July the oil price is at $35 it will be still too low for most of these companies and it will do the damage. It needs to get into the high forties for the industry to have a chance to survive. At this point this means it has to go up almost 70%. For that to happen and the market to be saved the measures need to be put in place so it can take its course. The likelihood of that happning is another thing, some may even say (RBS) its going to be a miracle any time soon
I've been pessimistic for the last few weeks and have to say I'm getting more so. Your point about the banks dragging the market down is a powerful one. Also gold and US treasuries are rising as investors look for shelter. I did think the market was having a big temper tantrum about the Fed taking the free money away but this seems a bit more serious now. It could be that the folks at RBS called this one correctly.
Morning Paul. If only there was a way to ship some of those 65m empty homes to the UK/London it could be very mutually beneficial!
I listened to the TRAK interviews last night (I don't hold a position). I have to say I prefer the more free flowing interviews you've done previously but understand the format change for this occasion due to the circumstances. By the end some of the questions seemed a little exhausted as they had mainly been answered and asking the company anything about their SP was unnecessary as they were never going to comment and also highlights perhaps why companies don't engage with PI's in the first place as this short term mentality serves very little purpose as the market is a weighing machine long term.......etc etc etc.
I felt they were on edge with the RM acquisition and pretty much admitted they weren't likely to recoup most of the debtors. It does seem like they could have structured a better deal and it will be interesting to see if they are liable for the additional payments next year.
On balance it's not one I'm going to add at the moment but is on the watchlist and thanks for taking this time to prepare the interview so everyone can form there own opinion.
Morning Paul, first of all always a pleasure to read your posts which I enjoy.
The declines now have followed a two-day rally last week as crude oil prices fell as much as 5% following an announcement from Iraq about record-high oil production that will feed into an already oversupplied market, wiping out much of the oil price gains from of the biggest-ever daily rallies on Friday.
We are going to be able to see the direction of stocks when you see where oil is trading. Will be interesting to see what the Federal Reserve do this week, whether that helps calm markets or not.