Small Cap Value Report (26 Jun 2015) - TNI, TUNG, ESS, SGI, SAL

Good morning!
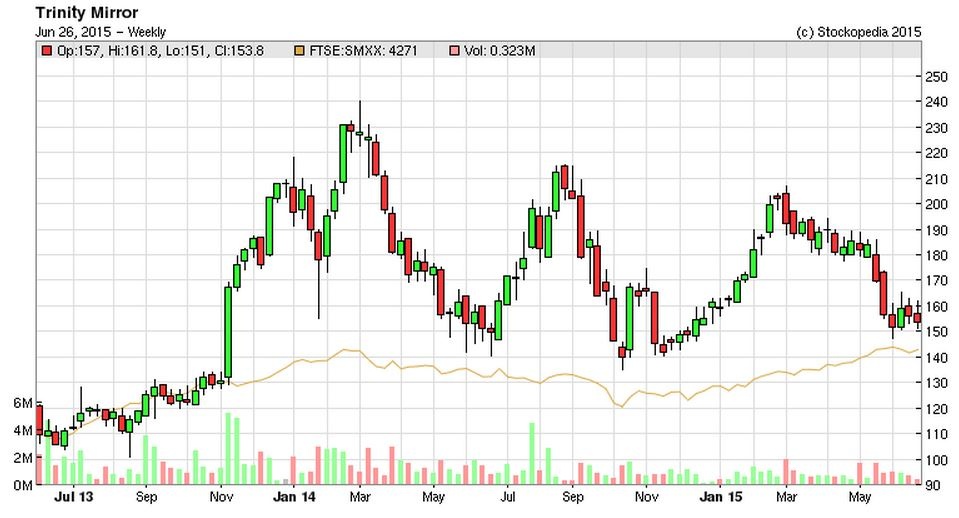
Trinity Mirror (LON:TNI)
Share price: 154p (down 3.3% today)
No. shares: 257.7m
Market Cap: £396.9m
Trading update - this covers H1, the 26 weeks to 28 Jun 2015.
The revenue trend seems very poor to me. Revenue for H1 is expected to fall by 11%, with what they call underlying revenue (i.e. like for like) down 9%.
More strikingly, print advertising revenue is down a colossal 19% in the period. To my mind this clearly demonstrates that advertisers are reallocating budgets to other forms of advertising, especially online, social media, etc.
Once again TNI has been able to mitigate the drooping top line with yet more structural cost cutting, targetted at £20m for this year, up from £10m announced in Mar 2015. This is continuing the same pattern of cost reductions to maintain profits, which has been happening for years now.
Although cost cutting also comes at a cost - £15m restructuring charges are expected.
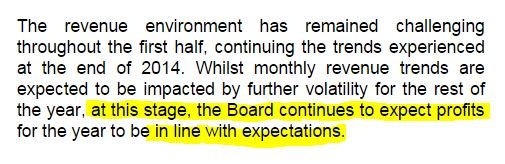
On profitability, they're sticking with full year expectations (for now - note the "at this stage" qualification);
Phone hacking - a potentially very serious issue, in my view. There's no new info today on this, with the company confirming that "there remains uncertainty as to how matters will progress". I suggest the news is more likely to be bad, than good - because there is already information in the public domain that TNI were heavily involved in phone hacking, and that management very much tried to cover up this issue in the past. So costs are likely to mount, in my view.
Valuation - the bizarre thing with TNI is that, whilst most people accept that the business is in terminal decline, it's still generating astonishing amounts of cash. It's very difficult to think of any other industry which is dying out due to technological & fashion changes, yet is still churning out huge profits.
The big question is, how long can this continue? Valuing a dying company on a PER basis is clearly meaningless, and the current year PER of 4.9 reflects the probably short life remaining for this business, in its current form anyway.
I think it can only really be valued as a special situation, effectively on a winding up - how much cash will it generate before the business has to be shut down? Is there any residual value in the digital businesses, once the newspapers close? Or, if you're an optimist, could some newspapers continue on a free to customers basis, as the Evening Standard & Metro seem to have successfully done?
Then there are the assets and liabilities to consider. The pension scheme here is huge, and will probably consume a lot of the remaining cashflow that the business generates in its last handful of years. However, TNI also has some valuable freehold property assets - so it might end up becoming a property company once the papers have shut down?
Dividends have recently resumed, but only 5p is forecast for this year, so a yield of only 3.1% is nowhere near enough to get me interested. I think this share would only make sense as a last puff of the cigar butt, if the yield was >10%.
My opinion - I loved this share in 2012, at 25p per share, when it was my best investment of the year. However, at 154p there is no appeal in my view. True, the debt has been cleared (as I correctly predicted), from the amazing cashflows of the last few years, but at some stage (certainly under 5 years, in my view), profits & cashflow are likely to really tank. I think we could be near to that tipping point, as the 19% reduction in print advertising revenue should be setting alarm bells ringing with investors here - that's not a steady decline, it's plummeting - suggesting that a major structural change in advertiser behaviour is occurring.
So a big thumbs down from me - this looks a value trap, in my opinion - revenues are now declining too fast to hold out much hope of a decent shareholder return.
Tungsten (LON:TUNG)
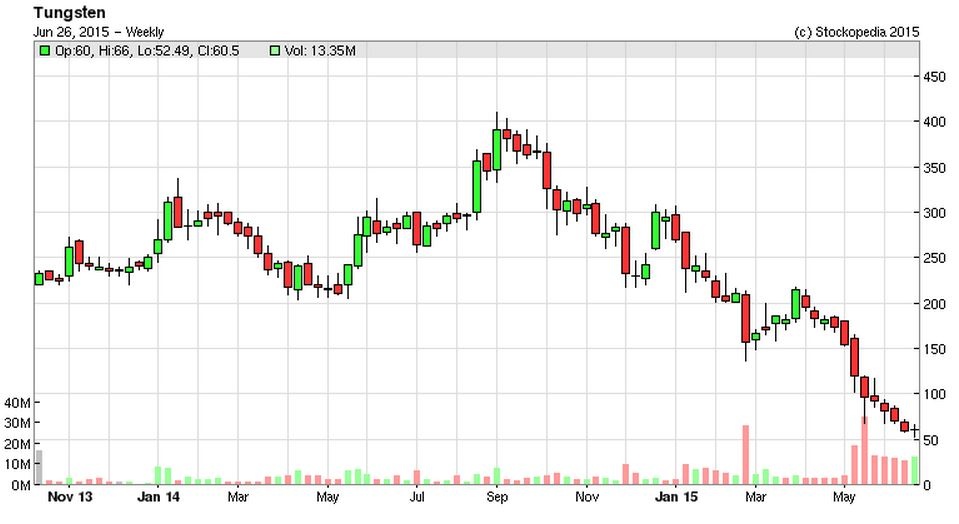
Share price: 61.5p (up 8.4%)
No. shares: 125.4m
Market Cap: £77.1m
Buyout speculation - there's an article in the FT today, suggesting the Edi Truell might take Tungsten private. It's possible, but that would be such a kick in the teeth to all the people who bought into the heavily ramped (by Truell himself!) story at much higher prices.
After all the big talk, that lured in many investors, including me (until I realised that I'd made a mistake, and reversed my view of the shares in Jan/Feb 2015, and was on the receiving end of some misguided abuse I might add), Truell's execution so far at Tungsten has been appalling, incompetent even - cash burn far higher than expected, several more fundraisings (the last one at a distressed level), and the original targets for profitability were missed by a mile, yet as usual PIs were the last to find out.
So a very unhappy tale, which has justifiably seriously damaged his reputation. This puts me in mind of my favourite quote from Bill Gates;
"Success is a lousy teacher. It seduces smart people into thinking they can't lose."
What happens to Tungsten then? Who knows? Perhaps Truell will take it private, but at what price? There would have to be a premium to the current price to persuade people to sell, but would long term investors be happy to sell out below their original purchase price?
Or, if you're more sceptical, you might think that putting out a rumour of a buyout might be a good way to trigger a short squeeze!
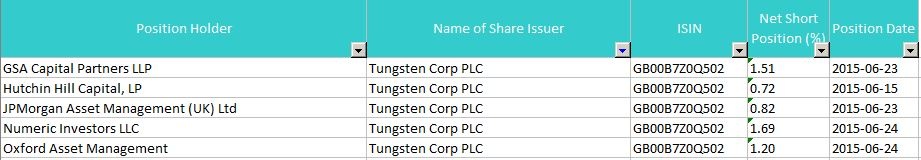
Here is the latest data from the FCA website on disclosed short positions in TUNG, which total up to 5.94% of the whole company:
My opinion - I got this one wrong originally, and hence have no plans to revisit it, either as a long or a short position.
In my view this is yet another example of how the stock market is just not suitable for early stage, speculative growth companies. The problem is this - the stock market swings from wild optimism to great pessimism - Ben Graham's famous analogy springs to mind.
So if a speculative, cash burning company like Tungsten, or on a smaller scale Synety, runs of cash at a time when the market is depressed, then it is in a full-on crisis. Often, to get a fundraising away, the price has to be a deep discount - half or less the prevailing share price before the market woke up to the reality that more cash was needed.
Therefore in my view, speculative shares should only be floated on the stock market if they raise enough cash up-front to reach breakeven, with a large contingency reserve on top, for the inevitable cost over-runs, and delays that always happen.
Poor execution, and not raising enough cash, scuppered the big story at Tungsten - plus I think also a realisation that what they are doing is not unique at all, other companies are doing the same thing.
Tungsten might yet succeed, but as I mentioned in a previous blog here, in my view the company needs to raise A LOT more money, maybe £100m, to really go for it, in terms of hoovering up market share.
It never should have been floated, the stock market is the wrong place for it. High growth, heavy cash burning companies should be privately owned, by entrepreneurs, VCs, etc. They should only be floated once they are past the cash burning stage, in my view.
I should add that I'm sorry if any readers lost money on TUNG and were influenced by my previous bullishness on the company. As a general rule, just ignore me when I write about speculative companies, as most of them will go wrong.
As this is a Value/GARP focussed column, I'm trying not to include any speculative companies now, or at least not completely blue sky stuff, as they nearly always go wrong - blue sky investing is a complete mug's game, except when you're in a roaring bull market & you can catch a speculative wave - but that's trading, not investing.
The other lesson is - listen to the shorters! It may be unpleasant to read negative opinions on a share you own, but it's absolutely vital to understand the negative case, as well as the positive one. People who close their minds to downside risk usually end up paying a heavy price for that stupidity.
Investing has to be rational to succeed - the moment we fall in love with a share, and think about it emotionally, we're half way to a disastrous loss. I'm very much talking from extensive personal experience on this point! Fighting those emotional responses is probably the single biggest key to better investing, in my experience - as very often your emotions will be telling you to do the exact opposite of what you should be doing.
Essenden (LON:ESS)
Share price: 80p
No. shares: 50.1m
Market Cap: £40.1m
(at the time of writing, I hold shares in this company)
Recommended cash offer at 80p - what a let down! In my view this 80p bid for the company is a complete stitch-up. It follows a pattern I'm afraid, of an aggressive major shareholder (Harwood Capital) bullying management into submission, then taking the company private at a derisory price, pocketing the upside for themselves.
Essenden has been a terrific turnaround, and there's no reason at all why it cannot continue as a successful listed company. This bid is all about self-interest for the bidders, who are nicking the upside from existing shareholders, in my view.
I'll certainly be voting against the proposal. Trouble is, the institutions will probably accept it, as they don't have any liquidity - so getting out cleanly with a cash payment, might be seen positively by them.
The take out price is far too low - a forward PER of only 11. Management should not have recommended this bid, and have failed in their duty to shareholders, in my view. The exit price should have been 120p+ to be considered a fair price, in my view.
I've noticed that Harwood are very good stock pickers, they're in some very good, undervalued micro caps. However, their modus operandi seems to involve making opportunistic, under-priced bids, thus capping the upside for other shareholders.
Stanley Gibbons (LON:SGI)
Share price: 255p (up 2.2% today)
No. shares: 46.8m
Market Cap: £119.3m
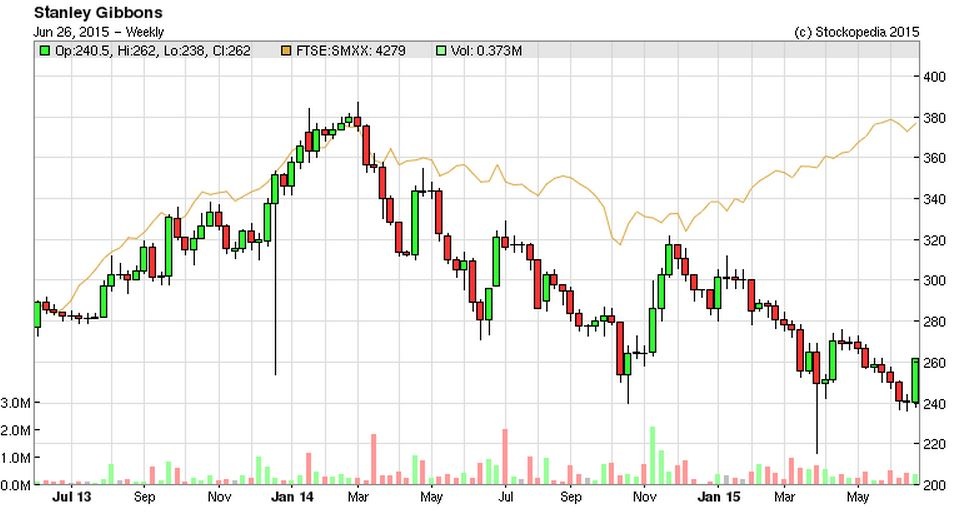
Results for y/e 31 Mar 2015 - these results look potentially interesting, although they're not the easiest to interpret as the prior period comparatives are 15 months, due to a change in year end.
Checking back in my notes here, my report on 2 Apr 2015 commented on the company's profit warning - triggered by several high value sales not completing by the year end. This emphasises that SGI is vulnerable to large individual sales.
Adjusted EPS of 12.9p for y/e 31 Mar 2015 has come in way below pre-profit warning forecasts of 20.2p, but bang on more recent forecast of 12.9p. So the historic PER drops out at a rather high 19.8.
Outlook - it's obviously more important to look at what EPS & cashflows the group is likely to generate in future. SGI has made two recent acquisitions, so that should push up future earnings. Also it makes interesting noises about its new online marketplace, which could be a catalyst for the shares to re-rate. I can see the attractions of a SG-branded ecommerce site for collectibles, rather than taking the risk of unknown Ebay sellers.
EPS of 17.0p is forecast for this year, which equates to a PER of 15, which looks about right.
Balance sheet - this looks in good shape, and as you would expect, is dominated by the inventories balance of £53.8m. The company says there is additional value over this figure, as stock is stated at cost, but has significant unrealised profit potential.
The current ratio is great, at 2.96, with a surplus of £49.8m in cash terms (i.e. that is the amouny by which current assets exceed current liabilities).
Long-term creditors are not excessive, at £17.2m, which is mostly £9.2m bank debt, and a £5.8m pension deficit.
So overall, I'm very happy with this balance sheet, it looks fine.
My opinion - I'm in two minds about this. Conceptually, I find huge prices for stamps utterly ridiculous. The worry is that, at some point, collectors dwindle, and the prices collapse. But that process is not likely to happen overnight.
A PER of 15 for an established, profitable business, with a fantastic brand name that is known globally, and a growing internet presence, sounds potentially interesting.
It has a strong balance sheet too, which protects the downside, so overall I would say this one is worthy of further, more detailed research possibly.
Spaceandpeople (LON:SAL)
Share price: 78p (up 25% today)
No. shares: 19.5m
Market Cap: £15.2m
(at the time of writing, I hold a long position in this share)
Award of preferred bidder status - I don't normally comment on contract win announcements, unless they look material. Since this announcement came 25 mins before the market close, and moved the share price up 25% on the day, then it's worthy of a mention!
Although I have to mention the highly suspicious flurry of trades which began late morning today - quite obviously insider dealing, especially whoever paid 3p above the offer price of 65p, to acquire 17,627 shares at 68p, printed at 11:08 this morning. That person is quite obviously an insider dealer, and needs to be hauled in front of the Courts. Will the FCA do anything? Not a chance!
Really, what is the point in having insider dealing rules, if they are so widely flouted?! Someone was clearly in possession of price-sensitive information, and traded on that information. That is illegal, so they should be punished.
I seem to have spent the whole day on my high horse, getting wound up by bad things happening! So it was nice to end the day with a few extra £ profit (well, more like recouping previous losses) from the bullish sounding SAL announcement, which reads:
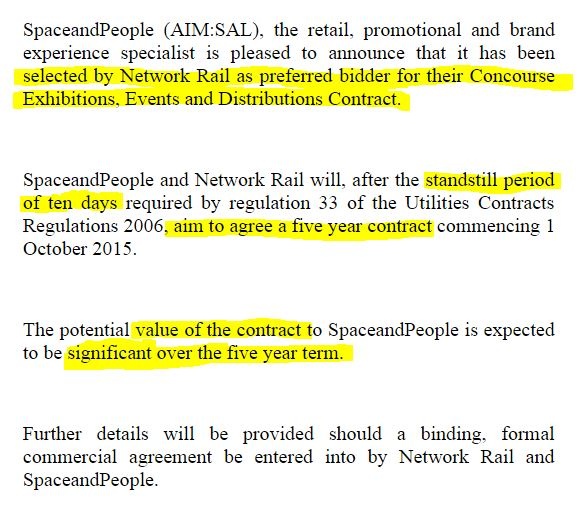
My opinion - I don't want to jinx it, as things are not formally signed yet, so let's wait to see what the outcome is. Of course, this sounds a potentially important deal.
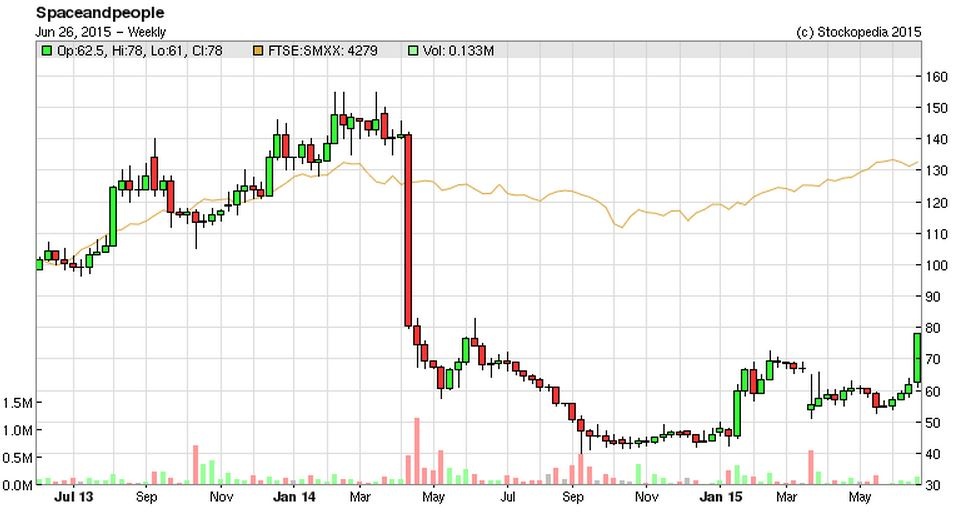
As I've maintained right through the profit warnings last year, this is a fundamentally good business, with entrepreneurial management, which just ran into a whole series of problems last year. They needed time to fix things, and it looks as if management are getting the business back on track, and I think potentially on to greater success, as there are other bullish things in the pipeline, e.g. the new mobile promotional kiosks beginning a roll out.
We're clawing back some of the losses from last year anyway.
It's worth noting that when everyone absolutely loathed this stock, late last year, would have been a great time to buy! Worth bearing in mind, that. It's the contrarians who catch the worms early, sometimes.
OK, I'll leave it there for today. No video today, as I covered everything I wanted to in the main report above. To recap on the two videos I've done earlier this week, please see my YouTube channel.
Have a smashing weekend & see you back here on Monday morning!
Regards, Paul.
(of the companies mentioned today, Paul has long positions in ESS and SAL, and no short positions. A fund management company with which Paul is associated may also hold positions in companies mentioned.
NB. Paul NEVER gives recommendations, or financial advice. This blog is his personal opinion only, and the emphasis is on readers to DYOR, and make your own investing decisions).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
Hi Paul,
Will appreciate your thoughts and that of other readers on the company: VOLVERE (Volvere Plc). Debt-free and trading close to cash held on the balance sheet, with a discount to book value per share of over 20%. Although, the PE seems quite high at 38, other performance metrics seem quite good.
Stockopedia seem to like it as it ranks 84. Also, some other analysis suggests it should be worth more than double its present price.
You have never commented on it before, hence will be great to hear your opinions and forensic balance sheet analysis on it.
Thanks for all the great work.
Kind Regards,
Sirsege
Hi Paul
I had a look at the Stanley Gibbons (LON:SGI) results this morning and they looked lacklustre to me. Whilst adjusted profits were in line with the revised broker forecasts, some of the exceptional costs which they've added back in are questionable ie. legal costs on defined pension scheme which occured in 2014 as well, acquisition costs, etc. They seem to be recurring costs so seem to be underlying costs of running the business and shouldn't be excluded.
Secondly the PER looks to high based on the organic growth of the business. For example recent acquisitions contributed just over half of underlying trading profits, and the performance exc. acquisitions was poor (profit here was £4.3m compared to £5.6m in 2014 - based on an annualised basis which represents a 30% reduction in profits). Therefore one could argue the underlying business shouldn't be valued on such a high multiple?
Thirdly whilst the balance sheet looks okay, trade receivables and trade payables increased quite significantly this year. They also wrote off £0.5m of trade receivables and given the level of inventories now equates to almost half of the market cap, this would make me slightly nervous if I was a holder.
The final point I would make is the poor level of cash generation of the business both in the cashflow statement and within the Stocko reports.I appreciate the business has been making acquisitions and investing in their website but their free cashflow per share has been negative for the previous 3 years. The full year dividend also looks to have been cut, as this was projected at 7.5p compared to the FY payout of 5p.
As a result, I'm surprised the SP went up this morning. Maybe I don't understand the business fully, but based on my understanding of the financials I think the current valuation looks toppy. I take the point on board that if they achieve EPS growth for the forthcoming year the PER could be reasonable but I have my doubts whether the company can unlock the potential of the business.
Hope this provides some additional points to your analysis above.
Best wishes,
Imran.
"It's very difficult to think of any other industry which is dying out due to technological & fashion changes, yet is still churning out huge profits.
Tobacco surely P?
Clientele are literally dying at the back end, with fewer new subscribers at the front end engaging in smoking due to fashion/health drive/societal pressure.
Paul thanks for that. I made the point that even the doyen of analyst/commentators can break their own investing rules. We all do it from time to time. I didn't know whether you still held Zanaga, but suspected you were out. As you say its little more than option money now. If you had asked the multi-billionaire who runs Glencore his view of iron ore prices, say 3-4 years ago, he would have no doubt been very positive. Still he had a more realistic view than the idiots who ran Anglo,RTZ and BHP who were all sacked. The amount of value destruction they were responsible for beggars belief but what do they care-made enough not to have to worry, One of them has even re-emerged from under a stone to become ceo of Vedanta a dubious Indian mining house. Keep up the good work.
Re Tungsten (LON:TUNG) I think it should be acknowledged that the shorters have done considerable damage to this company, I'm not saying management haven't made mistakes because they have but it's been depressing to see the old British disease of envy rear it's ugly head (as alluded to by bsharman above).
As for speculative companies on AIM what about this one?
This company IPO’d on AIM not more than 3 years ago.
It raised well in excess of £100m
It has management with a strong track record in business.
Director buying of shares has been heavy.
Institutions are keen with one particularly respected investor taking a big stake.
The company has big blue chip clients and its potential market is vast (it operates worldwide).
It is aiming to disrupt an existing market with a new and innovative product.
The underlying business is currently heavily loss making and has been since its inception several years ago.
The last reported loss was multiple 10’s of millions and it is not forecast to be profitable this year or next.
Cash burn is high.
In its last update to the market it indicated it would need more money to fund its expansion.
The company has strong cash balances of circa £50m and no debt.
No, I’m not talking about TUNG with a current Market cap of £72m but in fact the above comments all refer to RM2 International SA (LON:RM2) with a Market cap of £229m. I guess the difference is RM2 has not been targeted by shorters and the management are largely silent and keep RNSs to a minimum!
Webpax - re. RM2 International SA (LON:RM2) I remember studying their admission document last year and couldn't figure out why someone would pay upto 50% more to buy a plastic pallet (OK so it lasts longer) when the wooden varieties are perfectly fit for purpose, and you don't lose sleep if a few get nicked or go walkies from time to time. Besides there are thousands of wooden pallets and can be purchased second hand if cash strapped.
I have just glanced at the StockReport for this company. Revenues in 2014 just over £1m, market cap £224m. Ridiculous.
"I should add that I'm sorry if any readers lost money on TUNG and were influenced by my previous bullishness on the company. As a general rule, just ignore me when I write about speculative companies, as most of them will go wrong."
Thanks Paul. Actually I did invest a small part of my portfolio in Tungsten as a speculative punt at the end of last year, partly on the basis of your previous bullishness on it as well as some other people's bullish comments. But soon after I bought the shares, they started falling. I have a rule to use stop-losses on any new investments that I make, so I sold them quickly with a loss of about 15% of my small investment in them. If I'd held onto them, I would have lost a lot more than I did, so there was no great harm done. I look on it as an educational experience and as a warning to myself not to make speculative punts in the future! I will stick to using investment trusts and systematic investment directly in individual stocks using tools such as the StockRanks.
Please don't interpret this as a criticism of yourself - I think your Small Cap Value Reports are excellent and I have learn a great deal from them. The debates in the comments are also very educational.
I wouldn't read fundamentals in the Tungsten (LON:TUNG) price at the moment: the chart is a negative momentum algorithm magnet: it's basically a straight line trend on all the common timeframes (from September, so we've got monthly, 90 days and 6 months covered, as well as YTD), and at least half the shorts are algos. Add to that the humans who behave like algos (after all the momentum algos were modelled from manual traders' behaviour), that reinforce each other, plus the attention span of the original institutional investors (perhaps circa 2 years) and you have a perfect storm.
Not that I disagree with the criticism of Truell's errors (if with hindsight), but what we see in the price seems overdone. I also doubt he will take it private below IPO price, because it would be like a chess player kicking the board when they're losing.
(Happily long, though will be a bit miffed if there's a buyout at say 70p.)
Very interesting debate here. Why do people break the rules they set for themselves? Where is the review of Zanaga Iron Ore -a truly dire investment (news out today by the way). I think the reason is a mix of human nature and greed. Ultimately folks see a vision of themselves getting in at the bottom on say an ASOS and enjoying a comfortable retirement on the back of it. And as many others have pointed out we all like some fun speculative punting stocks. Mine at the moment is CPX. In holding it I'm breaking many of my personal investment criteria.
Hi hayashi22,
I didn't review Zanaga Iron Ore (LON:ZIOC) because it's no longer of any interest to me. I alerted readers ages ago to the fact that I'd sold out around 16-18p, because the price of iron ore was plummeting, which made it extremely unlikely that the project would succeed.
ZIOC is possibly of interest now, at sub-3p, as a call option on the project, and with the remaining cash in the bank, but I don't think it's the type of thing that is relevant to readers here now.
I wish I'd never written anything about ZIOC. However, if you look back to the circumstances at the time when I first flagged it, when iron ore was about c.$130/ton from memory, the Zanaga project was of enormous value, and had the backing of Glencore, who fully funded the feasibility study, costing $hundreds of millions. So it wasn't a daft idea at all, it was worth potentially billions at the time.
It didn't go ahead because the price of iron ore has collapsed to a point where it's not economic to do the huge capex needed on the project.
So I don't think people should beat themselves up too much over ZIOC. It was not a bad investment at a high iron ore price originally, quite the opposite. But the price has now dropped, thus undermining the economics of the project. So it's of little interest now, unless the price of iron ore shoots up again, but how likely is that with massive global over-supply?
Regards, Paul.
Paul, being on the receiving end of abuse (often very personal abuse) on bulletin boards when you've done your research properly but reached a conclusion that goes against the collective and wishful delusion is, unfortunately, par for the course. Not on Stockopedia, I hasten to add. I know from my own experience with Tungsten (LON:TUNG), Gulf Keystone Petroleum (LON:GKP), Quindell (LON:QPP) and others. Many so-called "investors" do little or no research and simply follow the madding crowd, preferring to believe in the tooth fairy They almost inevitably lose money but never seem to learn.
Tungsten (LON:TUNG) would have been far better off floating in the US, in my opinion. Culturally, American people like to back enterprise, success and vision whereas over here we are much more cynical and like to sneer at anyone who is perceived as successful - you just have to view the British papers, to see that this is true. It's amazing that markets across the world are so different and have a personality of their own based on many factors, including the culture of the country in which they reside. The US markets are full of speculative, high risk, loss making companies on high ratings. Twitter being an example. Perhaps someone (if they haven't already) should write a Phd thesis on how culture effects markets?
Paul re Harwood Capital further detail here;
http://www.harwoodcapital.co.uk/files/file/download/id/495
Major quoted holdings are NARS , Goals Soccer Centres , Coats, Bioquell , Innovation Group and Mecom
Hi Paul,
Wow, you're on form today! Love the Bill Gates quote, I'd not heard that before but it is so true. A lot of success is down to luck (right place, right time) and most people only get lucky once but still believe their own hype. Always enjoy reading the SCVR but your synopsis of Tungsten, and similar listed companies, is spot on IMHO. Why not just pretend they are Chinese companies :-)
All the best
Si
Paul, I gave you a thumb down by mistake, today's column is t'riffic as usual. I'm starting to use the bigger voting buttons at the bottom of the post to vote now, as I'm less likely to miss my target.
Ta
Chris
Paul when it comes to PE Ratios I am wary of anything above 20 but on the flip side below what level would alarm bells start ringing for you at 5,4,3 or below.
Thanks Andy