Small Cap Value Report (26 Mar 2014) - VLK, SSY

Good morning!
Vislink (LON:VLK)
As it's a core holding of mine, I'll spend a bit of time on calendar 2013 results from this technology group, announced this morning. They make high end video equipment, serving the broadcast and security markets. The shares shot up last week on a positive market reaction to the news of a decent size and quality acquisition, funded from cash and a new debt facility, plus a relatively small number of new shares issued, which I reported on here.
Stockopedia shows normalised EPS broker forecast consensus of 2.85p for calendar 2013. The company has today reported adjusted EPS of 4.2p. However before getting too excited, that figure is flattered by a favourable tax treatment this year. So the company also helpfully highlights adjusted EPS on a normalised tax charge, which is 3.2p.
So in my opinion the 3.2p adjusted EPS figure (normalised for 20% tax) is the most appropriate figure to value the company on. That puts the shares, at the current share price of 49p on a (now historic) PER of 15.3.
The historic PER is a good starting point, but investing is all about looking into the future, and valuing companies on how they are likely to perform in the future. Or rather I should say, it's all about buying/holding shares that are currently cheap against what you think future profits are likely to be. It's also all about being right on what future profits are likely to be!
In this case broker consensus is currently 4.05p normalised EPS for 2014, so at 49p the company is on a 2014 forecast PER of 12.1, which looks good value to me. There might be upside on that earnings figure too?
In terms of outlook, the narrative today reiterates the £80m turnover and £8m adjusted operating profit target, saying the group is "wholly in line with executing our strategy". Comments on markets & current trading say;
Our markets continue to be challenging. However, the Group enters 2014 with renewed confidence buoyed by the introduction of new products and the added momentum which has come from the synergistic 'bolt on' acquisitions.
So it sounds like growth is being generated by new products & the acquisition of Amplifier Technology, and more recently Pebble Beach, whilst still up against unfavourable market conditions. However, Western economies are improving, and I've heard from several company CEOs that the brakes are coming off their customers capex budgets, so hopefully market conditions for Vislink might also improve as 2014 progresses.
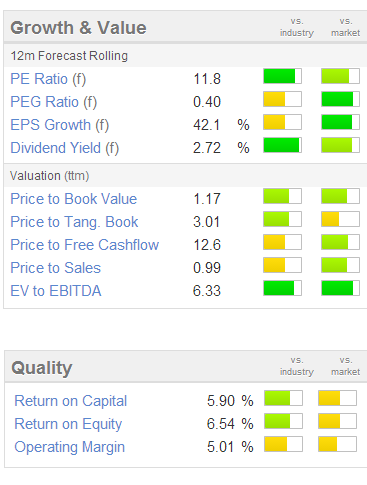 The dividend has been maintained at 1.25p, for a yield of 2.6%, which is a reasonably good payout for a smaller, growth company. As you can see from the usual Stockopedia graphics on the right, Vislink scores well on the main valuation measures.
The Balance Sheet is strong in my opinion, and passes my simple but effective testing. Although I note that cashflow has not been good in 2013, with both Debtors and Stock rising significantly, although both look to be reasonable given the size of the business. I am a bit disappointed to see cash drop back sharply from £8.1m to £3.7m, so with the recent acquisition post year-end the business now has net debt. That's fine with me, since I'd rather they put the surplus cash to use in growing the business, rather than pointlessly sitting on a large cash pile earning nothing in interest.
There is no pension fund, which is good.
To find out more, there is a results Webinar (i.e. an interactive, live results presentation online) today at 1pm, click here to sign up for that. I'm a big fan of Webinars, as it saves traipsing into London for meetings, and allows ordinary investors to get mostly the same information that Institutions and analysts receive on results day. So well done to Vislink for being private investor friendly in this way.
There is also a new commissioned research note on the company, published today, here. People are cynical about commissioned research, which is understandable to a certain extent. However all research has to be paid for somehow, and if someone is being paid to write a report, at least they have time to do it properly. I cannot see any difference at all between a commissioned research note, and a house broker note. Both are putting the bull case, and being paid to do so by the company. Also, I tend to ignore the target price & valuation, and instead just use these notes to gain a better understanding of a business, so they are very useful in my view.
Investor Evenings - reminder
There are two investor evenings today in London which unfortunately clash - organisers, please liaise with each other to ensure this doesn't happen, I would have loved to attend both, but can't be in two places at once.
ShareSoc (the UK individual shareholders association) is holding a seminar at FinnCap's offices, London from 4pm today, with the following companies presenting: Pressure Technologies, Cambria Automobiles, MoPowered, and ServicePower Technologies.
More details are here, there might still be some places available, I don't know.
Equity Development are running their quarterly seminar from 5pm today, near Oxford Circus, London, from 5pm, with the following companies presenting: W H Ireland, Deltex Medical Group, Ilika.
More details are here.
Organisers in both cases urge that anyone who has booked in should please let them know asap if you are not able to attend, as they often have a waiting list of people who would like to attend.
SCISYS (LON:SSY)
This is a niche electronics & software company, which operates primarily in supplying long term software & support to the public sector. I met management last year, and was quite impressed with the company, taking a view that the shares were unlikely to do anything spectacular, but might be a good slow burner in my long term portfolio, so I've held a few shares since then.
I haven't read all the blurb yet, but the headline results published today look quite good. Adjusted operating profit is up 19% to £3.2m, and adjusted EPS up 31% to 9.3p. Bear in mind the shares are only 83p to buy at the moment (up 4p on the day) that's a PER of only 9 - cheap in a bull market.
So it must be stuffed with debt & have a weak Balance Sheet then? Actually no. Net debt was £2.7m at 31 Dec 2013, which looks reasonable compared with profits.
The outlook sounds encouraging;
With encouragingly high levels of sales and operations activity seen in the final quarter of 2013 being maintained to date in 2014, and the benefits of a realigned cost base following last year's restructuring measures, the Group looks well positioned to deliver an improved financial performance in 2014.
The only slight fly in the ointment that I can see is that the restructuring charges of £1.2m were rather large. Although these were flagged last year, so it's not news. It just seems a lot to me, as from memory I think it was mainly redundancy costs.
The shares are very illiquid, and have a wide bid/offer spread, so it's not something I would invest heavily into, but I have bought a few more this morning. The company has been perceived by the market as being rather boring, so has not commanded a decent PER for some time, but with value now so hard to find in this market, perhaps investors will look at this again and think that it might deserve a rating of say 12 or 13, which I think is reasonable, given that the earnings are mostly quite good quality, some being of a recurring nature.
There have also been investor concerns over the impact of public spending cuts, given that Scisys supplies the public sector. I seem to recall management being quite bullish about the outlook for 2015 onwards when I met them last year, so must dig out my notes & refresh my memory in more detail.
As usual please be sure to do your own research, I haven't covered all the angles on this share by any means, the above is just my general impression, so I might well have missed something.
I'll try to update on a few more companies later this afternoon, but have to sign off now for lunch & the Vislink webinar.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in both VLK and SSY)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
SCISYS (£SSY) look interesting although I see that they claim to have "a strong balance sheet" and so I did wonder if Scott's law might come into play. However with all liabilities covered by current assets the company does look pretty solid.
However it's a bit disappointing not to see a breakdown of the exceptional costs so that we can judge whether they are truly exceptional or actually a recurring cost. Given that the eps without these costs is 9.3p, and so double the basic eps of 4.6p, this seems like a pretty material question. i.e. is the company cheap or not?
NB I've just looked at the interim results but there the exceptional cost was both broken down and only came to 248K for restructuring costs (218K in the previous year). So if the exceptional costs for the full year are just for restructuring then we're looking at an extra 950K in H2 and a good sign that they do recur.
Damian
Very true.
The only difference with Vislink is that the house broker (Singer N+1) doesn't seem to publish any publicly available research. There is no broker consensus recomendation on the Stockopedia stock sheet and the eps forecast has been stuck on 2.85 for nearly a year.
The Vislink website has a few Edison reports but little else.
Obviously the whole concept of the Stockopedia stocksheet forecasts relies upon brokers producing regular research and Stockopedia using this research to update the stocksheet accordingly. If this doesn't happen then the stocksheet is of very little use.
To add to SevenPillars' point , Petrofac, whilst not a smallcap and by no means a comparable company, made a similar forecast and repeated it in a number of consecutive Reports only to have to withdraw it on a downturn with a dramatic fall in the SP which is only just recovering after 5 months.
Hi Paul,
Any thoughts on the change in Vislink's way of reporting R&D. Seems like they are moving to capitalising a good part of their development costs - perhaps to flatter the results a little?
cycle,
I agree they have capitalised more than twice the amount they amortised this year which makes a significant difference to profits
Just a few points re Vislink. Nothing wrong with the results, but it does seem to me that they've made a rod for their own back with the 80/8 promise, by the end of the financial year 2014. The Chairman restates this today but leaves off the 2014 bit, which may be an oversight, but is a red flag in that it suggests they might know that the target date is now a stretch. They still seem some way off that unless they do it by acquisition. Will the market ignore it if it isn't achieved within the set time-frame? Who knows, but the share price might be higher if they had never mentioned it as a goal in the first place. Investors should ask how will they make that leap in the next year.
The dividend has been 1.25p for years, since 2007 in fact, nothing to write home about and looks like a token payout to keep investors interested, perhaps eventually it will go up once they hit 80/8?
It's a company I like, but I'd like to read more about how they expect to meet the goal it has set itself, when the numbers suggest that it is lagging behind meeting those goals, especially when in it's own statement it uses the word"challenging" markets. There is room for disappointment here.
The Vislink results were very good however I agree that what leaped out from the page was the fact that 2014 had mysteriously disappeared from the 80/8 target.... I think that this target is now very difficult to achieve in 2014. Delays will probably be due to finding the right businesses to purchase and at the right price. As a holder I wouldn't want them to make bad decisions at this stage just to meet a specified target. I'll be tuning in at 1pm!
See the followng link for 10 rules of forecasting and the perils of it, they obviously forgot Rule No. 6. - When forecasting give a number or a date but never both!
SP, I watched the Webinar at lunchtime and the 80/8 target by end of 2014 was repeated by their chairman. He was also confident of making it, which if they do would be a great achievement, but no one can foresee the future and even if they fall a little short it would still be a great result.
Well, good to have that feedback and I wouldn't disagree with what you are saying that even if they don't achieve it but get close it would still be a good result. The market however might think differently, which is unfair, but at times a failure to hit expectations will be punished. What is good about Vislink is that the fundamentals are not stretched, it isn't one of those growth/momentum companies on a P/E of 150 where the share price is one bad announcement from a 50%+ fall. Failing to meet 80/8 shouldn't cause too much damage unless between now and then the share price runs up on expectations which aren't met. We will know over the next 9 months or so.
One of the investment mags today reported that N+1 Singer have upgraded its VLK EPS forecast for 2014 by 8% to 3.9p and adjusted operating profit to 6.8M, . The chairman is reported as saying: “They’re the analyst’s forecast, not ours, We’re still on track financially, and have a group capable of growth well beyond the targets set out in 2011.". So do we believe the caution of the broker, or the optimism of the chairman?
Vislink's Chairman seems to be putting a lot of faith in making that great leap forward if the goal is still 80/8 by the end of this financial year. They've been saying that since 2011 and the numbers, while good have only been steady. Why's he so positive that they will leap up this year to hit the 80/8 goal? It may well be that a takeover or two will do it, but I would assume that may impact elsewhere as in the cash position or carrying debt, maybe even coming back to the market with a share placing? If they are just relying on the current business to jump up to 80/8 in the next year then that will take some doing based on recent results. The broker figures are still good, but the Chairman has to be optimistic as it was the company that set the goal.
I cannot see any difference at all between a commissioned research note, and a house broker note. Both are putting the bull case, and being paid to do so by the company.
Both sources are conflicted but I'd put more weight on an established brokers who have much bigger reputations to consider. I'm sure some Jonny-come-latelys will be willing to write unctuous froth to get the fee and develop their businesses. What we need is analystAdvisor.com, or perhaps a poll.
Paul,
I too hold Vislink (LON:VLK) and am +ve about the company. The 2014 forecast EPS of 4.05p was calculated before the Pebble acquisition, who in their last financial year (June 2013) made £1.3M PBT on sales of £5.6M. So assuming no synergy (which is unlikely), there should be a EPS upgrade from this acquisition alone and plus organic growth. I await new broker forecasts with interest which I expect will drop the the forward PE giving further scope for a SP lift.
Ian
Hi Paul,
Should/when they achieve their annualised target of £80m turnover and 10% operating margins, even with the dilutive effect of it issuing more shares for acquisitions, it seems to me that earnings in 2015 could be around 6.0p! Any thoughts?
Hi Paul
V minor point - dividend is being maintained at 1.25p, not 1.5p.
Garbetklb
Hi garbetklb,
It's an important point, thank you for pointing out my mistake.
I have now corrected the divi to 1.25p, and corrected the yield too. Important to get these things 100% right, so I'm always grateful when people point out any factual errors that slip through.
My apologies - just a slip of the keyboard, I had 1.25p written down on my pad here, but somehow typed it wrong. More caffeine required methinks!
Regards, Paul.