Small Cap Value Report (26 May 2016) - HSW, DEB, LRM

Good morning!
Ed is doing an interesting-sounding webinar today at 12:30 - signup link here. The topic today is different ways of using the StockRanks system to find good shares.
I see that Debenhams (LON:DEB) (in which I currently hold a long position) has appointed a new CEO. It's noteworthy because he's come from Amazon. So it shows how much emphasis retailers are now putting on online & mobile. Debenhams already has a very substantial online operation - it's actually one of the UK's largest internet retailers. It's funny the way the market ignores that, and puts it on a low earnings multiple, as if it were just a stores-only retailer.
Another stock I hold, Restaurant (LON:RTN) has still not said anything to the market about very specific potential takeover stories in the media. How can this be? Normally when a share price surges strongly, on rumours of takeover approaches, the company is obliged to make a statement to the market.
To date, RTN has said nothing. This seems most irregular. RTN shares are up 32% in the last 3 weeks, largely driven by takeover speculation. The company MUST make a statement, confirming or denying the situation. Also it needs to explain why there has been such a long delay in updating the market with price sensitive information that is currently being withheld - the rumours are either true or false. We need to know, now!
Hostelworld (LON:HSW)
Share price: 188p (down 27% today)
No. shares: 95.6m
Market cap: £179.7m
AGM statement (profit warning) - I haven't read it yet, but it must be a profit warning because the shares are down 27% - a typical drop for a standard-type profit warning.
A city friend asked me to look at this company, to give him a second opinion on it a few weeks ago. I've not written anything here about it before now. My view at the time was that the website looks good. The business is profitable & pays divis. However, growth seems to be stalling, and the group appears to be cannibalising sales from one of its own websites.
Anyway, on to today's statement. Q2 trading is not going well:
Reflecting recent geo-political events, particularly in Europe, trading over the second quarter has been at a level below our expectations...
...Overall, Group bookings are therefore marginally down compared to last year.
Doesn't sound too bad though.
Costs are being squeezed down:
...this will result in marketing investment as a percentage of net revenue coming in below the previous guidance of 45%-50% on a full year basis. We continue to see strong underlying cash conversion.
45-50% of revenue spent on marketing is gigantic! It reinforces my view that there are few barriers to entry for internet businesses of many kinds. However, the problem is that nobody will find the website unless you spend a huge amount on marketing, and keep spending.
So barriers to entry are low, but barriers to commercial success are very high. This is why I generally don't invest in early stage internet businesses. They nearly all flounder, because they haven't got the marketing budget necessary to drive traffic to their website. Look at Koovs (LON:KOOV) for example - burning large amounts of cash, with little to show for it so far.
Have you noticed how fashionable it has become to describe any type of spending as "investment"?! So yesterday we had Marks and Spencer (LON:MKS) calling price cuts, "price investment". Today we have marketing spend being called "marketing investment". It's a bit daft really. I think they're trying to emphasise that not a penny is being wasted! It's all investment!
Apparently it was a American department store entrepreneur called John Wanamaker who famously quipped:
Half the money I spend on advertising is wasted; the trouble is I don't know which half.
The interesting thing today, is that with clicks being trackable, increasingly companies can measure the effectiveness of their online marketing.
Today's statement is a bit vague, but I'm increasingly forming the impression that things are not great, but not disastrous either, reinforced by this section:
The trends in bookings and Average Booking Value that we have seen in the travel market, particularly into higher priced European destinations, while partially offset by improved marketing efficiency, means that the year's outturn will be dependent on a recovery in key European destinations over the important summer travel season, and we remain mindful of the exchange rate environment.
My opinion - this company joins the long list of companies to have warned on profits not too long after listing. This share has a full listing, and joined the main market in Oct 2015.
I quite like the company, and the shares look potentially good value.
Numis has reduced its 2016 forecast EPS by 8% today, to 19.6 Euro cents, so that's about 14.9p EPS this year (albeit down on last year). At 188p/share, the PER is 12.6, which looks good value to me.
The forecast divi for this year is 14.9 Euro cents, or 11.3p, giving a divi yield of 6.0%. Wow, that's excellent.
The difficulty is, we don't know where the shares will find a bottom. It's usually a mistake to buy after a profit warning, as it's a mistake that I frequently make unfortunately. However, decent companies recover from profit warnings.
Going back to my 5-point checklist on profit warnings, this is how I score Hostelworld:
1. Is this a story stock? No, it's a profitable, cash generative, dividend paying company. PASS.
2. Are the problems fixable in a reasonable timescale? Yes - it just looks like a period of soft demand. Discretionary spending (marketing) is huge, so profit can be protected by cuts there. PASS.
3. Is the company financially sound & stable? Yes. It's cash generative, and has net cash on the balance sheet. PASS.
4. Will there be another profit warning? Possibly - the company says it needs a good summer season. So if current trends continue into the summer, then we might see another profit warning in say Aug/Sept perhaps? So probably a FAIL.
5. Are management doing the right things? Probably YES - trimming costs, to preserve the profit margin seems sensible when demand is soft.
Overall then, I'm getting a fairly favourable result from my tests above, apart from point 4, which is always the big uncertainty. Therefore, combined with an attractively low PER and high divi yield, I'm going to stick my neck out here, and suggest that this share might possibly be worth a small purchase for my portfolio.
I'm worried there may be more serious problems underlying. With 40% market share in the hostels niche, this company is a mature business now. So its PER should be fairly modest. I don't think it warrants a racy internet rating.
Overall though, I like it at this valuation. It might be sensible to wait, and see where the share price bottoms out. That said, today's fall in price does seem rather extreme, for what seems quite a mild profit warning.
Lombard Risk Management (LON:LRM)
Share price: 9.9p (up 2.9% today)
No. shares: 305.5m
Market cap: £30.2m
Results, y/e 31 Mar 2016 - another year, another lousy set of results under the belt of this banking software business.
The narrative is always similar - promising great things in the future, but it never seems to translate into real profits. Fantasy profits are reported - EBITDA, but that's reliant on a huge chunk of costs being capitalised into intangible assets.
The company is transparent though, and provides a table to enable readers to select which profit measure we prefer. I've highlighted the one that's most meaningful to me:
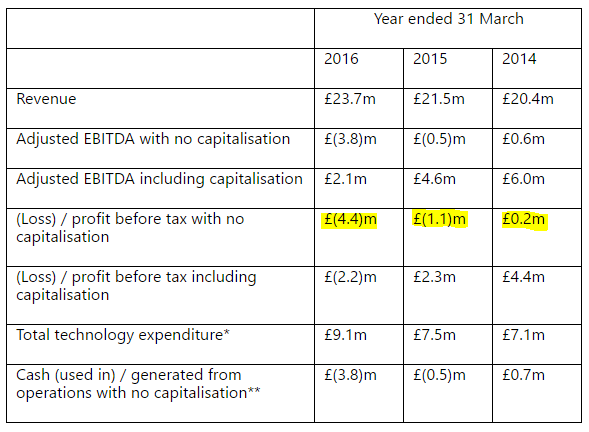
So using the most conservative figures, the company is now heavily loss-making. The trend for all the profit figures is downwards.
It's burning cash now at quite an alarming rate. The company raised fresh equity this year, so this looks like a planned increase in spend, in the hope that higher revenues will follow later, from new products.
Balance sheet - looks weak to me. The current ratio is poor, at 0.82. For me, the 1.2-1.5 range is a comfortable lower level for the current ratio. LRM is well below that.
Another fundraising looks inevitable at some point. Will there be investor appetite to keep throwing money into this company, for little tangible result? I wouldn't.
Dividends - confirming that cash is tight, the final divi has been passed.
My opinion - I don't like it. The business consumes cash, and is always promising jam tomorrow. Who knows, it might succeed in the end, by why speculate on that? I'd only be prepared to take a punt at a much, much lower share price, if at all. I can't see much evidence that the equity is worth anything, based on historic performance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
I see Hostelworld (LON:HSW) shares are down again today, now under 150p does look oversold to me and is very tempting to buy, will keep an eye on it next week.
Why are the directors share buys not showing up on Stockopedia?
Re RTN:
Unlike the rules in America, he would not have to be employed to be an insider trader. Anyone, including contractors, staff, relatives etc are subject to insider trader rules in the UK. The big difference is that in the USA insider traders - within their narrow definition, are frequently prosecuted unlike in the UK where the definition is very broad and pitifully few insider traders are prosecuted.
Hi All, first time poster too and as background i work in the online travel industry.
Agree with Browndog24 comments on hostelworld.com
They are after a different audience as they are looking at engaging the millennials who are looking for social experiences when they travel hence why AirBnB is a major threat.
They will also be facing more competition from Priceline group and their global accommodation brands booking.com / agoda.com who are expanding heavily from hotels into alternative accommodation which includes hostels (now have 390k alternative accommodation on top of their hotel inventory giving them 855k accommodation options).
As booking.com start to get that type of inventory then they will start to shut out hostelworld.com out of the variable marketing channels like google SEM and price comparison sites like tripadvisor, trivago as they will be able to bid more per click and they have very high converting websites. Due to their much larger traffic booking.com will be able to test and learn to improve their site / app faster than hostelworld, so will have a massive conversion advantage in these marketing channels. Previously hostelworld could hoover up the clicks with their different brands and bid at a low cost per click as their was minimal competition.
On top of this there is a massive shift in use of mobile, and also google has made some big changes to their search results to monetise better, so more of the top search placements / maps are all paid ads (SEM), and the free listings (SEO) are now below the fold and getting much less clicks. This means that brands like hostelworld.com will now be getting much less free google traffic, and they are competing against Booking.com who are the worlds best at travel SEM so they will have to spend more to acquire customers and traffic through that channel.
After having a quick play on their websites they are not best in class responsive even though 41% of their traffic is mobile, and they will be seeing lower conversion than the desktop, hence why the google / price comparison channel costs would have also been a pain point with that customer shift.
They will be desperate to get customers moving to downloading and using their app for repeat bookings as this will give them major marketing leverage as it is a low cost marketing channel ... the app seems to have some issues according to reviews, so hope they get it working well soon. I would expect that this is the key reason for the shift of 58% of customers booking in lower cost channels. I'm sure they are also looking at the buzzfeed style content marketing model and trying to engage their customers via social channels too, but this will be nascent and will take time to scale and competition as always is moving fast and innovating too!
All in all they face some serious headwinds due to their unit economics and expansion of the big beasts into their space, but if they make a rapid shit to the mobile app / social channels as their main source of traffic they will survive and do ok.
Not a 100% evidence because it's a non-exec and he may not (amazingly) be aware of any formal negotiations. That sort of thing has happened before. Or he could be inadvertently insider trading of Restaurant (LON:RTN) ;-)
Re RTN:
'Or he could be inadvertently insider trading of Restaurant (LON:RTN) ;-)'
Or not, seeing as he hasn't started his job at RTN yet :-)
Hi all, first time poster. I have been traveling for extended periods and used hostels.com and hostelworld to book all my accommodation. Their target market is very different to that of any other accommodation booking website. People book a hostel for the price, the facilities and the social aspect to meet people. My preference was always a hostel. Everyone you meet in a hostel will have found it on one of the hostelworld booking platforms and are generally a loyal bunch until they grow up and start using hotels! That said, I showed my girlfriend some of the hostels available and she was amazed at the quality and price of the rooms available on there. The other point to note is that a lot of hostel users are backpackers and are using for an extended period of time so it's not just people using them for a couple of nights or for a week long holiday. Airbnb is perhaps the biggest rival and a large group is more likely to find it more economical to avoid a hostel, but the hostels I've been to were mostly full of single travelers and couples. Yesterday's sell-off seems a little extreme to me. As the author confirms the company is financially sound.
The comment on not knowing which part of marketing spend was wasted was not made by John Wanamaker but by Lord Lever of Sunlight Port (now part of Unilever).
Hi Ray,
"The comment on not knowing which part of marketing spend was wasted was not made by John Wanamaker but by Lord Lever of Sunlight Port (now part of Unilever)."
Tell Google, not me! ;-)
I just looks things up on t'internet.
Regards, Paul.
Why would any sane PE house make a move on Restaurant (LON:RTN) now? From the evidence of the analysts' call there is plenty more value destruction that could be wrought by the incompetent CEO before the update in August. Add in the absence of any finance guy and there's absolutely no hurry. LFL sales are falling, the proposition is dated and the strategy is non-existent. Another profits warning could see the shares trading again at £2 something. The shares have come an awfully long way on the back of some spurious rumour from Sky News.
Elsewhere, I notice there has been little effect on prices of the car dealers today despite a fairly large acquisition by Marshall Motor Holdings (LON:MMH). Who's next?
http://www.am-online.com/news/acquisitions-and-dea...
All the best, Si
Debenhams (LON:DEB) I've bought into the story!
I like this new appointment! It could be inspirational and the company has certainly done everything but thrown in the kitchen sink, judging by the remuneration package, to capture Sergio Bucher's services.
Mr Bucher certainly comes with an impressive resume and wealth of relevant experience. If as stated by Sir Ian Cheshire, Chairman........
"I am delighted to announce the appointment of Sergio Bucher as the next Chief Executive of Debenhams. Following a rigorous recruitment process with some exceptional quality candidates, Sergio's wealth of e-commerce expertise, international experience and clear leadership qualities stood out. I am confident we have the best possible person to realise the potential of 'new Debenhams' as a leading international multi-channel retailer with a bright future."
...... can indeed meet and surpass these expectations then DEB's could turnout to be a very shrewd and rewarding investment.
Good luck!
"When a management with a reputation for brilliance tackles a business with a reputation for bad economics, it is the reputation of the business that remains intact."
Warren Buffett
Watch out. Hostelworld (LON:HSW) is a classic PE rinse & repeat job. H&F now completely out. Stitched up some unsophisticated instis. Directors have virtually no equity interest and have already been handsomely rewarded for stuffing the instis.
Volumes are dropping and will continue to dwindle. The marketing costs - millions spent on annual IP hosting charges - are relatively fixed if they want to continue to own the addresses.
At some point this will be taken private again and the cycle will repeat itself.
Just not enough gap year students to keep this business afloat. As I said in my first post, this is a business built on blarney.
The network effect is what is driving platforms such as Hostelworld (LON:HSW) isn't it? They hope that they will be able to dominate their niche and become so well-connected that they no longer have to advertise because they can e-mail their users directly.
I thought your comment was really interesting, Paul "45-50% of revenue spent on marketing is gigantic! It reinforces my view that there are few barriers to entry for internet businesses of many kinds. However, the problem is that nobody will find the website unless you spend a huge amount on marketing, and keep spending."
I was looking at On Beach (LON:OTB) following the recommendation in the Giles Hargreave interview. They also spend just under 50% of revenues on advertising. Initially I viewed this as a negative. However what was impressive is that they have a clear strategy for acquiring and keeping customers and tracking brand recognition. It's clear that they could stop the marketing spend and have a viable and much more profitable business. Instead they choose to spend and keep growing. In that sense it is positive when costs that are equal to half your revenues are discretianary and can be varied at will.
The difference between the companies (in my view) is that Hostelworld (LON:HSW) is adding less value. It is simply presenting the options in a sub-set of the market and offering a booking service. So as others have said, between TripAdvisor and Airbnb they could get hooribly squeezed. Wheras On Beach (LON:OTB) buys flights and hotel rooms itself and enables customers to mix and match their holidays. Also, travelling to hostels is something you might do once, or at the most a few years running, and it's cheap. A beach holiday is more likely to be an annual event and the spend is higher.
In summary, I think you have to look at the end goal. How big a market is the company addressing, does it have a credible prospect of achieving the scale for those valuable network effects to kick in and, to Paul's point, does it have to keep spending heavily on marketing forever or does it get to the point where repeat customers and recommendations are enough? Based on those criteria I would avoid Hostelworld (LON:HSW) on the grounds that the long-term rewards just don't look enticing enough.
It would explain why their rooms do seem expensive, problem is with discounts on Hotels they are close to their prices, certainly in cities like Bangkok you can get a reasonable room for $20 why would you want to stay in a Hostel for about the same price? Same with dorms why when you can get a private room in a guesthouse for the same. I would be interested to know the breakdown of countries their customers are from.
Re Hostelworld (LON:HSW). What a difference a few weeks makes. On 5 April they were trading in line. On 12 April, Numis launch an accelerated bookbuild for Hellman & Friedman and Duffy family to sell 25% of the company and exit at 260p. Six weeks later, the AGM statement says they are reliant on a recovery in order to make the numbers for the year.
I'm assuming the geo-political events they are referring to are the Belgium bombings. If the Belgium bombings are to blame, it's hard to believe that a change in the number of bookings would not have been immediately apparent. For context, the Belgium bombings occurred on 22 March or two weeks before the "trading in line" results announcement. Also, the prospectus says they have "a smaller peak in bookings around the Easter travel period" which was 27 March. This was also before the "trading in line" results announcement.
I think Hostelworld.com is a potentially interesting business but it is paired together with Hostel Bookers and Hostels.com under the same corporate umbrella. Hostel Bookers was purchased in 2013 and had about an enormous amount of the goodwill written off in 2014. Hostels.com is less than 10% of bookings. Hostel Bookers and Hostels.com (taken together) are seeing declining bookings (FY14: 2.66m bookings, FY15: 1.95m bookings) whereas Hostelworld.com increased bookings (FY12: 3.755m, FY13: 4.001, FY14: 4.448m, FY15: 5.226m). Additionally, the number of properties listed declined between Aug 2015 (prospectus) and 31 Dec (results presentation) from 37,451 to ~35,000. Incidentally, only 1/3 of the properties are hostels with the remainder being other budget accommodation (whatever that is). A decline in the number of properties listed is generally not a good sign.
I guess the good news is that the Hostelworld brand is showing "strong" bookings growth which suggests that the likely culprit is Hostel Bookers and Hostels.com and/or the myriad of other factors listed. May to August represents 40% of bookings (prospectus p. 71) so they should have much better insight at 1H16 results.
So you would be suggesting this is somewhat suspicious then ? That's certainly how I would call it, based on what you wrote.
The director dealings section on Digital Look has no mention of any director dealings in the last 12 months.
Incidentally, it does show Mr Woodford's firm as by far the largest shareholder.
As a customer, I stopped using this company due to their disingenuous pricing. There I am booking a double room, then when I click through to pay, the price doubles as they price per person, rather than per room.
Most companies quote a rate per room & I would rather deal with one of them.
Perhaps the backpacker set who sleep 8 to a room have different priorities & maybe there is less competition there ?
Maybe AirBnB is eating some of Hostelworld (LON:HSW) market, I have read their statement now, it says about disappointing bookings in higher priced European destinations, maybe travellers are not going to those so much or they are using other places to stay. Interestingly I hardly meet any British people these days in countries like Vietnam, Laos, Myanmar, Cambodia where are they all going these days?
Re Woodford Patient Capital Trust (LON:WPCT) - Industrial Heat is only one of many blue sky investments that assorted snake-oil salesmen have conned Mr Patient into backing. Got to hand it to the guy, though. Sheer marketing genius to call it Patient Capital Trust. As in, whatever your time horizon is, his is longer and it's your fault for being impatient.
Debenhams (LON:DEB) I have been considering but the Altman Z-Score is rather low, I don't know if Paul can shed any light on that?
Debenhams (LON:DEB) I have been considering but the Altman Z-Score is rather low
Z-Score is a composite of four factors that have historically indicated financial distress. if you click on the value in the StockReport you can see which values are causing the concern:
While for a lot of companies stretching their working capital is a sign of distress for many consumer facing businesses like retailers & cinemas it is just how their business works. They get paid in cash up front and pay their suppliers on 90-day terms. This obviously becomes a problem if the turnover declines significantly and the WC unwinds but not for a stable or growing business.
The negative working capital also contributes to the weak fourth metric. Combined with how some up-front lease incentives and things like that are accounted for as liabilities.
IMO the Altman-Z doesn't work particularly well for these normal negative working capital type businesses.
What these metrics do highlight is that there is no asset protection in the business if it were to be wound down. Why you would voluntarily wind down a business that consistently generates c.£200m OCF & c.£100m FCF pa I don't know. But it is a risk that is worth being aware of for the long term.
Re Hostelworld (LON:HSW)
Considering the statements...
"..this will result in marketing investment as a percentage of net revenue coming in below the previous guidance of 45%-50% on a full year basis"
and
"However, the problem is that nobody will find the website unless you spend a huge amount on marketing, and keep spending"
Then it does sound as if Hostileworld's squeeze on costs is going to lead to a further decline in business?
Won't they have some sticky business, e.g. people having booked in the past booking with them again? Platforms tend to have network effects.
Paul notes that online advertising is more traceable, but the data is likely very noisy, e.g. you'll get false positives (say people who knew the site and looked it up on a search engine, and entered through the advert because it is on top of results, but would also have found it with no advertising because it's also top of unpaid results) and false negatives (people who become aware of the brand due to advertising, do not buy anything during traceable sessions, but come back later).
In an optimistic scenario maybe Hostelworld are genuinely advertising too much...
Possibly but depends on their experince, also there is a very similar chain called Hostelbookers, not sure how much loyalty there is in bookings, think people tend to look for best deals and reviews. I tend to agree people know about them anyway no need to advertise too much. Its quite competitive now with agents and discounts, last time I used Hotels.com because I got 10% discount and 1 free night if I booked 10 nights which I did. Prices were similar to other Hotel agents.
Hostelbookers is just another brand name of Hostelworld (see bottom of page).
Hostelworld actually bought Hostelbookers in 2013. I recall from my travelling days in 2008 using these two sites almost exclusively to book my dorms. I would use the rating systems of either, which are excellent and then choose which site offers the cheapest. I'm not sure what level of cannibalisation there has been since, or whether the reduced competition has boosted margins. Whilst there is competition from the likes of AirBNB and Hotels.com etc. Hostelworld caters for a particular type of traveller- those that like to stay in shared dorms, and meet people from around the world. There is little competition in this niche market.
I disagree, there are many guesthouses who have been offering that for years, many don't have dorms thats true but not everyone wants to share a room witha load of backpackers. I would always choose a private room which is often not much more, in fact less in some places.
There are many that do want to stay in dorms though eg. party hostels and people that are travelling alone. Like I said, it is a niche market for which the primary medium of booking is Hostelworld or one of the other Group brands.
Yes I would agree with that, its mostly for school leavers/GAP and first time backpackers, the problem is how do you grow bigger. Can expland in Asia but thats a very competitive maket. Europe seems to be their big problem at the moment. Maybe the americans have been put off by the bombings and shootings in Belgium and Paris?
Re: Hostelworld.
I must admit that I was rather tempted by this company having read the Investors Chronicle article 7 April. They mentioned that Woodford Investment Management, Miton Asset Management and Baillie Gifford were keen investors when it listed. I also liked it because it had cash (although I presume that was a result of the listing so don’t know how long it would take them to burn through it) and that it was paying a dividend (although it wasn’t that hugely covered).
I looked at the website (for Asia as my daughter is planning to head off there) and it seemed easy to negotiate, although having had all kinds of shenanigans thrown at her from Lastminute.com, I now know that you have to use these websites to know how ‘tricky’ they can be to customers and how much they can muck you around.
In the end, I stuck with my rule that I need more vision on the finances before investing i.e. it is too new! On that basis I never got to look at the company’s prelim results figures to drill down any deeper.
Thank you Paul for your comments on how gigantic the marketing spend is. My mind had rather glossed over this thinking it was good to get the brand out there, but I guess there has to be a limit.
Good luck to those who hold. I hope it comes good.
Santa
As regards Restaurant (LON:RTN), my amateur reading of the takeover code is that the responsibility for making an announcement prior to approaching the Restaurant Group board lies with the potential bidder, but if any approach has been made, however informal, then Restaurant Group are obliged to make a statement given the unusual price movement in their shares, except that if they have unequivocally rejected an offer they may depending on the price movement not have to make a statement either. But at the least I would think someone there should be talking to the Takeover Panel to clarify the position and their responsibilities.
This situation isn't improving anyone's confidence in the CEO is it?
http://www.thetakeoverpanel.org.uk/wp-content/uploads/2008/11/code.pdf
"3.3 Rule 2.3(a) provides that the responsibility for making an announcement
before the board of the offeree company has been approached will lie with
the potential offeror, whereas Rule 2.3(c) provides that the responsibility
for making an announcement following an approach will normally rest
with the offeree company board. However, if the offeree company board
rejects an approach it will not necessarily know whether the potential
offeror intends to pursue its interest in the possible offer. Therefore,
following an unequivocal rejection of an approach, the Executive’s
practice is to treat the responsibility for making an announcement as
reverting to the potential offeror. Nevertheless, since the potential offeror
will have made an initial approach to the board of the offeree company
(albeit that the approach was unequivocally rejected), the Executive will
apply the criteria in Rule 2.2(c), and not the criteria in Rule 2.2(d), when
determining whether an announcement is required following rumour and
speculation or an untoward movement in the offeree company’s share
price."
"4.5 Note 1(c) on Rule 2.2 also requires that the Executive should be consulted
at the latest whenever there is a material or abrupt movement in the
share price of the potential offeree company after the time when an offer
is first actively considered by a potential offeror. For these purposes:
(a) a movement of 10% or more above the lowest share price since that
time is regarded as a material movement; and
(b) a movement may be abrupt even if there has not been a material
movement: for example, a price rise of 5% in the course of a single
day is normally regarded as being abrupt. When calculating share
price movements in the course of a single day, the reference price
should normally be taken to be the previous day’s closing price,
in order to ensure that overnight movements are included in the
calculation.
The Executive should be consulted in the case of any doubt as to how
share price movements should be monitored and calculated."
Guess where a huge chunk of that marketing spend goes? The investment case as explained to me by the H&F MD was that they owned literally tens (he may even have said hundreds) of thousands (I may be imagining it but he may even have said millions) of IP addresses relating to hostels so whatever you type into a search engine the company appeared in the search results. At the time this struck me as a desperate strategy. I may be revealing my ignorance about how this type of business works but I thought people might like to know and consider whether this said anything about the company and its product.
Maybe in that case they could get taken over by one of the majors?
RE. Hostelworld (LON:HSW)
The company's revenue split is broadly 64% Europe, 18% Americas and 18% Asia Pacific.
Today's RNS message is that Europe has weakened but Asia Pacific continues to grow fast.
So unfortunately it is the largest market segment that is hitting problems - not what I wanted to hear.
Woodford has bought some absolute pups for Woodford Patient Capital Trust (LON:WPCT). Pretty likely that the H&F MD (like Woodford, Oxford-based) stitched him up with this one. I was FD for another Woodford investment disaster and my money would be on the H&F MD to leg him over every time on this tech stuff. WPCT also owns just under 30% of another dog with a smooth-talking CEO - UTW - and he hasn't managed to hold that one up.
Yes, having subscribed to Woodford Patient Capital Trust (LON:WPCT) at launch I happily sold out near the top when I looked at their investment in Industrial Heat which is an unquoted company that claims to be commercialising cold fusion. That represents 1.99% of the fund.
Great for all mankind if they can do it, but not my idea of a wise investment.
It doesn't sound like things have been going very well at Industrial Heat: http://www.popularmechanics.com/science/energy/a20454/in-cold-fusion-20-whos-scamming-whom/
I hope they have a Plan B.
I was so surprised Neil Woodford has invested in this I had to go and see his portfolio holdings with my own eyes. Wow. Thanks mammyoko and JohnEustace.
Yes, it took a double take for me to believe it. I posted my concerns on their blog on August 21st last year which led to some vigorous debate. WPCT are sticking by their due diligence process.
https://woodfordfunds.com/blog/focus-on-long-term/
There is no way that cold fusion could ever work. You need temperatures of millions of degrees, such as those at the centres of stars, to overcome the enormous mutual electrostatic repulsion of positively charged helium nuclei in order to start a nuclear fusion reaction.
Chemical forces at room temperature are nowhere near powerful enough. As 2% of the Woodford Patient Capital Trust is invested in a cold fusion company, that demonstrates to me that Woodford has not taken competent scientific advice on a subject he evidently knows nothing about and is a good enough reason for me to never invest in any of his funds.
Hi Paul - RE. Hostelworld (LON:HSW)
I applied your excellent 5 points analysis before the bell and I came up with similar conclusions.
An additional point worth making is that Woodford has a huge stake in this company, something of the order of 20-25%. Like him or not, he does move markets and share prices.
So I went long this morning although the key issue to me was one of timing.
Regards, Ram
Thanks for the reply Paul. Much appreciated.
Hi Paul
Did you notice that the Restaurant (LON:RTN) price spiked up into the close yesterday evening, just before the markets closed? I thought this may have been a sign that a bid was in the pipeline, and an RNS would be issued shortly afterwards.
When there is speculation in the media as in the case of Restaurant (LON:RTN), that a bid may materialise are companies obliged to issue an RNS to confirm or deny this?
Best wishes,
Imran.
Hi Imran,
My understanding is that if a share price moves up significantly, on takeover bid rumours in the press, then a company is obliged to issue an RNS.
I think Restaurant (LON:RTN) has serious questions to answer, as to why it has not done so, when it clearly should have said something by now.
The broker needs a rocket under them.
Regards, Paul.
It's surely only if it moves up significantly intra day, or over a couple of days..but 32% over three weeks - hardly going to ring any alarm bells.
If it'd been a 20% rise today, on top of 12% yesterday, then Yes, I'd concur with your "Must notify,one way or another, via RNS"
Over three weeks, no way.
The absence of an announcement is proof of either:
1. The offeror &/or RTN are ignorant of the UK Takeover Code, or;
2. There HAS BEEN NO OFFER!
The Sky story from a week ago suggested that Cinven were in the EARLY stages of appraising a potential bid.
It would appear that wishful thinking has led a few investors into believing that this appraisal was instantly positive, that talks have begun & that a bid is imminent! Oh dear :(
In the words of David Hume: The wise man proportions his belief to the evidence.
PJ,
No you're wrong.
If a company has received possible takeover approaches, even if early stage, and the share price has risen considerably, then they are OBLIGED to update the market. Even if that is to just say that some preliminary approaches have been received, discussions are ongoing, which may or may not lead to a bid.
Paul.
Still sounds like wishful thinking Paul!
RTN are not obliged to comment on their share price appreciation.. unless they are negotiating a takeover approach.
They have yet to comment.
QED. They have yet to receive an approach.
Any other thought is misaligned with reality!
Good luck with any approach beyond today!
Today's announced share dealing by a RTN director is surely evidence that they are NOT currently in takeover talks.
Hi PJ,
You said:
Today's announced share dealing by a RTN director is surely evidence that they are NOT currently in takeover talks.
I agree, that's how I read it too. So I've sold half my position, after a good rise in the last 3 weeks.
Although the other poster above also has a point - that a new NED coming in may have bought the shares independently, without knowing anything about possible bid talks.
Regards, Paul.
Paul,
Thanks for bringing Hostelworld (LON:HSW) to my attention. It does look potentially interesting, especially on a yield basis, although I do not normally invest in these type of "intermediary internet based" companies. How much effort would it be for TripAdvisor to start listing the same hostel properties and use it's marketing clout to drive users away from Hostelworld? Not a lot I'd have thought. Then there's AirBnB too.
The website looks OK and is easy enough to use so I just checked out the properties for Cambridge, one of the more expensive places for young people to stay in England. There were only 4 properties listed. Now Cambridge is one of the most picturesque towns in England too and yet for some bizarre reason there was a picture of Stonehenge which is about 150 miles away! I think the website may still need some work...
All the best, Si
Hi Si,
I have used HostelWorld when I went travelling a couple of years ago - very easy to use. I would say the UK market isnt really geared towards the travellers that would use Hostel World.
Think : South East Asia, South America, Europe.
I dont think researching just Cambridge would give you any idea of the company.
Yes I agree its more about travelling abroad than uk. I have used them very occasionally, I don't like their charges, which tend to be per person, so single rooms are pricey and usually they are more expensive than other nearby guesthouses. They are aimed at a certain type of traveller so don't really suit me. The advantage is you can book ahead but then there are so many more online booking agants now so its not such a big deal.
I checked Mandalay which is where I went last trip, they had a dorm bed in 8 bed dorm, for £8 something, great, so thats about $12. Location its well out of the centre. I stayed in a central Guesthouse, own twin room with bathroom with breakfast and aircon for $15, I could have had a smaller fan room without bathroom for $8, so not contest really, oh I travelled in February which is peak season.
Hi James,
I dont think researching just Cambridge would give you any idea of the company.
Yes, I agree and it was only a cursory glance using a location I am familiar with to get a feel of the website and the type of properties they have. However, the picture of Stonehenge for listings in Cambridge is just plain bizarre - it shows a lack of attention to detail that I do not like, particularly in an internet-based business.
I've spent the last hour having a closer look and decided Hostelworld (LON:HSW) is really not for me. When we stayed in Oz recently we booked direct with TripAdvisor and the same accommodation was listed on numerous other sites, including AirBnB. From talking to customer service at TripAdvisor it sounded like they would be dealing direct with the property owner more and more in future. I believe the IPO timing of Hostelworld (LON:HSW) is probably highly opportunistic in the face of this level of competition. I'd need a lot of convincing it is not a value trap.
tbh If I'm just looking for a 6% yield I'd rather buy Legal & General (LON:LGEN) :-)
All the best, Si
I have a trip coming up to Budapest so just looked at the hostel options there out of curiosity. The ones I looked at on Hostel World were also on Trip Advisor - in fact Hostel World was listed there as a booking option alongside Booking.com and Agoda at if anything higher prices so I tend to agree that they risk being run over by the big boys.
e.g. The Hive in July is £26 per night on Hostelworld and £24 on booking.com via Trip Advisor.
Plus at these prices there can't be a huge margin to go for.
Personally I think I'll stick to the Ibis.
This is an ex-Hellman & Friedman purchase. I used to know the MD at Hellman & Friedman who actually bought it for them. He told me at the time that the CEO had the gift of the blarney. Knowing that H&F MD as I do you can be absolutely sure that this was dressed up within an inch of its life for sale. This was a disaster waiting to happen. I would take your time over stepping in here for all the marketing reasons that you have enumerated