Small Cap Value Report (27 Feb 2015) - MYSL, BOO, WTM, QPP, HVN

Good morning!
MySale (LON:MYSL)
Share price: 52p
No. shares: 150.6m
Market Cap: £78.3m
Interim results - the company had already warned on profits, so poor results were expected. That said, I'm feeling negative about the company reading these figures. It looks to me as if their business model is questionable. Growth has all but dried up, and the company remains heavily loss-making.
I do like their business model of having no inventory risk - taking excess stock on a sale or return basis from suppliers. However that is reflected in much lower margins.
The £3m Director purchase at c.80p just before Christmas appears now to have been for show, rather than on fundamentals. Either that, or he had already made a start on the Xmas booze and had £3m burning a hole in his pocket?!
On the positive side, there's plenty of cash in the kitty.
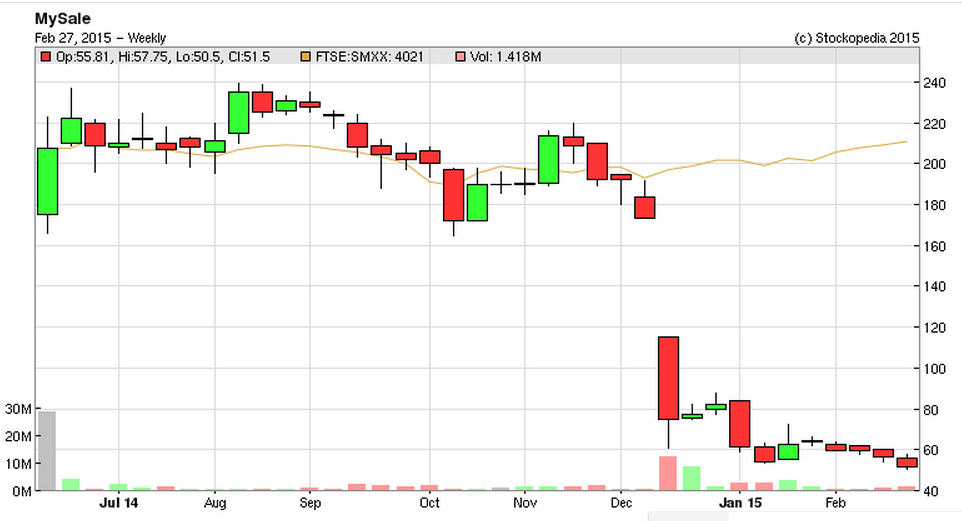
My opinion - MySale has a lot to prove, and in my view it has not yet demonstrated a viable business model. The penny is starting to drop with investors that internet retailers are just distributors to the public, through a website. They don't have any magic formula for making money, and the stretched valuations on many are accidents waiting to happen in my view - so I remain short of a number of UK online retailers.
There are many competitors popping up, and so anyone who thinks they can dominate a market online is probably deluded (the exceptions being the giants like Amazon, Ebay, etc).
The only reasonably-priced online retailer that I've found is Boohoo.Com (LON:BOO), which after a profit warning in Jan 2015 (original expectations at the IPO were far too high) is now on a fwd PER of 20.3, less if you remove the cash. That seems to me a sensible price for a decently profitable business that is growing at a reasonable pace, and is making good progress overseas, as well as in the UK. There was some interesting original research on BooHoo & its competitors, from Investors' Champion earlier this week, click here.
So why would I look at MySale, which is loss-making, and having to close in certain countries because it didn't work? That sounds to me like the business was a nice idea, but isn't working. Just because Philip Green is backing it, doesn't mean it will automatically be a success. He is a brilliant retail man, but he makes mistakes too - all entrepreneurs do - you have to try things out to see if they work. Some will, some won't. I suspect this won't.
The trouble with surplus stock, is that it's surplus because customers don't like it the first time round, when it was in shops. So just because it's cheaper now, doesn't mean it will necessarily sell on a clearance website such as MySale. I recall from working in the sector that some items just wouldn't shift even if you put them into 75% off sale.
Waterman (LON:WTM)
Share price: 67.25p
No. shares: 30.8m
Market Cap: £20.7m
Interim results for the six months to 31 Dec 2014.
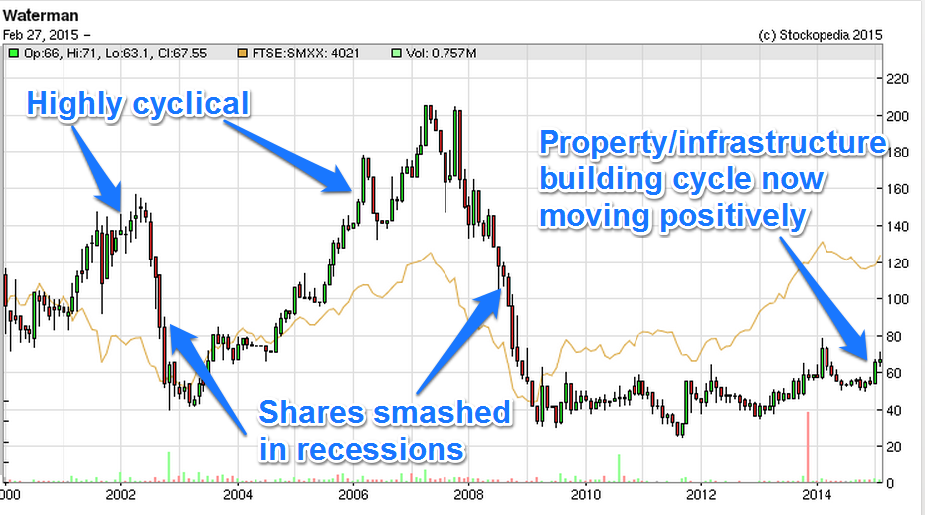
On an initial review (I'll read in more detail over the weekend), these figures look good to me. The company is cyclical, and is now seeing improved trading. It's important to note that the group has one under-performing part, which is loss-making, but that's being sorted out gradually. So there should be good upside when the restructuring has been completed.
The presentation of the figures is not what I'm used to, in that they seem to have shown three sequential half years together, which I find confusing.
Adjusted profit before tax is up 75% to £1.4m, which I'm impressed with.
Balance sheet - Waterman's balance sheet passes my simple tests, as follows;
1. The current ratio is 1.36 (I like this to be at least 1.2 usually), PASS.
2. Net Tangible Asset Value (NTAV) is positive, at £12.2m. PASS.
3. Bank debt is minimal, and at the balance sheet date the company reported net funds of £3.6m. This is validated by a low P&L interest charge. PASS.
Dividends - note that these are rising strongly, and the yield is starting to get interesting. The interim divi has been doubled to 0.8p, and the full year divis look on track against forecast of 2.0p total. That gives a respectable yield of about 3.7%. With further increases, it's not difficult to see that yield rising to say 5%+ with a bit of patience.
Broker forecasts - these look too low to me. So I think there's an opportunity here for the company to beat forecasts, and hence see a further rise in the share price, possibly?
My opinion - I like this share, and whilst the company's track record has been patchy (it's a heavily cyclical business), the cycle is now working in their favour, and hence results are improving. As we always say, and mean (!!), please do your own research. As I mentioned in a presentation the other night, investing is a team sport, so by pooling our research and analysis, I'm sure we come to better decisions most of the time.
I flagged up that this stock looked potentially interesting here on 5 Dec 2014 (at 56.5p).
Also, one of my interviewees, analyst/investor Paul Hill, gave his views on Waterman in this audiocast from 25 Jan 2015 (from 8:20 to 11:35).
Quindell (LON:QPP)
Update - the investigating accountants, PWC, were due to report by the end of Feb, although it should be noted that such a report won't be published. We'll just get a sugar-coated version of the bits that the company wants to tell us, I imagine.
Today's update is just a holding statement really, saying that it's taking longer than expected (and must be racking up a helluva bill from PWC - I used to work for them, and the charge-out rates on this type of job are usually high). Given that Quindell has a sprawling corporate structure, due to an acquisition spree under the founder, then it's bound to take time to unpick all the detail, and assess a large enough sample of live cases to form a conclusion as to what their recoverable value might be.
Disposal talks with SGH are ongoing, and some non-core subsidiaries are to be disposed of, which makes sense given that cash is tight.
I don't think anything in particular can be gleaned from today's update.
My view remains the same as it's been for several months now - that there is clearly some value for the good bits in the group, but nobody seems to know how much - opinions vary wildly! I've never been in the 0p camp, but equally can't determine what it might be worth, as we don't have any accurate information. Also if no disposals happen quickly, then it might need some kind of cash injection to resolve the chronic inability to generate positive cashflow. All fascinating, but I remain happy sitting on the sidelines with no position now.
Harvey Nash (LON:HVN)
Trading update for the year ended 31 Jan 2015, saying that results are in line with revised expectations. Also it says cashflow has been strong, with net debt having reversed round into a net cash position of £2m.
Directorspeak sounds fairly upbeat, so overall this one might be worth a look possibly?
Balance Sheet - it passes two out of three of my tests. The one it fails is the current ratio over 1.2. The last reported current ratio here was 1.06. That might seem low, but for the recruitment sector I could live with that - the reason being that there is no "Inventories" item in current assets for service businesses. Therefore a current ratio maybe as low as 0.9 is probably OK in this sector. The most important thing is that there is no long-term debt, so overall I'm happy with this balance sheet.
The main balance sheet risks are withdrawal of bank facilities, which seems unlikely with this company, and bad debt risk from a large customer going bust - so credit control is absolutely critical.
My opinion - looks quite good. Although there are plenty of smaller recruitment companies to choose from, which are all much of a muchness in terms of performance & valuation.
That's me done for the day & the week. Have a smashing weekend, and I'll be back here on Monday morning.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in BOO & WTM, and no short positions. A fund management company with which Paul is associated may also hold positions in any company mentioned here)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Hi Paul, I see SNTY shares are down quite a bit today, can't see any reason for it, any ideas?
Thanks to everybody who joined the conversation about Optos. For Purpleski: I don't propose legislation for preventing foreign takeovers because all legislation just creates loopholes. Optos board and major investors could have said no thanks to Nikon. It's more of a mindset thing for companies and institutional investors who see takeover as the best outcome instead of further growth. The same happened with Delcam who make CAD/CAM software. It just seems to me to be a lack of ambition.
I agree with Jane Bolacha about Mittelstand as I worked in Germany for a couple of years and know people involved in those type of companies. But a lot of them a private and so not investable. I'm not complaining as I've made a profit, but I'm a Yorkshireman and we're never happy unless we're moaning about summat and nowt.
Have a great weekend.
Cheers
Glen
Hadn't considered the point about customers bypassing- thanks, that's going towards the 2.1!
Also just a quick question- what's the minimum market cap you normally consider for this report?
There is a 10million market cap company called london finance and investment group that is trading at half NAV that gets you cheap exposure to finsbury foods, creston and northbridge industrial services - only picked it up because some of those names were on my watch lists a few years ago
Thanks for the report- part of my daily reading list!
One of the very great strengths of German industry and the German economy is the "Mittelstand", the vast number of small- and medium-size businesses, often still family-owned, who cover just about every sector. It is in very stark contrast to UK where the emphasis seems so often to be on floating the business on the market and selling out as soon as possible, often to non-UK buyers. Perhaps it's a question of short-term over long-term. The role of the City in promoting the short-term approach is obvious; that way, they earn fat fees, whomever they manage to get the business sold to. They are certainly not bothered about "UK plc", imo.
Thanks for the write up paul. Just a quick word on online companies on 'silly' valuations- doing a research project on Just Eat as part of a project, and it is absolutely key to differentiate between the guys just doing distribution with a nice online interface (ao world) and those companies with something much more sticky and with higher barriers to entry.
For example whilst I'm not buying just eat stock there is no way I would bet against it:
- it serves a multi-sided market (consumers and restaurants) and benefits from network effects- the more consumers join, the greater the attraction to restaurants and vice versa
- it probably has a big first mover advantage and has reached critical mass- has signed up 20,000 of the 40,000 uk takeaway restaurants offering delivery
- restaurants benefit a tonne from joining- £1000 signing on fee and 10% revenue fee but get an online presence with little upfront cost and get a software box delivering customer orders very efficiently. Also benefit from larger average order sizes online.
- highly cash generative, benefits from float effect- takes all the payments and distributed bi-monthly
Not saying it justifies the valuation but it may well do- it has network effects and switching costs that should allow it to return a persistently high ROCE. Boo hoo, asos, ao world will not have this, although they may benefit from having a 'best in class supply chain' that may take a while for others to replicate.
Just well worth properly trying to understand every online stocks true business model before chucking it in the overvalued rubbish box (where the vast majority of these companies belong)
Hi Mh101,
That's excellent analysis of Just Eat (LON:JE.) and I agree with the points you make.
I originally put this share on my bargepole list in Jul 2014, but quickly revised my opinion (see the narrative, which I don't edit) and closed my short position for an 18% loss in Aug 2014, at 255p, when it became clear to me that there was more substance to the business than I had originally realised.
Good job, as it's risen about 100p since then! At some point it will be a nice short again, but I'm learning that over-valuation alone is not a good enough reason to short something. There has to be something fundamentally weak about the business model (as there clearly is with AO World (LON:AO.) - it's just a very low margin box shifter), as well as it being wildly over-valued.
There is competition of course - I've seen Hungry House ads on TV, and have used it, seems a very similar offering to JustEat. My main issue with JustEat is that it's easy for the takeaways to by-pass JE once customers become regulars - they just tell you to ring up instead, and they give you an extra couple of poppadoms free, or give you a 10% discount, to by-pass JE.
Thanks for your comments though, very pertinent points.
Regards, Paul.
Thanks for the write-up on Waterman, Paul. These look like a cracking set of results and I am surprised that the market reaction has been so muted. The press release says "The company reports a revenue growth of 25% and profit growth of 57%. It remains on track to deliver the strategic targets of tripling annual adjusted profit before tax to £3.3m by July 2016 and generating a return on capital employed of 20%." So if the company is fairly valued now with £1.4m pretax profit, that suggests significant upside to 2016 with the protection of a strong balance sheet. I have been holding since last year and have added more today, on this confirmation that the strategy is on track.
I like companies where there has been an issue that has dragged the shareprice down but it's clear what that is and how management are tackling it. Even better if the solution does not involve new products or markets but simply running down an underperforming division and letting the goood performance of the rest of the business shine through. An analogy with French Connection, perhaps?
By the way, the reason there are three sets of 6-months figures is that the the company has a 30 June year-end. So they are giving figures to 31 Dec 2013 as the comparatives, then the intervening 6 months (to show the trend, I guess) then the 6 months to 31 Dec 2014 as the latest available. Normally at this time of year you would be getting the full-year figures. I think the middle column to 30 June 2014 can be ignored, basically - just focus on columns 1 and 3.
The ROCE they quote vastly differs from Stockopedia's ROCE 2.9% and ROE 0.7%. 2014 mind you.
Glen K has summed up what I was told in a Seminar about Intellectual Property some 25 years ago and has been emphasized by Neil Woodford in his new Patient Capital Trust. The bottom line is we in the UK are "very good inventors but rubbish innovators". ie we can invent things but are clueless in bringing them to successful markets
At Mello in Derby Katie Potts added her voice to the frustration of early sellouts for potentially great UK technology breakthroughs. She has even persuaded some entrepreneurs to stay the course and reject the early sell.
I share the disappointment at not growing world size companies, although I slightly temper it with the hope that as large chunks of disposal income become available (from sellouts) we may at least be able to fund more startups even if their fate is to be taken over too early.
The constant attention to, and foreign investment in, the UK is helping to keep the new company activity high, so at least we still have more possible giants to create.
Glen,
for another potential UK technology winner, with genuine patent backing and the ability to integrate systems top-to-bottom, rather than just being a component provider to bigger boys one needs to look no further than Kromek (KMK). These guys got a pasting on AIM last year because of some ill-advised overestimates of potential first year financials but that does not detract from the strong moat they have built around their technology.
paul, i agreed with the analysis on online retailers, actually came to that conclusion in dec '15 and sold Amazon.com Inc (NSQ:AMZN) (v small profit) and saw it climb steadily thereafter.
how do you value internet retailers, in theory someone else could set up shop and charge 1p less tomorrow, so i suppose the value is the number of customers x spend x stickyness x margin ?
Well done to you Glen K -spend it wisely! It is also a rather wonderful story as to why the technology was developed in the first place. Anyone got any views on companies which might become the next Optos.? Most medical device companies seem to struggle -but Woodford may be onto a few winners down the track.
Paul, you've covered Optos here so I just wanted to have a soapbox moment on your comment section. Hope you don't mind. Keep up the great work. Daily reading for me.
Today one of my biggest shareholdings Optos (LON:OPTS) is being sold for cash to Nikon in Japan. I bought in after a profit warning almost 2 years ago, so I’m money happy. But as someone with a technology background who wants Great Britain to have an advanced manufacturing industry, I’m not so happy.
I invested in Optos because I believe it is great technology backed by patents. It is a British company exporting hi-tech equipment around the world. It’s Dunfermline factory is shortlisted for UK Manufacturer of the Year 2014.
It seems the ambition of small hi-tech companies in the UK is to be bought out by a big foreign concern. I feel this shows a lack of ambition with UK Plc and means that this country is effectively in the second division and any star performers are taken over by the Premiership big boys. We will never build an Apple or Google when most successful start-up tech firms never get past the small or mid cap level.
The decline of hi-tech manufacturing is a long term 20 year issue and, as such, is of no interest to the markets, politicians and other short term headless chickens. Maybe when Optos manufacturing eventually moves offshore we can use their factory as a call centre for PPI mis-selling cold calls.
Just a quick summary of the Optos story - part of the reason I bought was psychological bias and we all like a good story stock. But hey, we’re just shaved monkeys with a reptile inner brain.
“Optos was founded and incorporated in 1992 by Douglas Anderson after his then five-year-old son went blind in one eye when a retinal detachment was detected too late. Although his son was having regular eye exams, routine exams were uncomfortable, especially for a child, which made it impossible for the doctor to conduct a complete exam and view the entire retina. Anderson set out to commercialize a patient-friendly retinal image product that encompassed a digital widefield image of the retina in a single capture.”
Quote from Douglas Anderson - European Inventor of the Year 2008
"At the end of all that struggle we succeeded in making a valuable imaging device that everyone said was impossible technically, clinically unnecessary, and certainly doomed commercially. But we owe those Luddites a debt because it was their infuriating scepticism and complacency that gave our thoughts their momentum."
I have no doubt Paul will be happy to see your soapbox comment here Glen - Mr Anderson should be rightly lauded as you have done, and yes, which of our feckless political leaders and so called 'captains of industry' understands what you have so brilliantly articulated?
I wonder if the likes of Neil Woodford and his new Patient Capital Trust are going to be a part of the solution? As a result of your comment, I'm going to take a closer look at his investment trust. I just hope he's not a holder of Optos and has also acquiesced to the takeover!
Hi Glen
Thanks for the background but I don't understand why "this shows a lack of ambition with UK Plc". Surely it just shows a lack of long termism of the shareholders in these companies. But also perhaps it just make economic sense.
I know nothing about the company but if I was started say with £1m and they have turned that into £260m in 23 years then surely an investor is going to take the money and move on to the next investment.
What would you propose to prevent Optos from being taken over by a foreign entity and staying a public company?
I agree about Boohoo compared to Asos its very good value, just dont understand Asos sp which is about 75 PE even after profit warnings and slower growth forecasts?