Small Cap Value Report (27 Jan 2015) - AFR, BMK, CPR, SPH

Good morning.
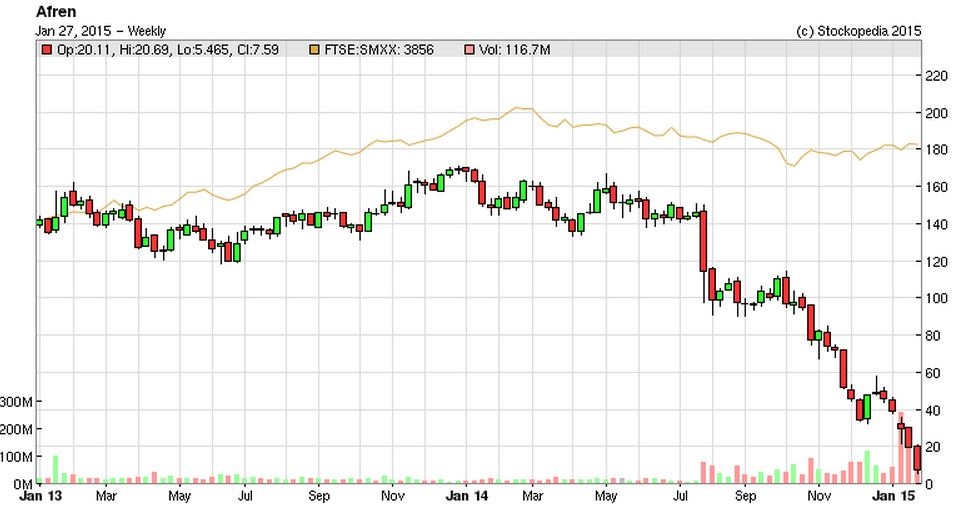
Afren (LON:AFR)
Share price: 8.0p (down 55% today)
No. shares: 1,108m
Market Cap: £88.6m
I don't normally report on the resources sector, but there are lots of interesting things going on at the moment - as the plunging oil price is throwing up risks, but also opportunities. So I will mention the odd one. The opportunities are going to be the companies that survive this period of low oil prices, where share prices could rebound strongly once the oil price is moving back up again. So cashflows, hedging, balance sheets, terms of bank debt & bonds, etc, are the crucial elements to consider right now.
Review of capital structure - the title of the RNS alone should be enough to frighten shareholders. Key points seem to be;
- cash is now tight
- negotiations are underway with providers of a $300m debt facility
- $15m of debt interest payments due on 1 Feb 2015 may be deferred
- bond holders are mobilising - have formed an ad hoc committee (to represent their interests)
However, the killer one is this;
"...there is an equity fundraising requirement which is likely to be significant and in excess of the Company's current market capitalisation".
So who knows what is going to happen next? It hinges on whether existing & new investors are prepared to stump up fresh cash for equity.
There is also ongoing discussions about a "possible combination", i.e. takeover, by Seplat Petroleum Development (LON:SEPL) , a Nigerian oil company which listed on the London market in Apr 2014, and has a market cap of £675m at 122p per share.
My opinion - when companies get into financial distress, effective control passes from the equity holders to the debt holders. If debt holders play hardball, then equity can end up being worthless (if they seize control by forcing it into Administration). At the very least, equity holders here are likely to be heavily diluted. Or it could go bust.
I'll be giving this one a miss. Although it might be worth another look once they have raised some fresh cash, but who knows what price that might be at? 5p? 3p? 1p? Massive dilution appears inevitable.
I think you would need to be a sector expert to even consider getting involved here, or just a gambler. It's a good reminder that, if the capital structure is wrong, a share that drops a lot can keep dropping. Cash is king at the moment for oilcos. I hope readers are incredibly careful if you do decide to catch any falling knives in this sector, and doing really thorough research is more important than ever. There will be fortunes made and lost this year on oil shares, that's for sure.
Benchmark Holdings (LON:BMK)
Share price: 95p (down 14% today)
No. shares: 219.3m
Market Cap: £208.3m
I've looked at this company a couple of times, and saw a presentation from management last year, but must confess that I don't really understand the company, nor have any idea how to value it. It's difficult to value, as it has limited track record as a Listed company, and has made acquisitions, so you're really having to rely on broker forecasts to value it, which are notoriously unreliable.
Final results - for the year ended 30 Sep 2014 are out today.
The company grew turnover from £27.5m to £35.4m, but recorded a loss before tax of £1.4m (vs. profit of £4.9m in 2013). They say this is in line with market expectations.
The issue seems to be that the company has profitable trading activities, but then spends that profit on product development, as set out in the following table from their results today;
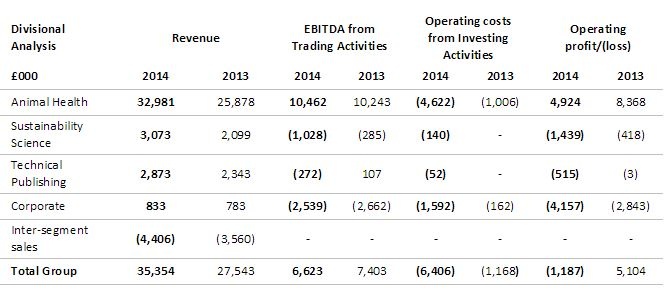
The animal health division is the profitable bit, making £10.462m positive EBITDA, but it has ramped up "investing activities" that seem to be expensed through the P&L, over four-fold to £4.6m, giving a reduced operating profit of £4.9m for that division.
The other two divisions are small, and loss-making.
A further breakdown is then given of the £6.4m "investing activities";
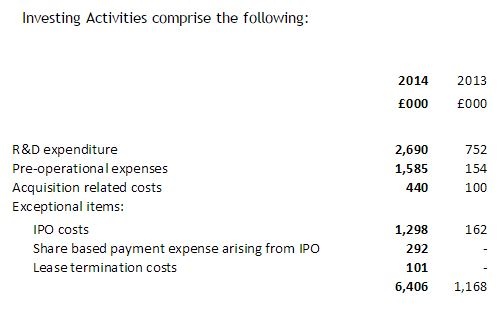
I'm a little confused as to why they didn't capitalise the first two items in this table?
Balance Sheet - looks fine, with net tangible assets of £29.4m, and the current ratio is very strong at 3.42, including a healthy net cash balance of £16.3m.
Subsequent acquisitions - note that a substantial, £70m fundraising occurred after the year end, to finance two acquisitions. That is almost a third of the current market cap, and explains why broker forecasts show a large jump in turnover and profit in the current year.
My opinion - unfortunately, there are too many moving parts here for me to form any meaningful view. Valuation all hinges on how well the various constituent parts of the group perform, and how much they then decide to reinvest in R&D. So the profit figures are moveable, and hence it's very tricky to decide how to value it.
This is a share where there's no alternative to doing the detailed research on its products & markets. So a cursory look from me won't really add any value at all, I'm afraid - I've no idea what it's worth, because I don't know what sustainable profits could be generated.
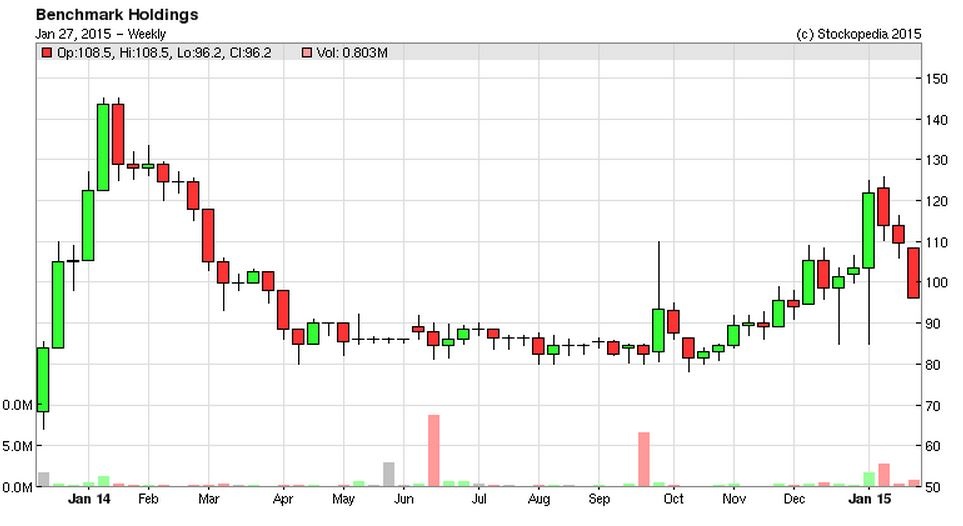
Looking at the chart, it found very strong support at 80p last year, so if it drops to that level again, and holds it for a few weeks, then it might be worth a dabble, as a trade, perhaps?
Carpetright (LON:CPR)
Mkt Cap: £304.6m at 449.5p per share
More evidence of good consumer spending in the UK, with an impressive performance from Carpetright, delivering 7.5% LFL sales in the 13 weeks to 24 Jan 2015.
Even Europe managed a positive LFL sales performance, in local currency, of +1.7%, but the depreciation of the Euro turned total sales negative (in sterling terms) at -6.0%.
I'm surprised that the company only confirms full year expectations, as I would have expected a strong sales increase to feed through into profit out-performance.
These shares have looked irrationally expensive for the last ten years - nobody has ever managed to explain to me why this low margin retailer of carpets should be rated on a PER typically of 30+. It remains a mystery.
Sinclair IS Pharma (LON:SPH)
Mkt Cap = £179.1m at 36.75p per share
A very detailed trading update today says that the company is trading well, and in line with the Board's expectations.
This company seems to have transformed itself from loss-making to decently profitable. It makes skincare pharmaceutical products. The Directorspeak today sounds good, with them saying that it has, "multiple avenues for continued high growth across several products and territories, while prospects for the US provide an opportunity to take the company to a new level".
Sounds quite interesting, so this one might be worth doing some more research on, possibly.
There's a fair bit of debt, and no divis though, which puts me off a bit.
I'll sign off for today. See you tomorrow!
I see Afren is down to 6p now. This is why I'm obsessed with balance sheets - if your balance sheet unravels for any reason, then the shares are toast.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions. A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

13 comments
I sold my 4.5p buyin for slightly over 9p so I'm happy. What a trade! Only held for 4-5 days.
I think afren is worth a play, just look at that book value per share. It's not investing or trading, a gamble/punt but if it turns around what a contrarian play this would be.
Paul, maybe the R&D expenditure is written off because it's to be a recurrent feature of BMK's business model?
From the BMK Chairman's statement:
"Your company has had a busy and productive year and I am pleased to be able to present this inaugural report and accounts as a public entity. Benchmark has exacting but achievable strategic ambitions within a substantial global market for animal health products and services. Whilst there is a long way to go for the business, major steps have been taken since the IPO in December 2013 to deliver these objectives both in terms of the products and services that Benchmark is bringing to market but also in the judicious acquisition of businesses and technologies that complement the Company's existing operations.
The various Executive Director's reports contained further in this document will provide you with detailed explanations of the strategic, operating and financial performance of your company during the year under review and so I will confine myself to reporting on the significant highlights and provide shareholders with an insight into the Company's tactical rationale.
An important component in understanding Benchmark's long term objectives is to note how the Income Statement is divided into Investing Activities and Trading Activities. The Investing Activities category reflects how the Group's financial resources are devoted to developing and expanding the pipeline of proprietary animal health products and services. The Trading Activities category reflects how these products and services, once fully developed, are performing in their various markets. We are committed to investing significant resources to secure the long term trading prospects for the business and, as mentioned later in this report, our pipeline of products currently in development has an estimated revenue potential in excess of £350m. We will continue to invest significantly in this pipeline over the next few years whilst ensuring that the revenue producing divisions are prudently managed so as to achieve their growth-oriented targets."
The talk is all of the long-term opportunity with resources being poured in continually over the next few years. Maybe this role of funder appeals to some but is there not a whiff of a "story stock" about all this?
dangersimpson that's a very good point and i appreciate you taking the time to make it. I was being a bit lazy.
Sinclair IS is also 'up for sale' potentially so may have some bid premium in the price. On the other hand it is more likely that any serious offers would be higher than the current price. All IMHO.
There was an excellent post by "orangetree" on Stockopedia about seven weeks ago:
http://www.stockopedia.com/content/which-oil-producers-will-survive-from-falling-oil-prices-88623/
AFR are said in this article to have a production cost of US$67 a barrel (about 40% above the present price of Brent/NYMEX) and enormous debts.
The writing was very clearly on the wall.
Also, FT Alphaville "Markets Live" a few days ago had included some very cautionary "grey" (analysts' comment) on AFR which was promptly dismissed on one bulletin board as "total nonsense"
If people have a death wish with their money, what can you do?
Thanks Imran missed it.
Can someone explain the RNS today by Gresham Computing (LON:GHT) regarding "Proposal for an amendment to the Share Option Plans". http://www.moneyam.com/action/news/showArticle?id=4965430
Is this (as I fear) the directors increasing their share options plan, for no apparent reason?
Hi Paul,
You say cash is king and you're right, but Afren says it had $235m cash balance at 31st December in it's RNS, but can't afford to pay $45m to bondholders and banks 4 weeks later. Even Stocko says it's got lots of cash. But it isn't really cash because it's tied up in other stuff. I think any bottom fishers have to look at debt, which is Afren's undoing. Afren's idea of liquid net cash isn't liquid at all and now they are being squeezed by the bondholders (sounds painful and probably is).
So be careful of reported cash figures because they don't seem believable especially in this case.
Paul,
The Afren (LON:AFR) statement this morning made me look back through last year's accounts to see whether there were any obvious warning signs about the firm's financial weakness (there were, if you looked at the accounts in the context of a falling oil price).
One thing I did notice was that Afren claimed to have a 'strong balance sheet' in its Q3 statement at the end of October. I might adopt your rule of thumb about such claims...
Roland
Disclosure: no position in AFR
Paul,
HAve you taken a look at RBN recently? P/S around 1 but PE 7. Yield over 3%. Strong balance sheet. I have never bought this company although it is clearly well run. The takeover worried me as some management teams manage well but cannot handle acquisitions. I also question the sector as everytime I come away from the supermarket I cannot help but feel there should be less rather than more packaging in this world! Anyway I know you were keen on them and just wanted to highlight them.
All the best
Guy
Hi Guy
I think Paul covered Robinson (LON:RBN) on Friday: http://www.stockopedia.com/content/small-cap-value-report-23-jan-2015-sal-rbn-90736/
Best wishes,
Imran.
P/S around 1 but PE 7. Yield over 3%.
Be careful about quoting the P/E from the StockReport without looking at the source of this. The StockReport uses fwd P/E which is probably the best compromise overall. However for small companies without much broker coverage this can be highly dependent on one or two, sometimes biased, opinions. There is no substitute for looking at the outlook statements and trading history of the company and determining if the fwd EPS is likely to be reality.
For Robinson (LON:RBN) this P/E is based on a forecast 2015 EPS of 20.1p from WH Ireland. So when valuing the company on the fwd P/E you have to assess how likely it really is for the EPS to jump 57% when the outlook is "much more challenging". They suggest there will be some growth due to an acquisition however acquisition EPS growth is the lowest quality and you really shouldn't pay a high multiple for it.
If you are valuing the business on an ex-organic-growth multiple on 12.8p EPS you'd probably call the current price slightly overvalued. To believe that it is undervalued you need to have a good idea of where future organic growth is going to come from despite the much more challenging outlook. Personally to invest here I'd want a much bigger margin of safety from either a much lower share price or a clear and believable strategy for organic growth from the company.