Small Cap Value Report (27 Jul 2015) - DIA, MYSL, XPP, FEVR

Good morning/afternoon!
I'm running a bit late today, so please refresh this page, as I'm adding to the article throughout the afternoon. I've been dog-sitting for friends in London over the weekend, and there have been a few accidents, so I'm now expert at carpet cleaning!
Dialight (LON:DIA)
Share price: 488p (down 11% today)
No. shares: 32.5m
Market cap: £158.6m
Interim results to 30 Jun 2015 - this industrial LED lighting company warned on profits on 10 Jun 2015 - which I reported on here. In that update the company said 2015 profits would be significantly below market expectations, but didn't quantify how much. I concluded at the time that Dialight seemed "a can of worms, with possibly more bad news to come out", which looks to have been a sensible conclusion.
Results today look bad. Key points:
- Turnover for H1 rose 14% to £86m
- Underlying operating profit collapsed - down 74% to only £1.7m
- Underlying EPS only 5.4p
- Interim dividend has been passed
- Moved from net cash into net debt, of £8.0m
Balance Sheet - overall this is still strong, but the main item which has consumed cash, and caused the move into net debt, seems to be a big increase in inventories, up £12m compared with a year ago, but up £4.1m in the last 6 months.
Significantly rising inventories is a red flag, so would need looking into, as it could be a precursor to a write-off of obsolete stock at the year end perhaps?
A useful check is to see what the stock turn is like. In this case, cost of sales from the P&L for the 6 months was £61.1m, so I would expect there to be no more than say 2 months' sales in stock, so about £20m, and hopefully less. However in this case, stock is much higher, at £36.5m. So that is certainly a concern.
Given that there is a new CEO conducting a strategic review (results to be announced in Oct 2015), then there has to be a heightened risk of him doing a "kitchen sink" job, and make a big provision against slow moving stock perhaps?
The net debt positions doesn't look to be a problem - the company says it has headroom on its banking covenants, and in any case I imagine the bank would be fairly relaxed, given the overall balance sheet strength, so I'm not worried over net debt, at the moment.
Operational problems - so why have profits dropped so much? Problems with the oil & gas sector are mentioned, but also internal problems:
The Group has previously reported during H1 2015 that it was incurring a number of operational inefficiencies at our principal plant in Mexico. We have also identified issues with platform product design, design for manufacturing and global commodity management. A team has been selected from the best operations resource within the Group to relocate to Mexico to remedy the issues identified.
This is a worry, because surely these problems are fairly basic issues when running a company? Therefore I can only conclude these issues are down to poor management, which might take a while to sort out.
Outlook - there are various positive remarks in the narrative about the opportunities available, etc, but the most specific remarks sound rather mixed to me:
There is an increase in the number of new sales opportunities in our H2 2015 pipeline, however there is uncertainty remaining on the timing of projects. We are not anticipating any recovery from the oil and gas sector in the balance of the year. The focus for the sales teams will be on our other target vertical markets. Operational issues remain in the Group, although a number of actions have begun to remedy them.
Dialight has a very strong brand, notably in the US market that has been built on products that stand apart from the competition and there is still an immense global market opportunity.
Therefore it sounds to me as if there could possibly be one more profit warning left to come, later this year perhaps? That's just a hunch.
Valuation - Broker forecast consensus of 31.5p EPS for 2015 looks pie in the sky, given that H1 was only 5.4p, so it would require a heroic improvement in H2 to achieve that. Although H2 historically has been stronger than H1.
So I imagine 2015 forecasts are likely to come down again, possibly quite a lot? I wouldn't want to hang my hat on anything more than say 10-15p full year EPS.
So how do you value the company? It's difficult, as it depends entirely on whether, and how much, you think the company can recover in future. This might be a one-off bad year, with improved performance to come next year & thereafter perhaps? Or this lower level of profitability could be the new normal? We don't really know at this stage. Therefore valuing the company involves quite a bit of guesswork - not something that appeals to me, and I would always err on the side of caution.
My opinion - the share price still looks too high to me. Also with divis now gone for the time being (they say divi policy will be decided in the strategic review), it's less attractive to tuck away and await recovery.
Personally I'd only be interested in taking a risk on this company if the PER was in bargain basement territory, which it really isn't at the moment. My worry is that the company might be facing more lasting problems, with increased competition & hence pricing pressure, which is alluded to in the narrative.
So it's not for me at this level. If the share price were to halve from here, then I'd take a closer look. The 2-year chart is showing an unrelenting down trend, of anaemic recoveries interrupted with profit warnings. It doesn't sound to me as if the company is out of the woods yet, based on today's announcement. What do you think? Comments in the comments below please.
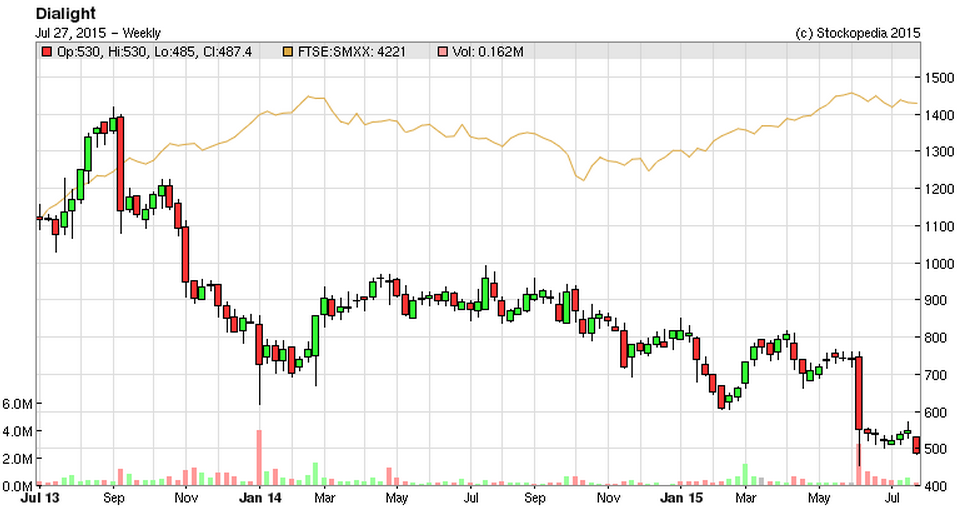
EDIT: I see Dialight (LON:DIA) shares have dropped further, now down 16% on the day at 460p. They've got further to fall too, in my view.
MYSL
Share price: 46p (up 15% today)
No. shares: 150.6m
Market cap: £69.3m
(at the time of writing, I hold a long position in this share)
There are 3 announcements today from this company, as follows:
Chairman appointed - Iain McDonald (stated to be a former top ranked retail & e-commerce analyst) takes up the Non-Exec Chairman role.
Director buy - the Non-Exec Chairman (above) has spent £27k buying shares at 44.9p. Interesting, but not a significant amount of money. I see Director trades increasingly as red herrings these days (unless serious amounts of money are involved), since they are so often just done for show.
(Note that the CEO of MySale spent £3m buying stock at 80p, eight days after a previous profit warning, which clearly wasn't a very smart move.)
More interesting is the new Chairman's share options package (unusual for a Non-Exec to get any share options), which certainly gives him a big incentive to help push the share price up substantially, as then some big in-the-money options will vest, as follows;
Alongside his appointment, the Company has today granted Iain McDonald 3,000,000 options over the ordinary share capital of the Group each with an exercise price of 53p (the "Options"). 1,000,000 Options will vest when the Group's share price reaches £1.50, a further 1,500,000 shall vest when the Group's share price reaches £2.26 and a further 500,000 shall vest when the Company's share price reaches £2.75.
Trading update - it looks as if the company's previously poor performance is starting to turn around;
In the year under review Group revenue grew by 5% to approximately A$235 million [PS: about £110m] and for the second half of FY2015 EBITDA was breakeven. As previously announced, following the challenging first half to the financial year, the Group took action to improve Gross Profit margins, and a reorganisation to reduce fixed costs. As a result the Group has seen momentum build during the second half which resulted in the Group returning to underlying EBITDA profitability in the fourth quarter. During the second half, management has increased the proportion of own-buy activity and investment into inventory to improve brand selection and increase gross profit margin.
That's quite a good turnaround, as looking back at the last interim results, it looked a bit of a basket case, making an underlying EBITDA loss of AUS$11.4m (about £5.4m) in H1, so to get to a run rate of breakeven/small profit in Q4 looks quite good - although seasonality might play a part in that - most sales are made in Aus/N.Zealand.
Balance sheet - this was strong at the last interims, and the company today says it has A$40m cash. This is well down from 6 months ago, but they say that is due to buying in more stock (previously it took in surplus stock on a sale or return basis).
Outlook - this sounds quite positive;
The Group anticipates that the positive momentum of the second half FY2015 shall continue into the current financial year with increasing revenues, improving gross profit margins and careful control of costs delivering an expected return to EBITDA profitability in the coming year.
My opinion - this company has, so far, been a big disappointment for shareholders. Performance has been poor (little growth, and increasing losses), and it was far from clear that the company had a viable business model at all.
I think today's update changes things. Sure, it's not properly profitable yet (hence them mentioning EBITDA), but it has plenty of cash, and seems to have a much better strategy now, to keep a lid on costs, and improve margins by buying in stock, rather than taking in the dog-ends from other fashion retailers.
This very much chimes with my experience in the sector - my former employer in the 1990s, called Pilot, opened a handful of factory outlet shops, which were initially a disaster, because they were just clearing dead stock, often at below cost price. I remember being horrified at the losses when doing the management accounts.
However, the buyers then hit on the idea of supplementing dead stock with specially bought-in ranges, which were still bargains for the customers, but had a much better gross profit margin. The impact was astonishing - suddenly the biggest loss-making shop became the most profitable shop (out of about 100) in the whole chain. Not only was the margin much better, but the more appealing bought-in stock ranges also drew in far more repeat customers too. So a double bonanza of much higher sales, at much higher margins.
It sounds to me as if MySale have come to exactly the same conclusion, and are already benefiting from this effect. For this reason, I think this share is now potentially interesting, as a GARP share (growth at reasonable price).
Strengthening the Board, and dangling some lucrative options in front of the new Chairman is a potential catalyst. Remember that Philip Green (retailing mogul extraordinaire!) owns 22.1% of the company (through Shelton Capital), and Mike Ashley (sportswear retailing mogul!) owns 4.8% through Sports Direct. So whilst no guarantee of success, having those guys behind you will certainly be a deep pool of experience & I imagine ear-bashing for the CEO by telephone, if the strategy isn't right.
It's clearly still a very speculative share, but the signs are starting to appear that it might actually get somewhere, in my view. So since the valuation is cheap for an internet retailer, and it has cash in the bank, then I think this could be an interesting, albeit speculative, recovery stock.
There's an article in today's Evening Standard which gives a bit more info, and suggests that Green & Ashley have been helping guide the strategy back to something more commercially viable.
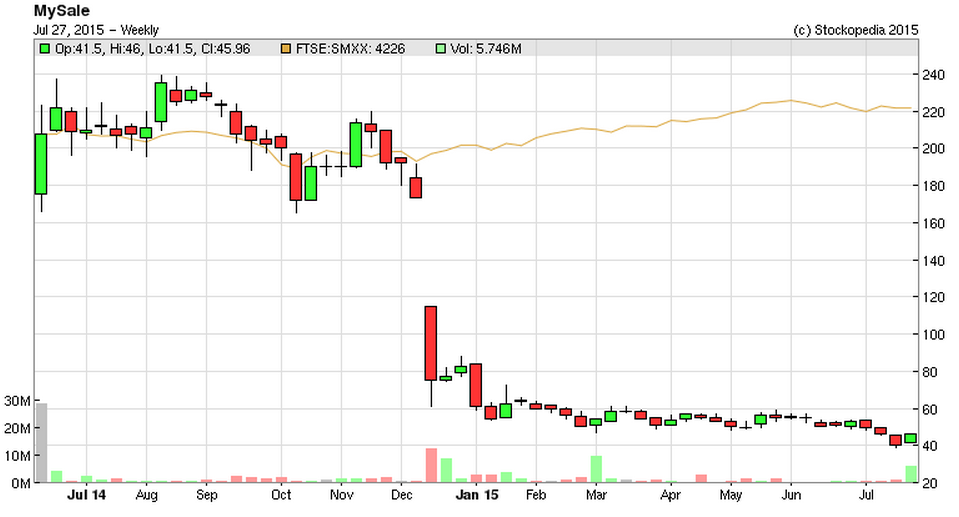
Take a look at this chart - yet another IPO that went disastrously wrong. Makes you wonder why anyone buys IPO shares, since the failure rate is unbelievably high. Memo to brokers - if you keep floating over-priced junk, then sooner or later you won't have any buyers.
XP Power (LON:XPP)
Share price: 1599p (down 0.2% today)
No. shares: 19.0m
Market cap: £303.8m
Interim results to 30 Jun 2015 - key points;
- Revenues up 7.4% to £53.9m for the 6 months
- Operating margin fell 90 bps to 23.6%
- Hence profit before tax only rose 3.3% to £12.6m
- EPS fell 0.8% to 50.1p, due to higher tax charge cf last year
- Interim divi up 2p to 27p
- Order intake up 11%
- Acquisition of 51% of S.Korean company
Outlook - sounds positive, although I don't see any comment on profits vs market expectations:
While the global economic outlook remains uncertain and exchange rates are volatile, following a strong first half, the second half of the year has started well and we are encouraged by our record order intake and strong backlog. This gives us confidence that we should be able to continue to grow revenues in the second half of 2015 as designs won in 2014 and prior years enter their production phase.
Balance sheet - looks very solid, no problems here at all. They have scope to do more acquisitions, which is mentioned several times in the narrative, so more earnings growth is likely from bolt-on acquisitions, which could drive the share price higher.
Dividends - there has been a very good progression of divis over the last few years, and the yield is good, currently about 4.2%.
StockRank - very high at 96.
Valuation - looks reasonable to me - this looks like a QARP (quality at reasonable price) company;
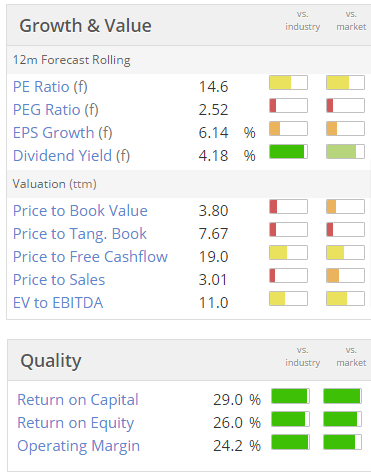
My opinion - the figures look good here. Now the $64k dollar question is what the future holds? I note that earnings growth has been somewhat pedestrian in the most recent few years. Also those juicy profit margins could come under pressure from competitors perhaps?
Overall though, it ticks a lot of my boxes, and is certainly worthy of doing more research, to better understand the markets and products which it sells.Fevertree Drinks (LON:FEVR)
Share price: 368p
No. shares: 115.2m
Market cap: £423.9m
Interim results to 30 Jun 2015 - this is the premium mixer drinks (mainly tonic water & ginger ale) company which floated in Nov 2014, and has seen its share price rise steadily since.
The company intrigues me, as what they've done - in creating their own niche for premium mixers - is very clever. I did an initial write-up about the company recently here on 8 Jul 2015, and afterwards I had a read through the company's admission document. Very interesting reading it makes too. We had an interesting discussion about the company in the comments section on that day, so that's also worth revisiting.
The bull case is basically that the product is very good, and that bars/restaurants are not likely to stock multiple premium mixers. Instead they will just stock Fever Tree, so it could become a land grab for a new niche.
I might have tried this product in a G&T at the Savoy a few months ago, but to be honest I couldn't really tell any difference, but we'd had quite a few by that stage of the evening, for a friend's birthday party. One of my friends - who likes designer bags, and gucci shoes, that type - was raving about Fever Tree. So it definitely appeals to a trendy, affluent and perhaps rather narcissistic/vain type of person. Personally I think paying more for the mixer than you pay for the shot, is bonkers, but there we go.
The bear case is that at £423.9m, the market cap is too high, and that the product might not grow as fast as expected, and could attract copycat competition, thus squeezing margins, and clipping the rapid growth rate.
I'm not sure which is right, but am leaning more towards the bear case, than the bull case at the moment.
Revenue - as expected in the recent trading update, which said that H1 turnover would be "approximately £24m". It's actually come in at £24.1m, so good to have a little extra. That's a fantastic 62% organic growth rate in the top line.
Although I note that the run rate per six months is slowing considerably (although there could be some seasonality involved), i.e.
H1 2014: £14.9m
H2 2014: £19.8m (sequential growth of 32.9%)
H1 2015: £24.1m (sequential growth of 21.7%)
So the sequential growth rate appears to be slowing. Or, as I say, it might be because maybe H2 is seasonally stronger?
Adjusted EBITDA - normally I would say that this measure is bogus, but actually in this case it looks fine - because there is only a minimal depreciation charge, the amortisation charge can be safely ignored, and interest charges will soon be gone since the company now holds net cash and can hence pay off the residual debt (assuming no punitive early settlement charges).
£7.2m adjusted EBITDA is therefore very impressive - a stonking, super-normal profit margin of 29.9%. The big question mark of course, is whether that profit margin can be maintained, against competitive pressures in future?
If you take off a notional say 20% Corp Tax, and divide by 115.2m shares in issue, then that arrives at EPS of about 5p for the six months, which is slightly ahead of the 4.44 diluted EPS figure that the company reports today.
Valuation - broker forecast (raised in Jul 2015) is for 9.1p for the full year 2015. That looks conservative to me - growing this fast, I would expect H2 to be better than H1.
The 2016 broker forecast of 10.4p also looks conservative to me, so providing nothing goes wrong, I'd expect to see those figures upgraded to maybe 10-12p this year, and who knows next year - maybe 15p? At 368p that would put the company on a current year PER of about 33, and 2016 PER of about 24 - which actually doesn't look insane, for a fast growing company that has created a new niche, and is growing strongly, internationally.
My opinion - this is a tricky one. With my value hat on, I'd say it's way too expensive. But with my growth hat on, I can see that if the bull case is watertight (i.e. no competition gains traction), and growth continues apace, then the shares could end up being a good bet.
So it's a straightforward bet on whether you think the growth and margins are sustainable. As someone mentioned in the comments section, there is also the possibility that a major drinks group might pounce, and take it over. Then drastically scale-up operations within its existing factories & distribution network.
Overall, I can see merit in both the bull and bear cases, so will say I'm pretty much neutral on this share.
Right, I'll sign off for the day. See you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in MYSL, and no short positions. A fund management company with which Paul is associated may also hold positions in companies referred to.
NB. Please note these reports are just Paul's personal opinions, and are not share recommendations or financial advice)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
Paul, I did buy some DIA in February, but due to the possible problems you flagged up in your April report I managed to get out unscathed. I am very grateful to you for keeping us on the straight and narrow!
Also, your covering of XPP is appreciated and avidly read. I bought some a while back round about the 1,000 mark and have done well probably more from luck than judgement. Their divi comes in handy and the good StockRank helps give us confidence.
As always thanks for your input.
Cig, yes, I'm also interested in what clients and employees think. For the latter, a site such as Glassdoor can often tell you a lot. Even Google Alerts sometimes dredges up useful information from unexpected sources. Major suppliers should also be covered as well as developments in other or related markets that could well impact on the company concerned or be followed in its particular markets (this is, imo, something very often overlooked). For me, time is very much a limiting factor, as it is for many, but I find that once the work of identifying sources of info is done thoroughly, then I'm more than halfway there in getting ahead of the game.
Thanks Brian,
One of the lessons I have learned from my (many, and sizeable) investing mistakes, is that getting your information mainly from the company you have invested in, is usually a mistake - because they tell you a sanitised, optimistic view.
These days I'm interested in the interim and final results statements and narrative, but spend a lot of my time digging around for views about the company and its products from third parties.
For most sectors, I conclude that I just don't know enough about the sector to make an informed decision. So best to stick to what you know & understand.
Regards, Paul,
Hi Paul -
I agree with your view and would add Trading Updates and IMS s as requiring close reading. Read carefully and with good judgement, they are generally good predictors of where a company is likely to be at the next reporting date.
Paul, for me it's just as important to identify and monitor specific sources of information on companies in which one is invested, sources which might include trade publications or independent market analysis or all kinds of other specific information, sources that could provide very specific and timely indications of progress, setbacks or developments and that could put one ahead of most other investors, besides announcements and results from the company itself, and comment by other investors and investment publications. The reason I stress the former is that it's invaluable in providing what I'd call an "owner's perspective" on how a particular company is doing, something I find necessary to complement (and sometimes very much oppose!) the "investor's perspective" that is built up from sources such as Stockopedia and your SCVR, often mainly based on historical figures. Imo, both perspectives are needed in order to make good investment decisions but to cover stocks adequately in this way, one needs to deliberately limit the number of stocks held, I'd say to between 10 and 15, which is a useful exercise in itself as one effectively forces prospective investments to compete for investment money.
I follow the same philosophy, but a shallower version, that is I get the "owner's perspective" -- which I would call stakeholder's perspective, I'm also interested in what clients and employees think -- from googling or side channels of company data or secondary sources. This is easy (a few hours of work to research one company/idea) but imprecise, so it is a good match for a very diversified portfolio (which dilutes the inevitable errors). There's only so much research one can do from behind one's desk... It may be one of those things where 20% of the work gets you 80% of the result.
The point I'm making here is that people should not be turned away from taking a broader views because they think they can't do it in sufficient depth.
CREE has been the market leader in high powered LEDs (and most SiC electronics) for some time now, but an increasing number of competitors seem to be emerging http://www.bloomberg.com/news/articles/2015-01-12/cree-sees-how-many-suits-it-takes-to-block-rival-led-lightbulbs.
They're probably a good company to follow if you want to learn more about the LED lighting space generally.
Domestic LED lighting seems to be a rapidly evolving technology. The domestic bulbs have gone from quite poor light output to fully competitive with halogen in not much more than 5 years.
So I presume it's the same in the industrial sector which Dialight occupy.
Now anyone investing in a rapidly evolving technology needs to pick the right company and get out at the right time. Think of Nokia & Blackberry v Apple & Samsung.
Whether or not this analysis is correct, I would certainly want to understand the marketplace in more detail before taking a punt on this. A quick look at google shows there are other LED industrial lighting manufacturers. Trying to work out which ones have a technical advantage in one for the "too difficult" pile.
Dialight (LON:DIA) don't make the actual leds, they just box them up, so you're not exposed to bad (good) technology as they can pass through advances from their suppliers. Of course, it means it is a relatively low margin commodity business.
There will also be circuits to power the LEDs. They don't just run on 230v.
So I suppose there's some skill in the design and integration of those circuits, but this would also be the type of thing any bright electronics engineer could work out.
Therefore I agree it could still work out as a low margin commodity business.
With no room for the kind of operational issues reported.
You don't want the electronics engineer to be too bright, because they'll home cook the power conditioning circuitry, because it's fun, instead of using off-the-shelf led power ICs, of which there's a rich ecosystem.
Still integrating parts into end products is a perfectly valid business to be in, but as you say they must not cock up manufacturing. There's possibly an investor perception gap as well: some investors may see or have seen them as blue sky, and misprice them accordingly. And they have commodity industry exposure, which may be tough for some time. Overall may be a better short than long at the moment.
FEVR
Coming from a slightly different direction I also estimated a forward PER of 33. Abcam, I estimate as a middling PER of 31. There is a type of share that has a very wide 'moat' which justifies these types of PERs.
I remember doubling my money on ARM in about a year and thinking they were too highly valued, despite knowing that it was the legion of software folks skilled in their programming that were the game changer when combined with their low-power consumption. I'm not making that mistake again.
Nicely balanced article.
apad
Good, balanced report on FEVR Paul. I'm very much in the bull camp as the chance to own an extremely fast growing global market leading consumer brand doesn't come along very often. I agree with your comments about the broker estimates being way too cautious.
Ha! Re. Fevertree Drinks (LON:FEVR), maybe that 'perhaps rather narcissistic/vain type of person' will no longer be a friend if & when they read that post, Paul!
In 2009 I looked at IQE and DIA as a play on the promising LED lighting market. In the end I kicked myself for having plumped for IQE, as I felt it had a strong design and technology moat and in addition a big opportunity to provide more complex chips to the exploding smart phone market. More fool me as DIA subsequently ten bagged and IQE five. I still hold IQE so its really a 2.5 bagger for me so far.
However now the world is different and I fear the competition will hurt DIA now, at a time they are struggling with internal in-efficiencies. I think it highly likely there will be a kitchen sink exercise. Given the tough market for small caps I could see the PE reducing to as low as 5 when the full year results are published. Like you I have no interest until the full year numbers except possibly as a small short.
On the latter point I find it emotionally hard to short as I instinctively want to support companies I have invested time and money in, however the lunatic global fiscal position could play havoc with equity valuations and I feel one should start getting some protection in the portfolio, perhaps ftse index short bets would be easier if not to expensive.
Apologies - the above is all rather rambling and unstructured but hopefully of some interest.