Small Cap Value Report (27 Mar 2017 - Part 2) - YOU, ELCO, KBT

Good afternoon!
Paul has already written a Part 1 article (at this link) which covers Bioventix (LON:BVXP), DP Poland (LON:DPP) and Spaceandpeople (LON:SAL).
In this article, I'm covering YouGov (LON:YOU), Elecosoft (LON:ELCO) and K3 Business Technology (LON:KBT).
Cheers
Graham
YouGov (LON:YOU)
Share price: 263.5p (+0.4%)
No. shares: 105.1m
Market cap: £277m
Some strong percentage growth numbers here:
- Revenue growth of 24% (2016: 15%) - Constant currency growth of 8%
- Adjusted operating profit1 up by 33% to £5.7m - Constant currency growth of 14%
- Adjusted profit before tax up by 27% to £6.3m
Paul has previously analysed the discrepancy between YouGov's adjusted and statutory numbers (see here) and today's results again show a large gap.
Statutory PBT is also rising strongly, but at the lower level of £2.5 million for the six month period to January 2017 (versus the £6.3 million adjusted measure given above). And FX gains have played a big part in these results (so are unlikely to be repeated).
The gap between the numbers above arises primarily from £3.1 million of amortisation, broken down as follows:
- Consumer Panel (£1.05 million)
- Software and Development (£1.65 million)
- Customer contracts and lists (£0.3 million
- Patents and trademarks (£0.1 million)
YouGov added £1.6 million of software & development in the period, and amortised £1.65 million.
In the prior six-month period, it added £1.6 million and amortised £1.7 million.
In the period before that, it added £1.3 million and amortised £1.5 million.
If it simply expensed all of this, the statutory profit figure would barely change.
But the adjusted number would collapse, since it would start to reflect these costs!
Data products
It's a shame we have to concern ourselves with this, since the underlying business does appear to be doing really well.
Yougov's brand intelligence tracker ("BrandIndex") helped its Data Products division grow revenue by 43% (24% at constant currencies), and operating profit in this division grew by 50%. This is perhaps competing with similar products offered by Brainjuicer (LON:BJU) ? On a standalone basis, this division looks like it would be worth a premium rating.
Outlook
Upbeat comments:
Current trading is in line with the Board's expectations and we remain confident in our ability to achieve our ambitious goals and deliver shareholder value. Within Data Products and Services, our pipeline of opportunities for BrandIndex and Omnibus remains strong and the growth potential of the newer YouGov Profiles is significant.
My opinion
I'm not sure what the attraction is in terms of investing at the current share price, and the Stockopedia ranks suggest some caution might be required too (although the Quality and Momentum scores are very good):
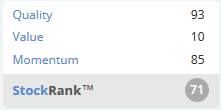
It is a well-known name and is performing solidly, but how can it be worth nearly £300 million?
Elecosoft (LON:ELCO)
Share price: 42p (unch.)
No. shares: 77.1m
Market cap: £32m
My first time looking at this construction software provider (formerly known as Asta Development).
It's another highly-rated share, though I can see the potential in terms of providing standardised solutions to the construction industry worldwide. They have over 100,000 users and appear to be embedded within the industry.
The growth rates are impressive, too. And the accounts are a straightforward demonstration of how a software company should present its activities, without any funny business, which helps to build trust.
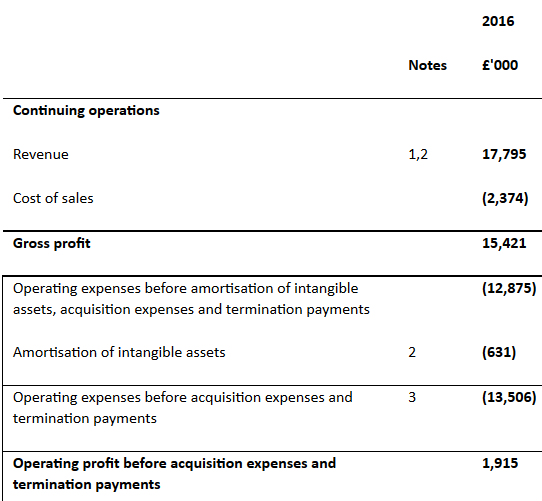
Ok, there are a few adjustments. But operating profit emerges at £1.6 million after all expenses, not too far off the £1.9 million figure presented above. And note that the company doesn't emphasise pre-amortisation profit measurements. It capitalises about a quarter of R&D and is explicit about that.
Outlook
Nothing too specific in the outlook statement, but the Chairman is "confident" the company can meet its challenges and believes it is "fast becoming a truly international provider of market leading construction software applications".
My opinion
Potentially interesting. I haven't discovered any red flags yet!
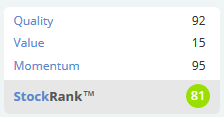
1.7p of EPS means that the market cap is not cheap but there is real cash flow (backed up by a dividend) and it sounds like it it could be one of those few companies with genuine promise as an SaaS provider.
K3 Business Technology (LON:KBT)
Share price: 254.5p (-0.2%)
No. shares: 36m
Market cap: £92m
This company had a big profit warning in January, so investors were already braced for a tough set of results today.
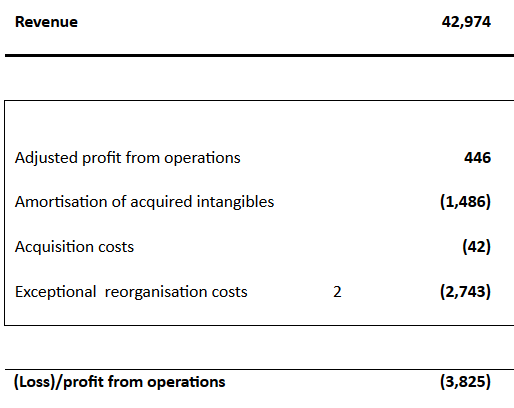
Revenues are up slightly to £43 million, but profitability takes a big hit due to "overhead investment" and the "sales slippage" in the key December period.
There is reference made "the pipeline of order prospects" which is standing at £82 million (compared to £56 million a year ago). I wonder how many of these sales are guaranteed, or are they prospective customers?
I've been taking a look at the KBT product set homepage. I consider myself reasonably up-to-date with technology, but have very little idea about what most of these descriptions mean!
So this stock will have
to go directly to my "too difficult" folder for now. Verticalising ERP solutions, providing out-of-the-box functionality, and unified omni-channel platforms - it all sounds great, but way above my pay grade.
Adjusted profits
For what it's worth, KBT claims to have earned an "adjusted profit from operations", prior to deducting the amortisation of acquired intangibles, and prior to exceptional reorganisation costs.
My opinion
Too difficult for me in terms of product at this stage and the numbers are tricky. Maybe someone smarter than me can figure out if there is an opportunity here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
RE: KBT
I would note that KBT talk about the possibility of changing their accounting period. This has become a bit of an obsession of mine (justifiably or not). They previously changed an accounting period some years ago, and in my view that allowed them to step over having to headline report a profit warning for the full year, by in effect extending the reporting period to 18 mths. That probably saved a few market linked options for the management (or is that too harsh?).
To change the accounting period again smacks of screwing up the comparatives, and puts quite a burden on the ordinary investor to read through it all. So for me this along with this sort of manoeuvre has a bad smell of engineering more feel good headlines. So a bargepole for me.
K3 Business Technology (LON:KBT) are a reseller for SYSPRO, Sage and Microsoft Dynamics. They add their own customizations and modules, which is normal for resellers of these products.
They've used a few buzz words in their descriptions, but the bottom line is that they have a solid business model here.
Hi Graham,
I was signed up for a while for YouGov's polls (but not any more) and I found the Brand Index questions the most banal of the lot, essentially asking whether I felt positively or negatively about a selection of brands and questions in a similar vein. I always opted out of these surveys and it makes me wonder whether they could really deliver a representative feedback on these brand surveys if people like me (whatever that looks like!) opted out of the surveys. For this reason, I struggle to hold this part of YouGov in any sort of esteem and cannot get excited about the company as a potential investment.
Re KBT Graham, when people want to pull the wool over your eyes, they write horoscope style like this. I worked in IT all my life and I have no idea what they are saying. Throw in buzzwords, a shiney smiley web site with pretty girls and hope that the hard of thinking will take a punt. I'm with safety margins these days, "invested" my punt money years ago and never saw it again.
Hi Graham
Thanks for covering ELCO, which I have a long position. I understand it may look "expensive" from a value perspective. However, in Mark Minervini's book he mentions that some of the best growth stocks have a P/E of between 30 to 40 which puts ELCO in that category.
Hi,
I also liked the results from Elecosoft (LON:ELCO) . It's vaguely been on my watch list for a couple of years, as I thought it looked potentially interesting. Today's results look really good - strong growth in profits, and the accounts look pretty clean, as Graham says.
I've picked up an opening long position in it today - am a bit late to the party, but if the profit growth can continue (and the outlook sounds positive), then I could see it growing nicely into the valuation.
I'm not too keen on its balance sheet though. It seems to be one of those software companies which finances the business from up-front payments from customers - see the large deferred income line. Still, I can live with that, since profits & cashflow are decent, and rising strongly.
It was rather too easy to pick up stock in it today, so looks like there is a seller in the market.
Regards, Paul.
Thanks for the reply Paul. I don't think you're late to the party, I hope it's just started! I noticed it was up ~9% on Friday so perhaps the results were priced in.
What attracted me was the good growth and technical breakout @ 37p. Thanks for the heads up on deferred income. From the preliminary results I read that deferred income relates to "annual maintenance contracts which are non-refundable" and "Historically, there is a low level of maintenance cancellations each year". That seems like low risk of the money not being collected or perhaps i'm being naive?
Thanks again
Ricky
I wholeheartedly agree with Samsgrandad re KBT. "Unified Omani-channel platforms" sounds like the gobbledegook spouted by Dilbert's pointy haired boss in Scott Adam's excellent daily cartoon. It could be that there is a scent product lurking buzz words but how would we know.
What I really like about Stockopedia and the SCVR is that between them they show up so many genuinely good companies. No need to take a punt on something like this.
Fair point ricky! I don't believe that all high-PE stocks should be avoided.