Small Cap Value Report (27 Oct 2016) - DEB, RIC, ALU

Good morning!
An earlier, and shorter report today, as I have to dash to an investor lunch.
Debenhams (LON:DEB)
Share price: 55.6p (up 3.5% today)
No. shares: 1,227.8m
Market cap: £682.7m
Full year results - for the 53 weeks to 3 Sep 2016 - note the extra week, which is necessary every few years to maintain a roughly similar year end date, for companies which use weekly, instead of monthly accounting.
In my experience, monthly accounting is better, as it evens out management accounts throughout the year, making monthly prior year comparisons more meaningful. However weekly accounting is easier to do, but results in horrible 4 & 5 week mismatches when you try to compare each month the prior year equivalent.
Overall today's figures from Debenhams look alright to me, given the strong headwinds which bricks & mortar retailers are experiencing - from online-only competition, rising costs (especially from Living Wage), other cost increases, and of course now all the problems coming through from weaker sterling.
Mind you, Debenhams should benefit from the recent demise of BHS, and I note that it is introducing lighting departments into 30 stores, to grab some of that business. It's a pity that BHS went bust, but it was a tired old format. Green managed to breath fresh life into it for a few years (boosting profits substantially in his first few years of ownership), but its demise was inevitable in my view - especially after the 2008 financial crisis, which resulted in its pension scheme liabilities soaring, due to interest rates being lowered so much.
It's bizarre the way the facts re BHS have been twisted by the media & politicians after the event, in order to create a pantomime villain in the shape of Philip Green. When actually if he hadn't been involved, BHS would have almost certainly gone bust years earlier.
The further I go on in life, the more I realise that human beings are predominantly emotional, and are not actually interested in the facts, in many areas of life. People really want simple stories, which reinforce their existing prejudices, not facts. You can see the same effect going on with shares all the time, on bulletin boards, etc - once someone owns a share, they block out and angrily shout down negative opinions or facts on it. This is very dangerous indeed, and is one of the key bad habits to unlearn as our investing experience builds.
People who can view shares they hold with a cold detachment, and will happily listen to & consider bearish views on their shares, make much better investors in my experience.
Anyway, back to Debenhams.
Bull points
- LFL sales up 0.6% - not bad for a conventional retailer.
- Gross margin also held up, only very slightly down, by 10bps
- Underlying profit before tax in line with expectations, and 0.5% up on last year, at £114.1m
- Underlying EPS very slightly down, at 7.5p - giving a PER of 7.4 - apparently good value.
- Online sales growing well, up 9.3%. Now 14.7% of total group sales.
- Dividend yield is good - 3.425p full year divis = yield of 6.2% - nice, but I'd rather see them paying down debt.
- Positive actions mentioned in the narrative - this is a business which is clearly doing lots of stuff to bolster & improve performance, ie it's not standing still.
- International performance is good, and on decent margins too - will help mitigate impact of weaker sterling too.
Bear points
- Net debt has come down usefully, but at £279m it's still nearly 41% of the market cap. Adjust to cash neutral, and the PER would rise to roughly 10 - not such a bargain after all?
- Pension deficit - it's an iceberg deficit. So only £4.1m deficit shown on the balance sheet, but the actuarial deficit is bigger, and requires £9.5m + RPI overpayments each year, plus admin costs. So a considerable drain on cashflow.
- Capex hungry - with lots of very large sites, heavy capex is an ongoing necessity to keep them looking modern & attractive to customers. So be careful with EBITDA - it's a bit meaningless for a business with constant, heavy capex requirement.
- No current trading statement, and no meaningful outlook comments - which can only be neutral to negative, in my view. If they were trading well currently, surely they would have said so?!
- Weak balance sheet, with NTAV negative at -£78m
- Note the huge £354.5m liability in long-term creditors for lease incentives. This is not a strict liability, but it is a measure of the up-front cashflow benefit which the company has received from reverse premiums & rent-free periods on leases. When I've got more time, I'll expand on this point. It's basically a drag on cashflow in the future - because credits will be put through the P&L from this item on the balance sheet, but will have no cashflow impact - i.e. profit will then run ahead of cashflow, which is clearly a negative thing.
Guidance for 2016/17 - Debenhams follows best practice, in guiding the market as to how it sees the new financial year working out. I wish all companies would do this, it's so helpful for investors, and of course these figures can be revised as the year progresses.
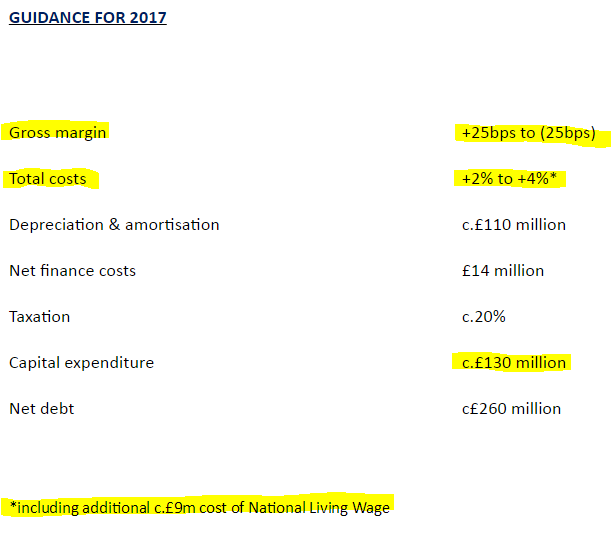
I've highlighted a couple of items above;
Gross margin - they're saying it's likely to be flat (between up or down 0.25%). I'm sceptical about this. Sterling weakness means prices will have to go up considerably. I think retailers will have to absorb some of that impact themselves. Hence in my view, we could see gross margins down something like 200bps at a guess. It depends on how far forward DEB has hedged, or contracted its input prices though.
Total costs - up between 2-4%, and see the footnote about Living Wage. This is the huge problem that UK retailers have at the moment - lots of their costs are rising, but most are struggling to get any top line growth. This is going to be potentially disastrous for profitability for retailers in 2017. Hence why I am so negative on the sector.
Remember that profit is already wafer thin for many retailers. So jack up their costs by 2-4%, with no top line growth, and gross margins under pressure, and you could see profits disappear altogether in some cases.
I fear that we're likely to see another wave of small to medium retailers going bust in 2017. That will free up more market share for the ones that survive of course.
My opinion - a fairly solid set of figures - Debenhams has fared reasonably OK in a tough market. However, the low PER & good dividend yield are not as solid as you might thing. There's a lot of debt, and a significant drain caused by the pension fund. Capex is large, and ongoing.
The outlook is grim, in my view, for almost all conventional UK retailers. They're facing big headwinds on costs in 2017, plus problems from sterling devaluation. I'd put money on Debenhams profit falling significantly in 2017. Hence why it's not an attractive share to buy right now, despite the apparently cheap value characteristics.
I don't think DEB is going bust, but I think there are probably better places to park our money in the next year anyway.
Richoux (LON:RIC) - (I hold a long position in this share) - shareholder circular published re the huge share options incentive package for new CEO, Jonathan Kaye. The Kaye family are of course very experienced restaurateurs, having been behind numerous successful chains.
More details are given on the trigger points for Mr Kaye's huge options package;
Under the terms of the share incentive being presented to Shareholders (the "Share Incentive") Jonathan Kaye may acquire up to 14,994,588 Ordinary Shares (14 per cent. of the then issued share capital of the Company) if the share price of the Company reaches 40p per Ordinary Share and a further 8,032,815 Ordinary Shares (bringing the total to 20 per cent. of the then issued share capital), if the share price of the Company reaches 55p per Ordinary Share. The Share Incentive will vest on the later of the second anniversary of the date of grant and the date(s) on which the performance targets are met.
My opinion - I've been saying for years that Richoux has great potential, and needed new management. At long last, the company has agreed, and done something about it.
The options package for J.Kaye looks insanely generous, but there again shareholders have to decide whether they would rather keep a larger slice of a small pie, that's going nowhere?
I jumped the gun a bit, and overpaid for my shares (I paid c.36p recently), so I'm not buying any more unless & until the price comes down a fair bit. It's so illiquid that it's very difficult to trade anyway. In my view it would be worth buying some more at around the 20p level.
Long term (say 5 years+) then I've little doubt the shares will be much higher. The Kayes have done loads of roll-outs, to a simple formula (pasta+pizza, very high margins, nice fit-outs).
Alumasc (LON:ALU) - a positive-sounding statement today, but the conclusion just confirms existing expectations for the year.
The valuation measures here look great. Be careful though, because it's cheap for a reason - due to a pension deficit. Deficits are becoming a bigger problem right now, due to bond yields being low, and inflation rising.
You can check if there's a pension deficit on Stockopedia now, just glance at this little box on the RHS of the StockReport;
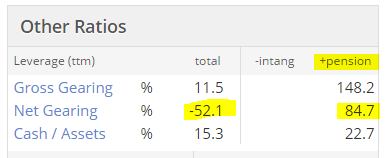
If the gearing figures in the "+ pension" column are larger than the gearing figures on the left, then it's flagging that you need to check out the pension scheme.
I have to dash now.
Also today, Bloomsbury Publishing (LON:BMY) reported, and there was a trading update from Caretech Holdings (LON:CTH) . I might possibly get a chance to update this report on those this evening, but we'll see how it goes.
Have a good day!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
The truth does matter, however inaccessible it is. The person with the best estimate/approximation has the opportunity to make the most money because they see the future more accurately.
Ray Dalio & Bertrand Russell would agree!
Truth—more precisely, an accurate understanding of reality— is the essential foundation for producing good outcomes. Ray Dalio
When you are studying any matter, or considering any philosophy, ask yourself only what are the facts and what is the truth that the facts bear out. Never let yourself be diverted either by what you wish to believe, or by what you think would have beneficent social effects if it were believed. But look only, and solely, at what are the facts. Bertrand Russell
A CND supporter suggesting you should not be 'diverted..by what you think would have beneficient social effects'? Wee bit of a hypocrite? (He made a big show of leaving the Labour Party because he believed Wilson would send troops to Vietnam, I think!)
Very much like the Dalio quote, but surely our ability to form an 'accurate understanding of reality' is dependent upon our ability and willingness to consider context and circumstance. Thus our personal truths are always based upon subjective considerations. (Probably not though!)
Is 'the best estimate/approximation' the truth? Seems more like a subjective estimation of events and factors to me (i.e. a belief system based on probability, not 'the truth').
You either believe in an objective reality or you don't.
If you do, then there is an objective 'truth'
If you know the truth, for today and the future, then you would be able to make a lot of money (eg gambling on results of events etc - you would already know the result)
If you know the truth for today, but not the future, you are still in a better position to model the likely future than someone who has a less accurate view of today (eg Man City more likely to win the PL than Sunderland).
Since we do not know the truth for either, we simply model on the basis of experience (and maybe theory). The more accurate the model, the better position you are in to make money. Most people limit themselves to a small portion of reality/truth because they know that maximises their accuracy.
Morning Paul,
The psychological term for the emotional reaction you are describing is called transference. It's an unconscious process whereby you link the other party to a character from your past. The character from your history can be positive or negative. You then react to the character in the present as if they were the character from the past. So if I was the victim of an exploitative headmaster or bully at school I am more likely to find bullies in my present life.
It cuts both ways though as one can also identify with the character in present given your history. So perhaps you have an unconscious identification with Philip Green and how you perceive he has been victimised. Perhaps there is something in your history as an FD whereby you felt you were unfairly criticised?
Just some ideas as to how we all become unconsciously emotionally involved in stories.
Best of luck
Phil
Regarding Debenhams. Reading through the extensive detail their statement, I can scope and put some numbers on 3 Headwinds that Debs face, in the context of a business that made £118m PBT last year.
1) Simplest one first, the 53rd week, which added £4m of PBT and obviously drops back out next year.
2) Minimum Wage: Increases by £9m in the new financial year. Despite talk of mitigating a lot of those through "further cost efficiencies", the two points I would make are "If the cost efficiencies can be easily found, why haven't you done them already?". Taking out costs isn't that easy, especially in a business like Debs which is well run and lean already. Also, the Minimum wage isn't just a one off increase next year...it keeps increasing year on year on year.
3) Less specific, but more frightening by far, is currency. They state that the year ahead is fully hedged at $1.50, and that 35% of their sales are sourced in dollar denominated. So 35% of £2.4bn sales is £850m. If one crudely assumes Gross Margin is 60%, then dollar denominated cost of goods sold is £335m. the difference between a current $1.22/£ and $1.50/£ is a c£80m increase in Cost of Goods. Their hedging may protect the year ahead...but if sterling stays at these levels, that's a huge potential problem for the year following. Can they pass any of it on through price rises? Who knows, and if market conditions remain like this, it may be tricky, and will obviously depend on the price elasticity of demand.
That's is 3 problems totalling over £90m pa for them to deal with, before whatever mitigating actions they can take, in a business which made £118m and has £279m of debt.
Was long, was having thought about these issues, I no longer am.
The bottom line is that he paid £200 million for it and sold it for a pound 15 years later. Other similar size clothing retailers in the UK have had their problems, but are still going strong (ish). I think it's pretty clear he wasn't fussed about the long term future of BHS.
" I realise that human beings are predominantly emotional, and are not actually interested in the facts, in many areas of life. People really want simple stories, which reinforce their existing prejudices, not facts"
So true!!! The facts have been twisted, in what is merely a political circus with no interest in the actual timeline and events surrounding the demise of BHS
Not specifically BHS/Green but we live in what I've seen coined as a "post-fact world", where the truth - or finding out the truth - is far too much hard work so there is an over reliance on other people doing the research (or not) and basing opinions on that. It's what costs businesses and society as a whole every single day
I am afraid the truth has never mattered, and never will. What we BELIEVE to be the truth is the foundation of our decision making. It does not matter if it is the witch crazes of the 17th century, the Wall Street crash, the outbreak of the Great War, or the invasion of Iraq, the truth has never been of much consequence in this world. (In picking stocks we tell ourselves we rely on facts and evidence, but largely we project the aspirations of ourselves and others onto our choices).
Hi Paul. Re BHS. If interest rates had not been cut in 2008 and the banks baled out and QE etc.,etc. then no-one would have had any money to spend in BHS, ...you can't have it both ways ! Also, do you really think that they would have gone bust earlier if £400m odd had not been not been taken out of the business ?- I find that hard to believe,even if Green is a wizard retailer.,though I also (vaguely)remember him from his WEW days,which did not end well either.
Whatever,he did or did not do,surely he can not be allowed to pass on his liabilities to the pensioners to a penniless buffoon ?!
So Green's facts have been twisted after the event have they?
And you ask that we open our eyes
Perhaps the public opprobrium is entirely justified and based on a solid understanding of the facts - and perhaps there's none so blind as those that cannot see
Hi Flackwell
I think you've demonstrated Paul's point admirably, you've just ignored the real timeline and judged BHS dividend policy on the basis of facts that didn't pertain at the time the dividends were declared.
Not in the slightest
and for the record I worked with the ex-knight of the realm and formed my opinion from those experiences
Indeed , from what I know he's not someone I'd want to have a pint with or indeed hold onto my wallet but that doesn't change the facts regarding the dividend timeline.
But its not just a timeline issue - look at how the dividend was funded and how the loans were structured
And we now know of the broken top up promises as well which reveal plenty about the real motivations at play
"loads of roll-outs, to a simple formula pasta+pizza very high margins, nice fit-outs"
im sure that the public are wise to being ripped off with 'Italian oriented' restaurants charging ridiculous amounts for a bit of spaghetti with some reheated sauce from the freezer, or pizzas with no real amount of protein on them by now. And still feeling hungry unless you have a full fat dessert for even more £££
Every mall has loads of these types of chains and they are all bland and overpriced. There are many more offerings appearing with just as nice fit outs, mostly independents.
No way is Jonathan Kaye going to get away with another boring food roll out. Hes going to have to work hard for his fat bonus and come up with something more original and satisfying.
Any views on the housebuilders,Paul,following the sizeable falls today led by BDEV going ex-div ?
I find it hard to get excited about Richoux (LON:RIC). I much prefer Fulham Shore (LON:FUL) which owns the Franco Manca pizza chain. I'm biased though as I love their sourdough pizzas.
Fulham Shore (LON:FUL) also has David Page as chairman (ex ceo of Pizza Express) so you can be pretty sure they know what they are doing regards building the brand and rolling out nationwide. Fulham seem to have stayed well and truly out of the spotlight so far with extremely low daily share turnover. Surprising, especially when you consider how popular the restaurants are (take a look at trip advisor or the queues outside).
I agree with the points made. David Page has a good track record @ Pizza Express.I'm also surprised at the low volume of the shares though I think it's a matter of time before more people become aware. The Franco Manca restaurants seem very popular - the central London branches nearly always have a queue outside the door when I walk passed. To my knowledge, they only have two Franco Manca restaurants outside of London (Guildford and Brighton) so there is lots of room for expansion.
Looking forward to your review of Caretech Holdings (LON:CTH) tomorrow. This really is an extremely well run company, operating in a difficult area of social provision and very lowly rated. We probably all want to forget about the field they operate in, but it is vital in the operation of a civilized society, and very few of us would be prepared to work for the minimum wage in a probably very stressful environment. I take my hat off to the management and all their employees. Good for the management to be far sighted enough to provide the training opportunities for their staff. I'm sure the company benefit from lower staff turnover; the clients benefit from better care; the staff benefit from an incentive to improve; win:win.
Caretech Holdings (LON:CTH) look very attractive, but their business makes me nervous because of the risk that vulnerable and difficult residents will be abused by stressed staff. Do you know whether CTH take special measures to assure themselves that they are not buying any risk of historic abuse claims when they acquire a new operation? How do they monitor the quality of care across their estate?
Thanks for that. I guess you have to trust in the quality of the management. They are long standing and very experienced in their fields. They expand slowly as you will have noticed; they upgrade their accommodation and services constantly. They made a shrewd move with the ground rents, and so dont make silly calls on the market for cash. They invest in training and staff in a way no other organisation of its kind does, as far as Im aware. I hope that all of this experience works through when they are assessing what they are acquiring. Seems to me they are much better than any others I have come across. They also seem to stay very close to the ones they are providing the service for - LAs etc. As a result they provide the best service and seem to be able to get cost increases through. Still lowly rated by the market, and unfairly so in my view but unlikely to change because I think it is unlikely there is an organisation out there who could better their performance by a takeover, and the management seem well positioned to stay. All IMHO, and always keen to have my assumptions and my research tested!
Hi Paul hope you are well - as you say that "It's bizarre the way the facts re BHS have been twisted by the media & politicians after the event, in order to create a pantomime villain in the shape of Philip Green."
If you have not seen it already on the BBC I-Player I think you will find this film "interesting" in that respect see - http://www.bbc.co.uk/iplayer/episode/p04b183c/adam...
Looking at the profile of Richoux (LON:RIC) they seem to be a chain with no clear idea of their product (French, Italian, American) or of their target market (Knighsbridge and Mayfair to Trowbridge and Andover) so there would seem to be opportunities to rationalise (and get benefits from combined purchasing and marketing).
But I'm never keen to invest where the management are this greedy, even if their reward package aligns their interests with shareholder interests to some degree. Im my experience, greed is never satisfied by the first or second mouthful.