Small Cap Value Report (29 Jun 2017) - UTW, HVN, PURP, ANP, WIN

Good morning!
There are lots of interesting things going on today, so I'll try to get through as many as possible.
I've been further pondering yesterday's thoughts on whether we've hit a market top. Obviously I don't know whether we have or not, I can only comment on things I observe. It seems to me that the momentum trade - of everything (growth stocks anyway) rising simultaneously, might have ended. Or at least is having a correction.
I think the danger is that we can all think we're ace stock pickers, but afterwards it becomes apparent that we just happened to buy a random growth stock, which went up along with all the others! Then when they fall, they all tend to fall together.
For me, the key thing is positive newsflow. To take growth stocks to new highs, it really does now require excellent newsflow. Not spurious contract wins (which often turn out to be immaterial), but beating expectations, and upgrading forecasts. That's what I particularly look for all the time, but especially now that valuations are very high, and the market feels more nervous. If a company is only meeting, not beating expectations, and the valuation is very high, then maybe it's time to bank some profits?
Purplebricks (LON:PURP)
(at the time of writing, I hold a long position in this share)
Talking of which, I'm very impressed with the announcement this morning from Purplebricks (LON:PURP) and have this morning bought them back for both BMUS and my real portfolio. Yes, the valuation of c.£1.1bn (at 414p per share) looks crazy. However, its results today show that the UK operation is operating at breakeven after spending £14.4m on marketing. It is now by far the market leader in online or hybrid agents in the UK, and is in a virtuous circle of success giving it more marketing firepower, driving further growth. Consider this;
UK marketing spend in the first half of this financial year is now anticipated to increase by some £3.5m year-on-year, with spend in the second half also likely to rise, should the expected returns come through. As a result UK revenue expectations for the current year are raised to some £80m; a near doubling from the £43m reported for FY17
Bear in mind that this is high margin business, where customers pay up-front, and this is developing into a very good business, just in the UK. The company looks on track to become the UK's largest estate agency, of any type. That alone could be worth the £1.1bn market cap.
Australian expansion is at an early stage, but seems to be going alright. Plus the big wild card is the imminent launch, on a small scale, in the US. If that works out well, in future years, the market cap now could look cheap. It may not work though - overseas markets can be very different.
I don't think there needs to be any network effect from overseas expansion. The point for me, is that PURP has cracked the UK market. So, whilst there will be differences in overseas markets, they should have a pretty good idea how to crack other markets too. So arguably it's a land-grab to become the dominant internet/hybrid estate agent in many countries. Then, once established, the cashflows should finance a marketing budget which can out-spend the competition.
So as a genuine internet disrupter, I think PURP looks potentially very exciting - despite appearing to be very expensive on conventional metrics at the moment. Yes, I know it's not small, nor value, so why am I writing about it here? Because it's interesting, and could be a good investment. This was a smashing trade for BMUS previously - in at 125p in Dec 16, and out at 407p in Jun 2017, once the valuation had become apparently too stretched. The newsflow today is sufficiently strong to make re-entry at 405p a good idea, in my view. We don't have to hold shares continuously. Personally I quite like to sometimes sit on the sidelines for a period, until the newsflow is strong enough to tempt me back in. Mind you, that was a disaster at BOO, when I missed another huge leg up. So whatever we do, sometimes it will be right, and sometimes wrong. There's no single rule that always works, whatever the people who like to throw wise quotes around after the event say!
The problem is that, due to internet disruption, value investing may not work as well in future. Low PER stocks in particular, could be value traps, suffering from internet disruption which may be killing off their business models. Not many traditional companies adapt well to radically different circumstances. Usually the high flyers in a new sector were start-ups a few years earlier - e.g. most of the dominant US tech giants now, are quite young companies. So I think great care is needed when looking at low PER stocks, and imagining that they might recover from earnings falls. Are those falling earnings cyclical, or structural? Many might actually be the latter.
We also saw yesterday how high dividends can also be value traps. With Fairpoint (LON:FRP) being the latest stock which attracted value investors (I fell for it, for a while) from a juicy dividend yield. Only for the company to basically go belly up, or be on the brink of it anyway. I think a generous dividend at companies which are dependent on bank facilities, should be disregarded - as chances are, it could well end up being cut at some point. I prefer divis from companies with net cash - as they have the capacity to continue paying divis, often even through periods of soft trading.
EDIT: Also see the section below on Utilitywise (LON:UTW) - which has also turned out to be a high yield value trap.
Harvey Nash (LON:HVN)
Share price: 81.5p (up 1.2% today)
No. shares: 73.5m
Market cap: £59.9m
(at the time of writing, I hold a long position in this share)
AGM Statement - this is a recruitment company, with a focus on "technology & digital talent".
The company has a 31 Jan 2018 year end.
Things seem to be going alright;
"The Group is performing in line with management expectations for the financial year so far, and ahead of the prior year, despite geo-political headwinds including the UK General Election.
"The immediate outlook is positive, with the key measure of contractor work in progress being comfortably ahead of last year.
Acquisitions - the company is also planning acquisition(s), and it sounds like they're being disciplined about the criteria & purchase price;
A number of acquisitions are being actively considered, each of which would be subject to stringent financial hurdles, and the Board is optimistic of being in a position to announce one or more transactions in the current financial year.
Cost-cutting - the new FD has come up with £1m in cost savings, which will incur £1.25m in exceptional costs. This should be beneficial for profitability.
Move to AIM - had previously been announced. This will be effective from 28 Jul 2017.
My opinion - I quite like companies moving to AIM, if they have honest management. Although regulation is lighter, it attracts investment from growing IHT portfolios. Although there can be a period of indigestion, where funds that are not mandated to hold AIM shares become forced sellers.
Valuation - this whole sector is cheap (the small caps are anyway). Although even allowing for that, the numbers look attractive for HVN (a sea of green below).
Note also the stand-out StockRank of 98 too, and is rated as a Super Stock, from this excerpt of the Stockopedia StockReport;
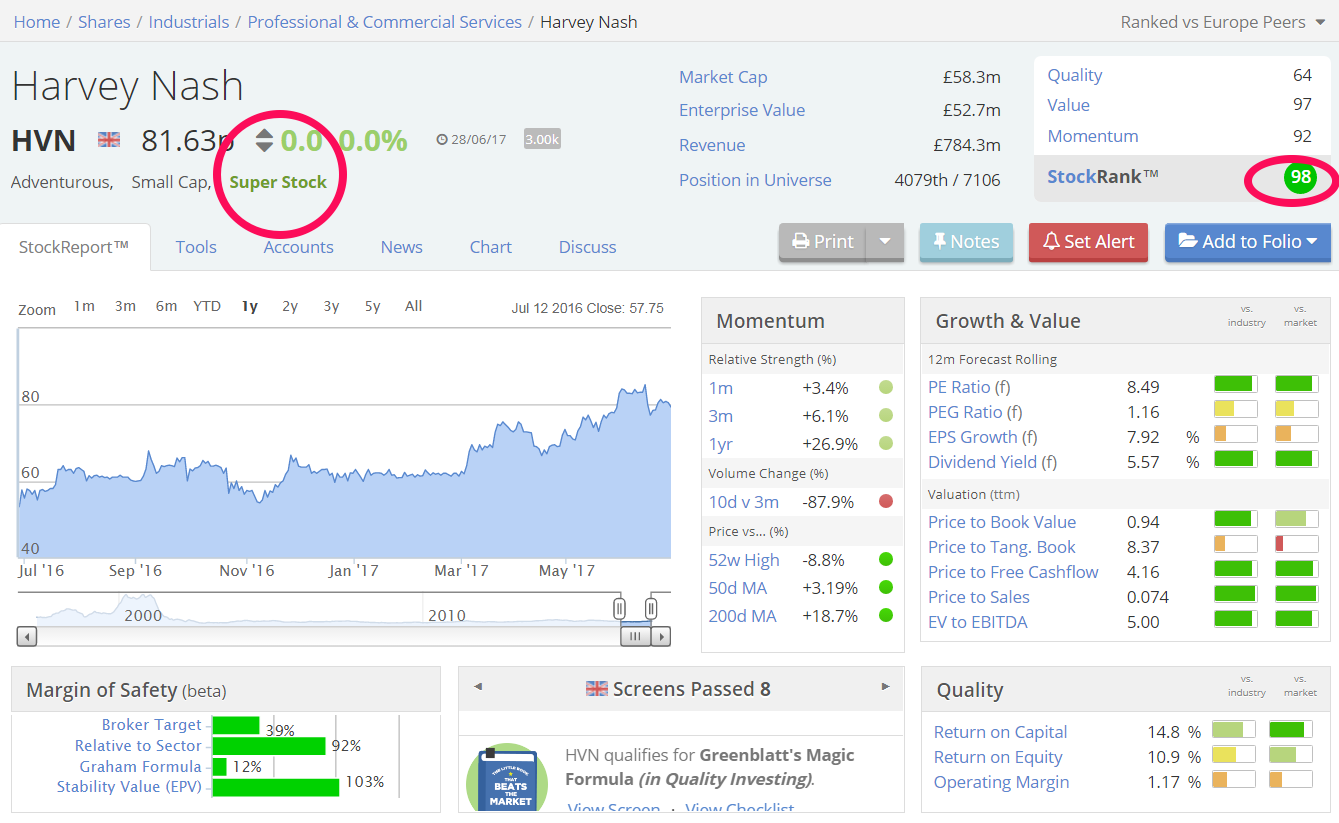
Just to reiterate, positive Stockopedia ranks don't guarantee success for individual shares, but are statistically proven to work, for a portfolio of stocks.
My opinion - I like it - HVN seems a decent company, and with bang up-to-date positive trading news today reducing risk, the valuation seems good value. It's a pity the bid:offer spread is so wide.
I might add to my existing long position on a down day.
Utilitywise (LON:UTW)
Share price: 73.5p (down 32.6% today)
No. shares: 78.5m
Market cap: £57.7m
Projected Under Consumption of Energy Contracts (profit warning) - well the accounting wheels have finally come off! I've been warning readers about this company's dodgy accounting for literally years, in these reports.
Utilitywise is a cost consultant for utilities - so it (supposedly) finds the best deals for businesses for their electricity, gas, etc supplies.
The main problem has always been that the company booked revenue & hence profit, a long way in advance of actually being paid their commissions by the energy companies - clearly an imprudent accounting treatment. This gave rise to huge debtors on the balance sheet. The debtors figure on the balance sheet is the total money which has not yet been paid by customers.
Excessive debtors is the single biggest red flag on any balance sheet, in my view. It very often hides all sorts of problems. Excessive debtors often means that the company has been too aggressive in revenue & profit recognition. That has turned out to be the case with Utilitywise. I think all investors should have a point on their checklist, to ensure that debtors are not more than c.60 days sales (inc. VAT). Also look for other, stray debtors, not just trade debtors. Both Globo & Quindell were obviously bad, because they had gigantic & unreasonable debtor balances on their balance sheet.
Today's announcement says that the company over-estimated consumption by some of its customers, and will now have to repay commissions of £7.6m to energy companies. Various excuses are made, and an additional £3.5m charge is also required. So a total hit of £11.2m to the next set of accounts, of which £7.7m is expected to be treated as exceptional.
The company says it can work around this, in terms of cashflow.
It also says this seems to be a one-off relating to one contract.
My opinion - there's a load more detail given in the RNS today, but I wouldn't bother reading it. The company now has zero credibility.
Myself and a few other commentators believed that the accounts were dodgy, and that has now been proven correct. Therefore I would treat this share as a bargepole job. If you can't rely on the accounts, then it's uninvestable.
Does it actually make any real profit at all? Given that so much profit booked in the past has now turned out to be bogus (i.e. based on incorrect assumptions), then I think this share is now impossible to value.
I wouldn't count on the high divis being maintained either - because the company has significant net debt. If you write off intangibles, and a chunk of the debtors, then the balance sheet doesn't look great.
Note also the sheer scale of massive Director sells in this stock in the past.
Anpario (LON:ANP)
Share price: 339.7p (up 3.7% today)
No. shares: 22.9m
Market cap: £77.8m
AGM Statement - this company sells natural animal feed additives. It's a stock that Lord Lee was very keen on, and I assume still is.
Today's update is short & sweet;
"The Company has achieved strong sales growth in the year to date directly attributable to strategic initiatives implemented in 2016 and providing confidence to accelerate the investment in recruitment of sales and technical personnel.
It then goes on to mention that Non-Exec Chairman, Richard Rose, is stepping down after 11 years in the role.
This update is not really satisfactory, as it fails to tell investors how the company is trading against market expectations - which should be mandatory for all updates, in my view.
Broker consensus seems to be for just under 10% sales growth this year. So the paragraph above sounds consistent with (or maybe even better than) that. Therefore, I think we can safely assume that the company is probably trading in line, or a bit above maybe?
Valuation - as you can see from the Stockopedia graphs below, Anpario has been awarded quite a high PER by the market. However, I question whether its growth in revenues and earnings has been sufficient to justify such a high PER?
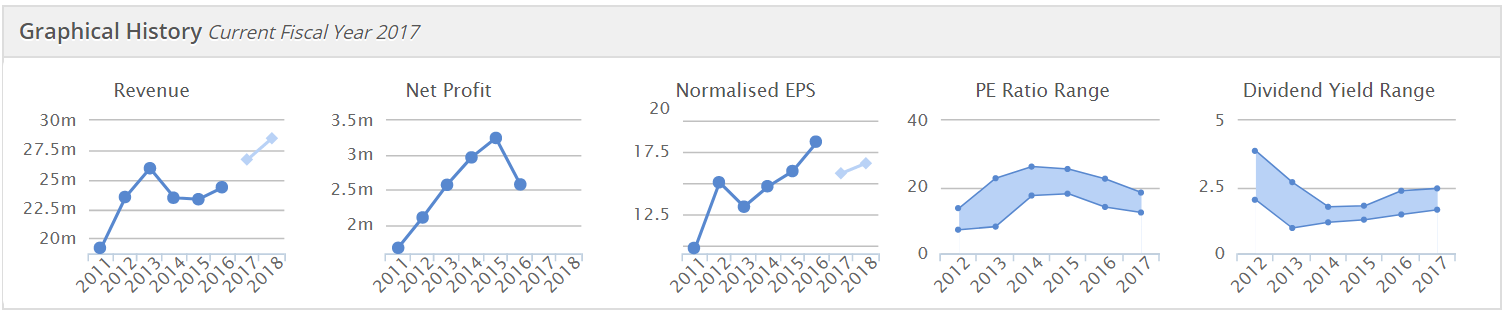
Normalised EPS hasn't really gone anywhere much in the last 6 years.
The forward PER of just over 20 seems high, for negligible earnings growth since 2012. Perhaps there are better things to come? There will need to be, to retain this level of valuation.
Dividends are nothing to write home about, with a yield of just under 2%.
Balance sheet - very strong, with plenty of cash.
My opinion - I don't know anything about its markets or products, so perhaps the share is more exciting than the figures to date suggest? It sounds as if some of the upside from increased sales is likely to be ploughed back into increasing overheads, in order to drive further sales.
I think for a PER of 20 or more, I'd want to home in on companies which are demonstrating more explosive growth potential.
A few quickies to finish off with.
Wincanton (LON:WIN)
A very mild profit warning today, which has knocked the share price by 7.7% to 270p, at the time of writing;
In the period since the year end, we have seen year over year growth in revenue primarily driven by organic growth in the Retail & Consumer sector.
The Group has experienced weaker than expected performance in some of its transport-related contracts and activities and these have created some trading profit headwinds in the first quarter. These are expected to be largely mitigated by continued operational efficiencies across the business during the remainder of the year.
Taking into account further reductions in the Group's net finance charges, the Board anticipates that profit before tax for the full year will be broadly in line with expectations.
Not a disaster by any means.
My opinion - this seems a good business, but not one I would buy, because the balance sheet fails my testing. Although the share price has shown that, when a business is performing well, then balance sheet concerns don't seem to bother the market.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
Hi Paul,
I am interested in your comment on Utilitywise: "I think all investors should have a point on their checklist, to ensure that debtors are not more than c.60 days sales (inc. VAT). Also look for other, stray debtors, not just trade debtors. Both Globo & Quindell were obviously bad..."
Can you please tell us how you calculate this metric?
Thanks.
Divide the debtors by 1.2 (to extract VAT) and then take the net amount, divide by annual turnover (which is always stated net of VAT) and multiply by 365. So £2.4m of debtors would equate to 61 days sales if annual turnover was £12m. (2.4/1.2/12*365 = 61).
Thanks
Does anyone know how the purplebricks LPE's are remunerated? I've been having a quick search but unable to get a clear picture of how this works. The reason I'm asking is because purplebricks' strategy is to eventually have 'ultra local property experts' controlling a smaller post code area and providing customers with a deeper understanding of their local maket. Obviously this is a plus for the customer but my concern is how would this affect the LPE's earning potential if they are in control of a smaller area? Are they going to be able to make a good living out of controlling a small postal code area of properties where they are presumably earning only a small commission of each instruction ? As I said, I'm not sure how the remuneration works but assume they take a small commission from instructions on top of a basic salary but would appreciate if anyone could clarify.
My understanding is that the Purplebricks (LON:PURP) local property experts are self employed and earn commissions per listing. It's more like a franchise model but the local experts don't have to pay to buy in to it.
They advertise potential earnings in the £45k+ region and I have seen claims some make up to £95k pa. Being self employed they will have to deal with their own admin etc. and won't get any holiday pay or other benefits.
I think they get around £330 to £500 per listing depending how many of the add on services they sell and whether it's in London or outside.
Useful to know thanks. I think any firm having a lot of self-employed workers needs to keep half an eye on the Taylor review on modern employment practices commissioned by the Government. It's due to report this month and could make recommendations which affect companies like Purplebricks (LON:PURP), Uber etc.
As I recall, Utilitywise (LON:UTW) is more than 29% held by Neil Woodford's various funds. In the past he has been pretty supportive of management despite the share price dropping from recent highs around the 200p level which up until today has served to underpin the price. I can't realistically see him wanting to take any more on (potentially triggering a mandatory bid) so he'll either need to stick with it or look to exit. If the latter, this will be at a fire sale price well below even today's heavily marked down level. Anyone tempted by this as a value opportunity might like to consider this before exposing their fingers to the falling knife.
Gus.
Utilitywise major share holders seller list below
http://investors.morningstar.com/ownership/shareholders-selling.html?t=UTW®ion=gbr&culture=en-US&ownerCountry=USA
Look like he(Woodford) is already selling out
Thanks dustyie.
My original figures came from the company website, which I see from the footnotes hasn't been updated since April 4th (prior to the sales reported on your Morningstar link from April 30th).
https://www.utilitywise.com/investor-relations/share-information/
Looks as though Hargreave Hale have been a seller as well at the end of 2016. After yesterday's profit warning not sure who the future buyers might be if they both look to sell down further. At least now that Woodford is down to 17% he has headroom to buy more if he decides at these lower levels it is a reasonable contrarian play. He's not averse to backing his own judgement against the market.
Gus.
The last Holdings RNS I can see for Utilitywise (LON:UTW) is:
http://www.stockopedia.com/share-prices/utilitywise-LON:UTW/news/reuters/reg-utilitywise-plc-holdings-in-company-urn:newsml:reuters.com:20161216:nRSP0681Sa/
or
http://www.investegate.co.uk/Index.aspx?searchtype=2&words=utilitywise
Which has Woodford at 29.01%.
The only updates since are Director Dealings and Total Voting Rights.
So unless the RNS is incomplete/missing then Morningstar is wrong and the company website correct
nice up tick in Purplebricks (LON:PURP) today , bit of a honey badger in today's market . Fist time since December 2016 that UKX, NMX, MCIX, SMX, AIM and TASX all closed below their 50 DMAs. Of the 37 NMX sectors only 4 are bullish. Might be time for the swoon ....
Paul, another company reported yesterday was CRPR, profit up almost 50%, their fibre business is a real moat.the mcap is about 160m, the chart is the most bullish one comes across.
I sold my house through Purple Bricks a couple of years ago. They charged £750 to sell my 4 bed detached house in the SE, we didn't have to pay up front as we agreed to use PBs own online conveyancing. I wouldn't use their conveyancing services again as our designated person was extremely difficult to get hold of.
The fee of £750 was about 17% of what I would have had to pay an estate agent. The PB agent was very competent, doing a couple of the viewings (it sold quickly) and always answering his phone using my first name so overall a good experience at a very cheap price.
I asked him how PB was able to do the service at such a low cost. He said that they had found a loop hole in the Rightmove charging structure, this was due to PB having just one office with all services carried out by agents, therefore PB was paying in effect for one estate agents office but covering the whole country. This in effect means that other estate agents were subsidising PBs Rightmove exposure. If this is still the case, and PB are taking an ever increasing share of the market, I can see more and more estate agents going to the wall. With Rightmoves dominant position in the online market, it wont be too long before they will change their terms and conditions to something like a per property charge. This would increase PBs overheads considerably.
I think the current market price of over £1bn is absolutely bonkers. Yes PB is changing the market for selling houses but to imagine that they have any kind of moat due to marketing spend or presence is illusionary.
First of all, I didn't give you that thumbs down, you make fair points. The 1.7% margin is what's tangible in the here and now, and it's based on this company having significant market share and being a market leader. If the company makes no money in this position, then I think it's a huge, huge stretch to expect them to do the sort of numbers your're talking about with a degree of confidence. I am not saying they can't, I think they possibly could, but even then this company is still only catching up to fair value.
I think Purplebricks is a very interesting company. I think it's going to have a potentially big effect on competition in estate agency and that effect will basically be to drive down fees. So that will be good for consumers, but overall bad for agents.
But I think there are also some clear limits to the scalability of Purplebricks' business. Clearly, their advertising spend has an element of scalability in it. But, they will need to continue to recruit agents (I am sceptical of the term "local property expert") as they grow. And, I think the current forecasts implicitly assume that there will be no response from traditional agents. I think that is really quite unlikely. I think traditional agents will (be forced to) cut their fees and this will curb Purplebricks' growth.
The estate agency industry is not obviously, to me, a winner take all market, unlike the portals such as Rightmost, or indeed other advertising or internet businesses, such as Auto Trader or Google. All of those businesses genuinely do have essentially zero cost growth, as well - so are clearly superior businesses to Purplebricks. In my view at least.
Also - I'm sceptical of the prominence they give to Trustpilot. For that kind of valuation I would like to see hard numbers (cash), not their internet review scores.
I would give this much more credence if it was a recognised measure like the net promoter score.
Having fairly recently been a buyer, what the high street agents say they do, isn't what they do in practice. the number of times we went to a viewing and the vendor was annoyed that the agent hadn't turned up. We even turned up to one viewing (with emails to confirm it had been arranged with the estate agent) and the vendor knew nothing about it! How many people go round looking in estate agents windows nowadays? The perception you get is that they add little value.
PURP
There was an article in The Guardian last week
'Sharp fall in home sales despite help to buy and record low interest rates'.
It's based on some research by Lloyds Bank comparing figures for 2015 / 2016.
https://www.pressreader.com/uk/the-guardian/20170621/282123521507579
I don't think it changes the' will they / won't they' become dominant arguements but they might be slower reaching profitability.
Housing transaction volumes are kept up to date by the government, you can get the statistics below. The numbers do show a fall in home sales, but I wouldn't refer to it as a "sharp fall" by any means.
https://www.gov.uk/government/uploads/system/uploads/attachment_data/file/619629/UK_Tables_Jun_2017__cir_.pdf
The Harvey Nash (LON:HVN) resolution to disapply pre-emption rights failed in the AGM today, with 40% against.
Fair point.
I'm sure they will react and already are with their own low-price options and investments in PURP online-only rivals. However, they are working to erode their own margins and undermine the earnings ability of their armies of estate agents. This creates profit and cultural issues that will be hard to overcome.
When disruption hits an industry it is seldom the established industry leaders that retain their position. Structurally their previous source of strength becomes their weakness. Look at Blockbusters vs Netflix, Bookshops vs Amazon, taxis vs Uber
you may be right, estate agents have certainly been slow to react so far, perhaps the booming market and relatively low market share loss has insulated them so far, the crunch will come when the market slows down significantly and more and more people realise that 90% of the work of selling a house is getting it on the main portals (ok maybe not 90% but a lot), and anyone can do that. At some point rightmove and zoopla might take private sales, they haven't so far, but until not that long ago they were blocking internet agents from advertising on their at all (until a legal challange)
Established industry leaders sometimes do win by adopting disrupters' tactics and obliterating them, e.g. ISPs vs. incumbent Telcos (remember Demon Internet?), most car challengers vs. blue-chip carmakers (remember Swatch's car?), etc.
Revealed: Shocking rise in violent and sex crimes in London’s bars and nightclubs.
From last week.
More and more security is the answer but it wont come cheap. Insurance costs are sharply rising too. Who wants to insure? Costs everywhere.
I remain short Revolution Bars from 125p with a 80p target.
barnetpeter,
Well it's a good thing that Revolution Bars (LON:RBG) has bars mainly outside of London then! ;-)
Paul.
Hi Paul,
Interested to hear why you sold Purplebricks (LON:PURP) immediately prior to the results based on its excessive valuation only to buy it back this morning at an even higher valuation? If you were confident in the business model and the prospective FY results would it have been better from a trading costs perspective to 'wait & see'?
On different subject any thoughts on Record (LON:REC) recently announced tender offer which combined with going ex-div today has taken share price down over 6%. Is that the sort of reaction you would expect?
Hi ACounsell,
Interested to hear why you sold Purplebricks (LON:PURP) immediately prior to the results based on its excessive valuation only to buy it back this morning at an even higher valuation? If you were confident in the business model and the prospective FY results would it have been better from a trading costs perspective to 'wait & see'?
I didn't sell PURP immediately before the results. I sold it (along with lots of other stuff) a few weeks ago, before the General Election, as I was worried about the political risk of a Corbyn Govt (only narrowly averted, thank goodness). So holding cash, as opposed to speculative stocks, was the most important thing to me at that specific point in time.
Today's results impressed me sufficiently to want to buy back in, armed with what I regard as impressive new information on growth, etc.
I bought back at roughly the same price that I sold at. So the re-purchase makes a lot of sense, as risk:reward is now a lot better than it was a few weeks ago.
Bear in mind that in my personal portfolio I use gearing. So risk management has to be very tight. BMUS reflects roughly what I do with my personal portfolio.
Regards, Paul.
Hi Paul,
Thanks for the explanation. I incorrectly assumed from one of your more recent reports that the Purplebricks (LON:PURP) sale was more recent. Unfortunately I sold my remaining holding (I took profits on the way up - don't trust myself/the market to run my winners!) at 364p when it fell back and hit my -20% from 52 week high stop loss. This stop-loss approach doesn't seem to work for me. If I stick to the rules - no emotion as Ed keeps telling us - the share promptly recovers all its loss and more. If I break the rules and don't sell it carries on down!!
Re the election I share your view on a Corbyn government and I fear we will get one within a year. However, I have given up trying to 2nd guess political risk after selling a portfolio of small companies pre- Brexit only to see the portfolio (if I still held it) up nearly 30% since May 2016!
Hi Paul,
Thanks for your reply. I just wondered if there had been something I had missed but nice to know there hasn't.
Cheers
James
Bear in mind that this is high margin business, where customers pay up-front, and this is developing into a very good business, just in the UK. The company looks on track to become the UK's largest estate agency, of any type. That alone could be worth the £1.1bn market cap.
What high margins? I see a 1.7% EBITDA margin for the UK business alone.
Like you said, Purplebricks in the UK is amongst the market leaders. In fact at this stage, I suspect it might even be the market leader. I calculate market share at being just over 6% on a most recent monthly basis (5.5k instructions received for April based on 89k total transactions for the period according to Gov.uk figures). If they're the number 1 player, or close to it, then where is the cash flow? I suspect your response will be that they can ratchet down the marketing spend in the future. But I would argue that this isn't possible. In a lifetime, the average person is only going to buy and sell a property a handful of times. Therefore, the marketing spend will need to be recurring in order to maintain the pipeline of instructions coming.
I think the valuation on this share is one of the craziest I have seen.
Surely it's the 56% gross margin and the operational gearing that are more relevant than last year's EBITDA margin?
Project forwards a few years and if they can get to a 10% market share of the 1.2m transactions a year in the UK, multiplied by £1,035 revenue per transaction and a 56% gross margin, that amounts to a gross profit of £70m in the UK. Knock off say £15m for overheads and £20m for marketing gives EBITDA of around £35m which is a 28% margin.
The point with the marketing spend is that even if it is recurring spend, it won't ratchet up at the same rate as revenue rises, so even if it's held at say £20m per year in the UK, that will represent a rapidly decreasing percentage of revenue over time. Also, it represents a moat of sorts as very few (if any) other competitors will be able to spend anything like as much on marketing.
Good point bestace,
PURP is only just swinging to EBITDA profit so the EBITDA margin will be tiny and not especially useful as a data point for forecasting.
It seems inevitable to me that PURP will continue eating into the mkt share of the bricks and mortar incumbents and will benefit from their operational leverage vs the structural high-cost base of those competitors.
My worry remains the US where I think the huge opportunity also brings risk. I'm still not sure why PURP isn't attacking that market with the same low-cost strategy vs competition. The value of the UK and Australian opportunities more than covers current market price in my view, but the shares could hit volatility if the US struggles and that froth starts to come out.
I topsliced a few weeks ago and am happy still being exposed to PURP albeit it with fewer chips on the table.
do you not think it's inevitable that the bricks and morters providers will start offering different levels of service ? we'll just put it on the internet for 500 quid, if it doesn't sell after 6 weeks, take our marketing solution, we'll offset the 500 quid against the 1% commision ?
it's going to be hard for purple bricks to compete with that,
surely it's inevitable though ?
K
They already are doing that but they are still saddled with their overheads, so even if they do sell it cheaper they are cutting their own profits. It's a lose lose situation for them.
Interesting to hear that the high street are offering an online-only service these days.
I agree that it doesn't seem like a good position to be in right now. Having said that it seems like the traditional players have a choice of:
a) offering a online service and accepting lower overall margins, or
b) being run out of business in the long term
Assuming they choose the former, and execute well, it could be a risk to the new players.
No position
Yes I came across this a few weeks ago when this was being discussed, here is one which is part of Countrywide (LON:CWD), http://www.bairstoweves.co.uk/?referrer=cat-google-ppc&mkwid=sd3jzHWc9_c|pcrid|188683864785|pkw|bairstow%20eves|pmt|e|&gclid=CjwKEAjwytLKBRCX547gve7EsE4SJAD3IZV6coxWl4NlSqikWGP5YU50V2jWccJO1VmwISuB7vWk0RoCpojw_wcB
This is essentially the brokers in-house forecast for 2019, so a very bullish case. Assuming everything was to work out by 2019, and we were to slap a Google type multiple on EBITDA of 20 on this business, that gives a market cap of £700m. Well short of today's market cap.
Also, your G&A portion of future revenues of 12.5% looks far too low. Other hot internet companies (Google, Facebook, etc.) are at 20%+.
I wasn't so much making a point about the valuation of the company, rather I was responding to your assertion that they are not a high margin business. If you're trying to come up with a valuation you would surely include something for Australia, and maybe something for the USA.
If you want to bump up overheads to 20% of revenue on my pro forma figures, you get to EBITDA of £25m which is still a reasonable margin of 20%. I don't hold a position in Purplebricks (LON:PURP), but I think you are missing the point by focusing on the 1.7% EBITDA margin achieved last year, and I think you're still ignoring the benefits of operational gearing when it comes to overheads.
Final point - is it "very bullish" to think they might reach £124m of UK revenue by FY19, which is the implied revenue based on my pro forma figures? They're guiding to £80m UK revenue in FY18 which is an increase of 85% compared to FY17. To get to £124m in FY19 would therefore require a growth rate of 55% in FY19, i.e. a considerable slowing down compared to FY18 and FY17. It doesn't seem implausible to me that they could comfortably exceed that growth rate if the chips fall their way.
With Utilitywise (LON:UTW), many have highlighted the aggressive revenue recognition, and I completely agree that caution should be taken whenever this occurs. However the contracts are with the big energy providers and so should be relatively solid, insofar that the end clients will be able to pay.
However this issue is to do with an over-estimation of the energy usage of new clients with a certain energy supplier - this will have been in the contract between the two counterparties. How they can get it so wrong is very worrying, and gives evidence of the severe incompetence at Utilitywise (LON:UTW).
Both issues are to do with short-termism from the company, and probably, often do go hand-in-hand.
Company's are far better being prudent, and under-promising and over-delivering - they will warrant a far better valuation in the medium to long term, when they consistently beat forecasts, rather than being a serial disappointment. As you rightly say, Utilitywise (LON:UTW) now has zero credibility.
Could it be 'in play' now?
Yes, I looked at Purplebricks (LON:PURP) 's results this morning and I too went back in with a long position.
The results are actually better than broker forecasts, especially an eps loss of -1p versus an expected broker forecast loss of -3p. Other positive signs are :
- operational gearing is kicking in. Revenues went up by 151%, against a cost base increase of only 41%. That's over a 3x gearing.
- my back of envelope calculation says that with foreward revenues of £80m for FY2018, they are likely to break even or even show a small profit.
UK market dominance is evident . The bet now is on the Bruce brothers to establish this model in the US without getting their fingers burnt or being crowded out by sharp American competitors.
I was also very impressed by PURP's results, especially dominance in online market (72%). My main concern about the company was its lack of economic moat, but growing market share suggests they are ahead of the rest by some way, and have the cash to support it.
I think it's premature to say they are going to be the biggest in the UK, at least in the near-mid term. Countrywide, LSL, and Connells are beasts, the former's revenue is around £700-750m/year, 16x PURPs, while the latter makes a hefty profit per year and owns a PURP competitor.
Nonetheless, long term (provided the upfront model continues to work) I think they will become the largest.
The point that many make about them becoming the largest very soon (probably this year) is based on number of customers rather than revenue.
Worth noting that DBAY Advisors have built a stake of around 26% of HVN.They call themselves value investors on their website. http://dbayadvisors.com/Strategy.html
Last year they were involved in the take out of Creston (CRE) at a premium after building a stake.
Hi shauney2,
Great spot re Harvey Nash (LON:HVN) - thanks for flagging up!
Regards, Paul.
just wanted to say another great constructed report. love the way you break things down and your views on the overall market conditions. really great read :)
Your comments on the nervous market that's ready to write down any suggestion of falling growth shows up well in Wincanton (WIN) today.
The company has done extremely well to build its business back up despite the legacy of a terrible balance sheet and an alarming pensions overhang. But today's even slightly hesitant forecast ("broadly in line with expectations" is nowadays a clear profit warning) has taken 9% off the market cap, and seems to draw a line under its fast growth phase.
Bit surprised you highlight HVN as a superstock yet fail to show similar metric for PURP.
Yes I know I'm going to get flamed by the usual bunch but I do like consistency!
Hi sminers,
Subscribers can look up details for themselves! Fairly obviously, an extremely highly valued, loss-making growth company like Purplebricks (LON:PURP) will always have a lousy StockRank & Style. So I didn't even look at them.
I'm only giving a flavour for things & a personal view. I'm certainly NOT going to work to some checklist to ensure consistency, as that would be too boring. I just write whatever pops into my head as I'm looking through the RNS statements.
Sorry about that.
DYOR!!
Regards, Paul.
"I just write whatever pops into my head as I'm looking through the RNS statements."
And you do it brilliantly. Ignore all suggestions of changing your approach, til the end of time!
Jon
Hi Paul,
Really enjoy the column, very interesting. Just wondered if you had any more thoughts on Revolution Bars as they were at one point down another 10% today although most of that has now gone. Is there a further potential profit warning coming? The drift from 120 to 108 seems to be a bit like the slow fall before the last.
I can't work out why as I certainly try and do my bit to boost their revenue.
James
Hi James (jsatchwill1)
There hasn't been any news from Revolution Bars (LON:RBG) - so there's nothing for me to comment on.
These reports are driven by newsflow, mainly trading updates & interim/full year accounts. Plus occasionally any significant deal announcements.
So when RBG announces something, then I'll do a section on it.
I don't want to start speculating on day-to-day share price movements, as that doesn't add any value.
Bulletin boards are full of people chatting about that sort of thing! (most of it being codswollop!)
Regards, Paul.