Small Cap Value Report (29 Mar 2017) - GMD, ABDP, APH

Hi everyone - I'm planning to look at Game Digital (LON:GMD), Ab Dynamics (LON:ABDP) and Alliance Pharma (LON:APH) today.
Regards
Graham
Game Digital (LON:GMD)
Share price: 42.5p (+7%)
No. shares: 170.9m
Market cap: £73m
I was tempted to buy some of these today, as net cash is now £69 million, very near to the market cap even after a 7% increase in the share price.
However, I resisted the temptation, and will stay on the sidelines for the moment.
It's definitely an unusual situation, though: a large retailer which is still profitable and priced only a little over its net cash balance! (Edit: it also pays a dividend!)
And I did not expect the share price to get so low, so quickly - it is barely 20% the level it was at in December 2015.
It previously traded under the "GAME" ticker, and left shareholders with nothing when it went into administration in 2012.
It IPO'd again two years later with half the number of UK stores it had previously, and with no international operations outside Spain.
But sentiment has soured once again as investors are concerned that games will in the future be downloaded and/or streamed, making physical distributors irrelevant.
I think that's a bit overblown, since there are console sales and gifts for children, etc. where physical stores serve a purpose.
But there is no denying that Game will continue to face changes beyond its control.
Results: A decent set of profit numbers, given the declining top line:
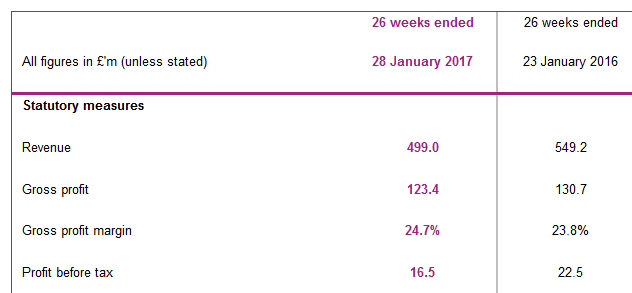
Note that Christmas sales are crucial and the spring/summer months then become very quiet. Last year, the PBT result for the full year was just £5 million.
Lease length: The average lease length of UK stores is 1.2 years, while the average lease length in Spain (where Game also has nearly 300 stores) is just 1 year.
That seems incredibly low, and perhaps means that the risk of investing here is not so great as it looks at first glance. If trading continued to deteriorate, perhaps the estate could be halved again, but without entering administration this time?
Outlook: A decent outlook statement. Management appear to be suggesting that the sales trend has turned the corner, at least in the short term:
The Group expects to deliver continued growth from digital and other new retail categories in the second half, as well as across Events, Esports and Digital, with these business areas delivering a growing contribution to Group gross profit. Furthermore, we currently anticipate an overall positive sales performance for the second half with the sales of Nintendo SwitchTM, together with our other sales initiatives to offset the declines expected in Xbox and PlayStation console markets.
My opinion: I'd like to continue researching this. Even if it's high-risk, maybe the potential upside is sufficiently large that it could be worth taking a small stake.
Ab Dynamics (LON:ABDP)
Share price: 612.5p (+2%)
No. shares: 19m
Market cap: £117m
Fairly simple update: revenue and adjusted operating profits for H1 are ahead of last year and in line with management expectations.
CEO comment:
"We have once again delivered excellent performance with a good pipeline of orders to take us into the next financial year. Our new HQ will enable us to reorganise our production and facilitate further growth."
This rapidly growing motor testing company had an oversubscribed placing and open offer in December, and raised £6.4 million.
It scores really well on quality and looks set to ramp up its activities with the opening of its new factory HQ this year, plus investment in its international centres using fundraising proceeds.
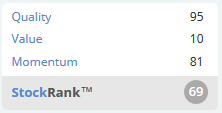
Considering the direction it's going in, I don't see why any long-term investors would want to sell out of it at this juncture! Opening a new position at this level is a bit harder to justify, since it's obviously quite highly-rated now. But true high-quality stocks are few and far between, so it might be worth a closer look.
Alliance Pharma (LON:APH)
Share price: 47.625p (-0.3%)
No. shares: 472.7m
Market cap: £225m
Pharmaceuticals aren't my specialism but this has a reasonable market cap for inclusion in this report, so I'm happy to cover it by request.
Revenues have now doubled at Alliance thanks to the December 2015 acquisition of products from Sinclair Pharma for £127.5 million.
EBITDA, PBT and free cash flow have all at least doubled, too (free cash flow up by 110%, to £13 million).
Alliance doesn't do its own R&D. Instead, it buys up rights from other companies, and then markets and distributes them.
The strategy appears to work well. Profitability has been sustained and on a broadly upward trajectory for approaching ten years, culminating in this transformational deal.
Diversification
The portfolio includes over 90 products, and only one of these is worth over £10 million in sales. So it looks very well diversified, and should not be too risky in the short-term. 70 of the products are said to deliver "stable and reliable sales without any significant promotional expenditure", mostly being prescription medicines which are "engrained into prescribing practice".
Gross margin is excellent at 56%, as you would hope for in this industry. 55-60% is the target range (59% was achieved last year).
Net debt finished the year at £76 million, and I do see a cause for potential concern here. The adjusted net debt/EBTIDA leverage ratio was 2.8x, which the company says is "comfortably below our banking covenant of 3.0 times".
93% utilisation of the banking covenant isn't normally comfortable to me! I guess Alliance must have a lot of confidence in the predictability of their revenue stream, which might well be justified:
We expect net debt and leverage to progressively reduce during 2017 driven by the Group's strong cash generation, including utilising our surplus US Dollar position, to service debt repayments.
In addition to this, £5 million will be paid from Sinclair to compensate Alliance for unexpectedly poor trading from one of the acquired products, and these payments have been earmarked for reduction in the bank loans.
So the debt is a bit too high for comfort right now, in my opinion, but will hopefully be back at a reasonable level soon.
My opinion
I don't usually have the confidence to invest in pharma, since the R&D and regulatory approval processes are too difficult for me to predict. But since Alliance don't do their own R&D, and are well-diversified, the risks could be manageable.
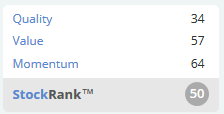
This is all I have time for today - thanks for reading!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
GAME got game? I ended up over on Roland Head's personal blog (https://www.rolandhead.com/ a great read, of course) and his comments on GAME Digital sparked my interest, especially their ongoing rollout of new Belong arenas. So i tried to find out a little more about how the kidz are responding to this, and came across a pretty positive thread on reddit, https://www.reddit.com/r/pcmas...
A small signal by itself and i need to look into it more, including all the comments here still, but it might just mean GAME (and Mike Ashley) is onto something with their instore gaming thing. It intuitively makes sense to me - high end kit it expensive, especially VR which is only at the very start, it's fun to (physically) hang out with your buddies which you can't do at home coz you only have one computer, eSports is booming, they're setting up across-store tournaments, they cater for teenager birthday parties and so on. The other thing is, my kids who are still under 10 are growing up with games and tablets just like all the other kids, in a way they're all gamers now, it's just normal and they'd love this stuff when they're a bit older (which they can pay for out of their own pocket money, just saying). I think there's a market for this. If they can get the branding right there might even be some parallels with Games Workshop here?
Anyway, i think it's interesting, definitely a company I'm going to start keeping an eye on.
Looks like CloudTag Inc (LON:CTAG) has gone, this was covered by Paul last December.
Thanks,Graham, Good point.Graham.
ABH, rightly or wrongly, forms part of my Inheritance Tax-free portfolio. The acquisition of Sinclairs portfolio has provided marketing access to may more countries and the benefits have yet to be fully realised. Thus, although debt is certainly a concern in the short term, its near 3% yield and international earnings seem attractive at the current sp.
Hello Crusty
Just seen your reference to your IHT AIM portfolio.
I am just starting one and have only just recently accessed this website.
Any advice on building this portfolio would be appreciated.
Mrken.
Graham, hope you don't mind me posting here.
We've just released a video with Gervais Williams talking about the future investing landscape. There's a quick 3.5 mins overview, followed by another, with a fuller 30 mins presentation.
Thought it might be of interest to all here.
http://www.piworld.co.uk/videos/2017/3/28/gervais-williams-at-redleaf-breaking-the-mould-capital-markets-day
Tamzin
Thanks Tamzin, I'm sure nobody minds. Looks interesting!
Graham
Thanks for the alert Tamzin. Gervais Williams is always worth listening to.
Just thought I would comment on Flybe (LON:FLYB) update today since it has a history of comment from Paul.
I have held a negative view regarding Flybe for a couple of years now and today they issued another dire statement - profit warning
Net debt continuing to climb partly as a result of having to take on more ex-Republic Q400 aircraft. Those aircraft are probably only worth about 70% of what they actually paid for them. Ideally they should have done a sale and lease-back but their failure to do that should be a red flag. However this will not be an issue until some years hence.
Load factor continuing to decline (generally speaking anything below 65% herald's 'lights-out').
Capacity increasing
A new CEO that is 'excitable' but has not stamped her authority on the business; so I have little faith she will do anything substantive over her predecessor.
The start of what maybe two or three years of write-downs and ever increasing 'exceptionals'
Load factors are in fact only against scheduled flights; does anyone know the proportion of charter flights to schedule? Load factors are not such an issue on charter flights because (in theory) even if the aircraft is empty the airline gets paid albeit without seeing possible additional passenger ancillary income.
Anyway, I see little evidence of a real turnaround here; a view I have held for two years.
Today Ryanair hit the panic button: http://www.investegate.co.uk/ryanair-holdings-plc-... which will not help European airlines. Personally I think it's BS and just Ryanair grabbing headlines again to further bolster revenue. Now there's a CEO worth having....
Carcosa
Hi Graham,many thanks for your report. GMD does look very interesting,though I notice they have cut their dividend from 1.67p to 1p, do you think they are being super conservative ,? It does seem a strange move bearing in mind their EPS and cash balance.
Cheers,Graham.
Hi Graham,
Well, rather than paying a super-high yield, it would make more sense to me to start buying back their shares at this level (presuming they don't think they are going into administration). That would potentially add a lot more shareholder value in my view.
But cash is likely to drain over the summer, and investors are clearly very worried about the future, so an element of conservatism makes sense to me, especially when it comes to the dividend.
Graham
ABDP statement says: "Revenues and operating profits (adjusted to add back share option charges) for the six months to 28 February 2017 are expected to be ahead of the same period last year and in line with management expectations." Since share option charges are (probably, depending on the scheme) a cost why add them back? And can we assume that if they were not added back profits would be below same period last year and below management expectations? Otherwise why put the qualification in?
Not necessarily. From last year's finals (my bold):
A cynic may claim the main reason for adding back the share based payments is to cast the results in a better light, but it is also possible that the aim is to to provide a better sense of the underlying performance of the business.
Holy cow, Graham has lost the plot. Game? Didn't they crash and burn before, and the market for physical games has only got tougher. These are almost guaranteed to shrink further...
Relax, he hasn't actually bought any... yet... game has transformed to become more of a social / plastic gift space. They just need to add a few arcade machines and a coffee shop I reckon to occupy the dads...
Hi Graham,
I was wondering if you or any readers have any thoughts on this morning’s final results from Centaur Media (LON:CAU):
http://www.investegate.co.uk/centaur-media-plc--ca...
At first glance I didn’t thing they were too bad but the market clearly wasn’t impressed as the share price went down about 24%, although it has now recovered a bit and is down about 13%.
Perhaps this spooked the market:
At least the generous dividend hasn’t been cut (yet).
A potential disposal of part of the business has also been announced:
http://www.investegate.co.uk/centaur-media-plc--cau-/rns/potential-disposal-of-home-interest/201703290705028165A/
Gostevie
Disclosure: I hold shares in this company