Small Cap Value Report (29 Nov 2016) - CRAW, IGR, MYSL, CAKE

Good morning!
Here is yesterday's report, which I wrote overnight, so most people won't have seen it yet. I recapped on the interesting takeover battle for Lavendon (LON:LVD) , plus tried to understand the situation at Trakm8 Holdings (LON:TRAK) after poor interim results. Also a quick look at Stride Gaming (LON:STR) .
On to today.
Crawshaw (LON:CRAW)
Share price: 24.1p (up 7.2% today)
No. shares: 79.2m
Market cap: £19.1m
(At the time of writing, I hold a long position in this share)
Trading update - my heart sank when I saw this, as I assumed it would be another profit warning - given how the share price has been almost in freefall of late.
Overall though, it's actually not that bad, when you consider that the share price has now dropped by 74% in the last year. This spectacular fall from grace is because perception changed from it being a sexy retail roll-out, to being a small chain of barely-profitable butchers.
The first paragraph of today's update reassures;
Crawshaw Group plc ("Crawshaw" or the "Group") (AIM: CRAW), the fresh meat and food-to-go retailer, notes the recent movement in its share price and confirm the Group continues to trade in line with management expectation.
Sales trend - this has improved, as you can see below, but is still negative;
Previously reported on 29 Sept 2016, LFL sales;
Q1 (Feb, Mar, Apr): down 0.8%
Q2 (May, June, July): down 7.8%
Q3 (Aug, Sept, Oct) - first 7 weeks only: down 15.8%
Reported today (29 Nov 2016), LFL sales;
4 weeks ended 27 Nov 2016: down 8.1%.
Clearly, a decline of 8.1% in LFL sales for the most recent 4 weeks is still a poor performance. However, the trend is improving from the disastrous performance earlier in Q3.
The company's self-help measures appear to be slowing down the decline in sales. It emphasises today that full year results still rely on the key festive season;
The Board are confident in the actions taken so far and are encouraged by the early improvements in sales, but note the importance of this progress being maintained through the key winter and festive period to deliver full year profit expectations.
Forecasts - I've not seen any updated broker figures yet this morning. So based on the existing numbers, it's expected to produce a small loss of £0.1m this year. It sounds like there might be a little downside risk on that, if Xmas isn't as good as CRAW hope.
My opinion - it's obviously going to take time to restore market confidence here, if it can be restored. The original roll-out plan seems to be highly questionable now. The issues seem to be;
- Supermarkets fighting back with better value offers on meat
- CRAW self-inflicted damage - they tried to get too clever on margins, and the customers walked away. So it's having to go back to the basics, of being a discounter.
- New High Street stores not producing enough profit. However, out of town sites doing well, e.g. West Bromwich
- Giving branch managers more input into choosing products & price points that their customers want - this suggests to me that Head Office doesn't have a decent merchandising department - it's their job to spot what sells in which locations, and adapt products/pricing accordingly. There could also be an issue with inadequate EPoS-derived information?
My opinion - it seems to me that CRAW management tried to run before they could walk. So they embarked on a rapid expansion of stores, without first getting the business model robust enough.
Maybe they just hit a temporary sweet spot, catching the supermarkets napping, that has since disappeared? I think the jury is out on this company at the moment, and the share price crash has reflected that.
The share price is all over the place this morning. There still seems to be an aggressive seller in the market. So I've got no idea what the share price will do in the short term.
Longer term, I think at £19m (24p per share), the market cap is now factoring in very little progress from here. The balance sheet is OK for now, and with a significant depreciation charge, the company should generate cash even at breakeven on the P&L.
I think there's a chance that things could improve, once the disappointed sellers in the market have been flushed out. It's anybody's guess how long that will take - it can take a very long time with small caps, due to the illiquidity.
The price isn't yet cheap enough for me to want to back up the truck, but it's not far off. So personally I intend holding for now, and seeing how things develop. If the price continues falling, then sub-20p would start to look interesting as time to top-up. 15p or below would, for me, be time to fill my boots.
Management are very ambitious, but they're really messed things up this year. So it could take time for them to repair the damage, and regain credibility.
IG Design (LON:IGR)
Share price: 288p (up 4.2% today)
No. shares: 62.6m
Market cap: £180.3m
Interim results, 6 months to 30 Sep 2016 - these figures look excellent! Also, I must say top marks to the company & its advisers for being completely transparent in how they're presenting the highlights. Each item is broken down into how much growth is organic, and how much has come from the acquisition of Lang, and the gains from forex.
Note how forex has had a massive impact on these numbers, in a favourable way. This got me thinking that there could be upside on other shares I own, with US dollar earnings. Maybe we've been under-estimating potential favourable forex gains? Or the opposite too - maybe we're under-estimating the damage at companies which sell in the UK, but buy in dollars? All food for thought anyway.
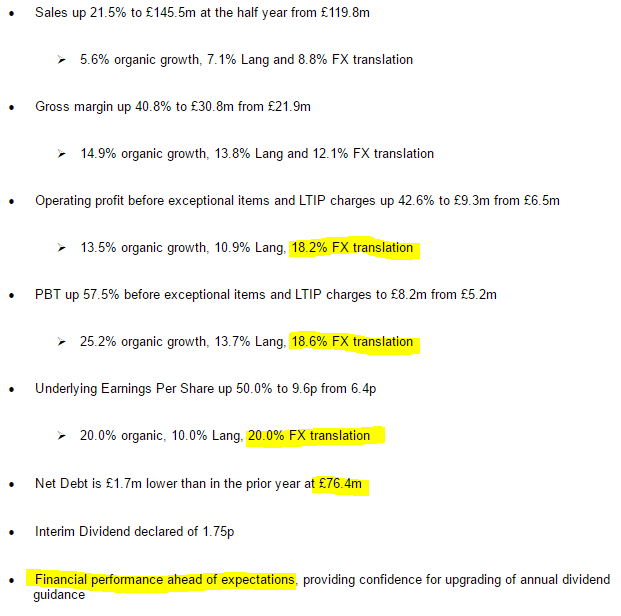
Net debt tends to be high at the interim stage, because of seasonal working capital requirements - so debtors are inventories are very high at the half year, but reduce back down again by the year end on 31 March.
Outlook comments look excellent;
With a strong order book in place for the balance of FY 2016/17 we are on course to deliver financial results materially ahead of market expectations for the full year.
Current momentum in sales and gross margin is expected to be maintained into the second half of the year.
While the timing of overheads and the acquisition of the Lang Group of Companies part way through the year (therefore excluding early periods which are seasonally loss making) has slightly flattered the first half year's results at the levels of operating profit and below, profits and our key metric of earnings per share are also expected to be stronger.
That sounds really good. I'll wait to see what the revised broker forecasts look like, but the company certainly seems to be on a roll.
My opinion - when last reporting on this company, I was concerned that the share price looked to have run away with things. However, we now find out that the company is trading materially ahead of expectations. So maybe insiders were filling their boots, knowing that things were going well?
It's so difficult when you see a share price move above a sensible valuation. What are we meant to do? Sell because it's got too expensive? Or hold on, hoping that the buying is being driven by people who know that the company is performing ahead of expectation? It's very difficult, and there's no simple answer.
Good companies do tend to grow into their valuation though. Also the market is very excitable about growth companies right now.
Everyone I know who has met management here, has said how good they are.
I have to stop here for now, as have a meeting in the City.
I'm partially nocturnal at the moment, so wouldn't rule out the possibility of a further update this evening, as there are loads of updates for me to look at today.
Evening update - several readers have asked me to look at Patisserie Holdings (LON:CAKE) and £D4T4 so I'll get cracking with that now.
Patisserie Holdings (LON:CAKE)
Share price: 270p (up 4.7% today)
No. shares: 100.0m
Market cap: £270.0m
Results, year ended 30 Sep 2016 - I read these results earlier today, on my iPad whilst having a soak in the bath. I couldn't see anything wrong with the figures. On the contrary, this stock ticks nearly all of the boxes that I like;
- Self-funding roll-out of new stores, going well - about 20 new stores each year
- Excellent profit margins
- No issues from Living Wage, or currency - all seems to have been dealt with smoothly
- Bulletproof balance sheet, including £13.3m net cash
- Quality management, including the Luke Johnson halo effect - he's Executive Chairman - like most investors I'm sure, I have tremendous respect for him
- Outlook comments sound good - "encouraging" performance in first 8 weeks of new financial year
- Average store payback period of 23 months - this is highly impressive
What's not to like?
Dividends - unnecessarily stingy in my view. The yield is only about 1.2%. To my mind, looking at the balance sheet & cashflow statement, I think the business already has scope to pay much more generous divis. Still, at least that's something to look forward to in future years.
My opinion - my only reservation with this share in the past, has been that its rating got rather racy. Paying a PER of 25-30 really was getting too much.
Since then though the rating seems to have moderated somewhat. Right now I would say the price looks about right. It's just announced diluted EPS of 13.6p, so at 270p the PER is 19.9 - that's not traditionally what we would think of as cheap, but for a self-funding retail roll-out, with high margins & a lovely balance sheet, it's not unreasonable in my view.
EPS rose by 20%, so a PER of 20 looks about right - that's a PEG of 1.0.
The market tends to look ahead at the current year earnings, and it looks as if CAKE should do about 16.0p this year, so the PER drops to 16.9, which looks about right to me.
The chart seems to be showing a gradual loss of interest in this share, it's been drifting down, which is quite surprising for a high quality business like this. Maybe some investors are chasing faster growth at online companies? The problem with a physical stores roll-out like CAKE, is that the growth can only go so fast. That limits the PER to around 20, in my view.
Overall, I think this is a fantastic business, and I'm starting to get tempted to buy some - the valuation is now coming into range for me. I'll ponder it for a little longer, but don't be surprised if I add this to my portfolio in the coming weeks/months, if the valuation drops further.
It's very surprising that the StockRank is only 32 at the moment. CAKE has a very high quality ranking on Stockopedia (93), but is let down by very low value & momentum scores.
Maybe the market is worried that with consumer spending likely to tighten in 2017, perhaps CAKE might experience a slowdown in its customer spending? Personally I doubt it. I agree with the company's view that it is seen as an affordable treat in more difficult economic times. Also £2.95 for a slice of cake is hardly extortionate is it?!
MySale (LON:MYSL)
Share price: 96.5p (up 3.2% today)
No. shares: 151.3m
Market cap: £146.0m
(at the time of writing, I hold a long position in this company)
Trading update (AGM statement) - it sounds as if things are going quite well at this online "flash sales" clearance group;
"The current financial year has started well with revenue growth rates similar to the second half of last year and with substantially enhanced gross profits.
''We have continued to direct more of our marketing spend in the core ANZ market towards re-engagement with lapsed or inactive customers and this has been successful in reducing Cost Per Activation (CPA). We will continue to invest in our data and analytics capability over the remainder of the financial year and so would expect to drive further improvements in marketing efficiency.
''With reference to market forecasts, at this relatively early stage we would anticipate a full-year out turn slightly above the top end of the current range of analysts' projections of $8.2 million to $8.5 million underlying EBITDA.
Top marks to the company & its advisers for giving some figures in the announcement, for market expectations. I'm sure if we keep nagging for long enough, then this will gradually become the norm.
I especially like the "substantially enhanced gross profits" comment. The opportunity for investors at MYSL is that its original business model had very low gross margins - it was just clearing consignment stock, on behalf of brand owners. The model has since been greatly improved, to include bought-in stock on much higher margins. This is why profits are now considerably improved.
I saw a very bullish broker note recently, which pointed out that MYSL has already built an international business, and the opportunity now is for it to ram through higher volumes, at higher margins.
Broker upgrades - I see one broker has today increased its EPS forecast for this year (ending 30 Jun 2017) by quite a considerable amount in percentage terms - up 15.8% to 0.8c. Mind you, the PER looks completely nuts on this year's forecasts - the Aussie$ 0.8c EPS forecast translates into 0.48p, which gives a current year PER of 201 times! LOL.
Still, this makes a bit more sense when you consider that the broker reckons earnings will almost quadruple in the next 2 years, and also points out that with the company now beating forecasts, there's likely to be more upside on those forecasts.
My opinion - I think this is a case of a company which is starting to grow into its valuation, and where in a couple of years' time we might realise that the valuation wasn't actually as crazy as it looked back then. That's the reason I'm holding this share anyway.
Companies that are successfully cracking the online fashion market, internationally, like Asos, BooHoo, and MySale, are exciting investors in a way that traditional businesses just aren't. That may not last forever, but for now, online fashion is a very exciting space for investors. If the game is profitable, then personally I'm happy to continue playing, but keeping an eye on the exit too.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Paul, any views on Digital Barriers (DGB) ? I know you had a holding some time ago.
They announced interims yesterday. Business seems to be booming but they are still have some issues about when the revenue can be booked. Would have thought they would be a huge beneficiary of sterling drop & the 'Trump' efffect but the market didn't seem impressed judging by sp slide.
Regards
Dennis.
DGB looks a total crock to me!!
Paul, I don't know if you noticed but a couple of newspapers ran pieces about MySale (LON:MYSL) in the last 24 hours. They are planning on launching an own-label womenswear brand called London Chic. That's encouraging. Plus I am pleased that they are finally focusing on higher end fashion labels which I think has a much better potential for them (assuming margins are still good). Some of the brands they listed before I'd never heard of! https://www.drapersonline.com/news/mysale-ups-full-year-expectations/7016351.article
Thanks bestace, I did not see that! I've purchased a few today, after some top slicing elsewhere.
"Topsliced" to buy cake! Very good!
I bought some cake this morning as well, prices have been up and down, opened up about 10p, not sure if that was due to Paul or not but soon fell back below 270p but now back up again to around 278p. Not worried about the dividend, have concerns about the outlook once Brexit starts.
I don't think £2.95 for a small slice of cake is that cheap, last time I went in M&S it was about £2.40.
Re. "I don't think £2.95 for a small slice of cake is that cheap, last time I went in M&S it was about £2.40" isn't it all a question of relative quality? You can probably get a piece of cake in a Sainsbury's cafe for less than £2... but it's unlikely to be half as nice an an M&S piece of cake... and I'd suggest that IMHO the quality of a Patisserie Valerie piece of cake relative to an M&S piece of cake justifies the price. It's just a different market... isn't it?
I don't totally understand why you actually bought shares if you have outlook concerns and also are skeptical of the price of the value of their product...
You have got me there I have never been in a Patisserie Valerie shop, there are none in my area.
I must confess I was in two minds about buying, I think the outlook problem maybe some time off, so I have time to see how it goes, after Brexit people have many concerns but the market has taken off, a dummy NAPS of 20 shares I did after Brexit is up nearly 24%, which I don't really understand, the market does not always go the way you expect.
You never have concerns about shares you buy?
Re Patisserie Holdings (LON:CAKE)
My first dumb question of the day... why does the balance sheet show trade and other receivables of £11,004,000? I could not see an explanation in the narrative or notes. It seems a lot for a business selling only products usually purchased with cash, or do they sell cakes on easy terms; pay nothing now and pay the balance over six easy to afford monthly instalments? I'm sure I'm missing something, please help!
Thanks
Looking at the 2015 accounts (note 14), the vast bulk of those receivables will be prepayments for rent and rates. Trading debts amounted to just 9% of the overall receivables figure last year.
I think one of their brands caters to businesses, which I would imagine is done on credit terms.
Its been said before but I suspect Crawshaw's (LON:CRAW) initial success was more to do with the Horse meat scandal rather than any business model. Now that that has started to fade in customers memories they will drift back to the supermarkets. It’s not as if independent butchers are a new idea. They’ve already left our high streets 25years ago and I can’t see any fundamental change in shopping habits now to allow them back.
See a director at Getech has just bought 300,000 shares on Monday-since the FIRST profit warning couple of years back (I have been a shareholder since well before this having got in on the way up from initial buy at 22p
Hi Paul
Re CRAW, do you have any concerns that they have provided no information in relation to margins over the last 4 weeks. In LFL sales terms, they have clearly started to move the situation in the right direction but has this been at the cost of a further reduction in gross margin?
Obviously impossible to tell currently which makes their RNS far less helpful; indeed the RNS might be giving a totally false picture that some measure of progress is being made.
Perhaps there is a broker update which says more.
All IMHO.
Regards, Martin
Re IG Design (LON:IGR), I was at their Richmond ShareSoc presentation in October and I'm sure I heard the FD say that they had run the numbers and found their business was neutral with regard to exchange rate movements. Seems not.
Paul
I see 3 major negatives with Crawshaw (LON:CRAW)
1. "in line with management expectations" as opposed to "with market expectations" - in the comments from CRAW - are a red flag for me. In this case as with Lakehouse (LON:LAKE) it seems to invariably mean a loss (I'd welcome any examples to the contrary).
2. Whereas I freely accept your greater knowledge, Paul, when it comes to retail I am reminded here of something Hugh Hendry said. To paraphrase 'retail is easy, the stock goes up with the store roll out then down as the positive impact of increased distribution fades'. This rings true to me after a decade of selling consumer goods to supermarkets - Tesco being a case in point. CRAW seem to not even be able to achieve that and this fact presents another red flag.
3. I think you said previously that these guys don't seem to know what their business model is anymore. I agree completely.
Given the above 3 points, why are you still prepared to 'back up the truck' with this stock? Even at 15p. It seems to me that the investment thesis is gone. One to move on from?
I'm happy to be wrong on this one but I just can't see it.
Re Crawshaws-Good points doesn't look good to me but value there to an accountant at lower enough price
I also would be interested in Paul's views on Patisserie Holdings (LON:CAKE), his last review seem very positive apart from the valuation.
Any chance of a comment on Eckoh. Today's figures much better than the gloom previously implied - lots of $ earnings too!
I bought into IG Design (LON:IGR) earlier this year - 175p mark - so happy with the update and share price. It was their increasing exposure to overseas markets that looked good, especially as Sterling was on a clear downward trend. I also moved into other smaller companies with overseas exposure - Walker Greenback, LPA, etc. I think Paul is correct - the market is potentially underestimating the FX impact on smaller companies - the market marked up the bulk of FTSE100 companies - 70% of earnings are in foriegn currencies, but ignored the positive impact on smaller companies, probably due to their concern about the domestic economy post BREXIT.
RE. £D4T4 I had a quick look at this stock's half-year this morning.
IMO generally OK but nothing exciting. One thing caught my eye and this is a sharp increase in receivables. This has dented OCF anf FCF and turned them negative. Looking at the balance sheet, it now shows a total of £7m in receivables which roughly equates to 35% of annual sales. More than double previous year's.
It definitely warrants a close examination to understand why. Not one for me, I am afraid.
Hi Ramridge
RE: £d4t4 I had similar concernes when I saw the cash figures today but I am somewhat reassured by the comments from Finncap:
"Cashflow: A large project was invoiced (through partner SAS) at the end of
September, due this month. It left £4.7m working capital outflow in H1 and lifted
trade debtors from £2.8m to £7.0m at September. The resultant £2.6 Free
Cash Outflow and £0.5m dividend reduced net cash from £3.4m at last year
end to £0.1m. We are reassured this is a major, long standing global banking
client which is in good standing and payment is due imminently. With the usual
strong cashflow we expect D4t4 to finish the year with around £6.0m net cash."
Incidentally, Finncap have raised their target price to 185p following today's results - not that I pay too much attention to such things but nonetheless, it is a hefty upgrade. I also like that 78% of sales are in USD.
I hold.
I see a director has just bought 70,000 shares. I'm holding on for now.
Thanks crazycoops..
That pretty much explains the big rise in receivables. Now why couldn't the company have put a note along these lines in the half-year report?
Indeed Ramridge and on that point I have no answer!
I would be interested to hear any thoughts on Record Management. They are in the hot area of currency management which a lot of pension funds will be sorely aware of at present. They have a stock ranking of 98 and a yield even after a good share price rise of 4.8%. They have no borrowings and Management own a good chunk of the shares. I have nibbled to date but interested in taking more but just cannot quite get over a slight question mark in my mind which I can't identify. Any thoughts help much appreciated?
"I would be interested to hear any thoughts on Record Management. They are in the hot area of currency management which a lot of pension funds will be sorely aware of at present. They have a stock ranking of 98 and a yield even after a good share price rise of 4.8%. They have no borrowings and Management own a good chunk of the shares. I have nibbled to date but interested in taking more but just cannot quite get over a slight question mark in my mind which I can't identify. Any thoughts help much appreciated?"
Long-term holders of REC (which include me) may disagree with describing currency management as "hot".
Look back through the last five/six years and you will see a sad story of disappearing client mandates, declining higher-margin AUMe, stagnant revenue and standstill earnings. All to do with global QE killing the carry trade and with it REC's clever algorithms.
Management has talked for years of winning new clients, but nothing has been forthcoming on any great scale as yet. (Note that the business remains dependent on a handful of large customers.) The latest results showed client fees down 2-3%.
Bear in mind the management awarded every staff member a 10% pay rise last year, apparently to keep up with the wider City-employment market. It is a bit galling for shareholders to stomach that extra cost when the same staff have essentially overseen the aforementioned stagnant performance. I do at times wonder who this business is being run for.
Anyway, maybe one of those points is the slight question mark you can't identify.
That said, the business is flush with cash -- although I do have a growing sense that the hoard is there to keep the clients happy. So it may not really be surplus to requirements. Also, the group's margins are high and cash generation is superb. And the group's currency strategies all currently appear in positive territory for once.
If one day new clients can be won in the higher-margin AUMe categories, then we could be off to the races. I have been waiting for 'one day' for some time now.
Hi Mayn,
Still perservering with Record?
It must be close to six years now?
When the change in the world markets was blamed for the demise in Record's business model I seem to remember asking back in the day "What if the market stays like this for a prolonged period or worse never returns to the old behaviour?"
Best of luck
Phil
Hi Paul, would be great if you get chance to have a look at the d4t4 results out today, even if just a quick glance.
Thanks
Dom
Suggest its worth investors taking a look at the HY results from £D4T4 out this morning - very encouraging. Finncap have duly raised their price target from 140p to 185p.
£d4t4 , previously £ISL, problem with them IMHO was that whilst they report decent EPS each year, they do not make any FCF, not even enough to cover divis. but ive not yet checked todays interims.
Hi Paul would you be able to cover Patisserie Holdings (LON:CAKE) at some point ?
weve got a Pattiserie Valerie here in Nottingham and its always mega busy....hence why i bought a while back, expecting good results....which they were ! amazing balance sheet too.
Paul Re IG Design (LON:IGR): I see that Gervais Williams of Miton Smaller Companies holds IGR as their No1 stock and is keen on their management. He is reported to particularly like IGR's high sales to market cap (Stocko Price to Sales ratio of 0.73 yesterday before interim RNS), which will improve with +20% H1 sales. $/€ effect particularly helpful in this regard too. A medium term winner I think. Ian
Hi Paul,
Any chance of having a look over Kainos reported yesterday, got knocked off about 7% but off the back of a good run previous few weeks.
Lot of shrewdies in this one and seem to remember you were 50/50 when you last looked at it.
Cheers
Andy
Hi Paul.
Any chance you could have a look at CAKE later today?
There results look excellent again - their appears to be no brexit effect and new geographies (Northern Ireland) are trading well. The best thing is that store roll out is continuing at pace fully funded from internally generated cash flows, the cash balance is growing and they are paying a dividend : )
Quite pricey on a conventional p/e multiple but substantially down from their highs (less than 20 for the current year). Considering the growth (targeting 20 new stores per annum on an ongoing basis) this looks to me a great buy and hold.
Cheers
I'm really tempted to buy Patisserie Holdings (LON:CAKE) today as well. Everything seems to be going right for this company, but I'm still hovering on the buy button due to the valuation. To me the broker forecasts for next FY look on the money, they've factored in the 20 additional stores that are being planned (around 11% growth of the existing store network). Based on broker forecasts, it is coming out to a high teens EPS ratio, which is toppy for a retail chain. Therefore based on the current SP it looks like investors are currently paying in full for next FY's expected growth, and assuming everything goes well.
I think interesting catalysts for the company would be if they can accelerate the store rollout - they have the financial strength to do so, and also it looks like the beefed-up operational executive team to take on more. And also if they can make something bigger of their online ordering, as well as international expansion (maybe via franchises/licenses?)
I'm really tempted to buy Patisserie Holdings (LON:CAKE) today as well. Everything seems to be going right for this company, but I'm still hovering on the buy button due to the valuation.
I thought these were great results from Patisserie Holdings (LON:CAKE) and I just bought some more at 270p, but don't let that put you off :-) The numbers speak for themselves, but I found this bit particularly interesting with regard to the way they seem to be mitigating the effect of the Living Wage:
As anticipated, the largest cost pressure this year has been National Living Wage (NLW) which had a full year impact of £0.5m. However we introduced a more efficient labour rostering method in the year which has almost offset this increase. The increase to minimum wage from 1 October 2016 will be £0.1m and we will continue to monitor and react appropriately to future increases in the NLW.
I think I mentioned a while back that good companies would find a way of overcoming the additional cost by "more efficient labour rostering" and they seem to be achieving this. Also good news on business rates.
There's a lot to like about Patisserie Holdings (LON:CAKE) and IMHO you need to pay up for situations like this with great organic growth, very high gross margins and an excellent management team.
All the best, Si
I topped up on Patisserie Holdings (LON:CAKE) yesterday and thought the results were very good as well. I also noted that they had mitigated the impact of the NLW, and like you say good companies and by definition good management find ways to deal with headwinds, after all that is what good management should be doing, but its not the case in all companies.
I was particularly impressed with cash generation at Patisserie Holdings (LON:CAKE). Free cash flow was £9m for the year, and capex on new stores was £5.6m, so like others have said this is a self-funded rollout where they have sufficient capital to increase the store estate.
Like you said Si, sometimes as private investors, you have to pay up for quality companies, that are delivering strong organic growth, high margins and excellent cash conversion.
Regards,
Imran.
I was particularly impressed with cash generation at Patisserie Holdings (LON:CAKE). Free cash flow was £9m for the year, and capex on new stores was £5.6m, so like others have said this is a self-funded rollout where they have sufficient capital to increase the store estate.
Yes, I agree, the excellent cashflow generation and self-funding nature of the increasing store expansion is the key to the investment case. The fact it is being overseen by a top management team is the big cherry on the top. FWIW I don't think the current StockRank of 36 does Patisserie Holdings (LON:CAKE) any justice at all.
All the best, Si
"As anticipated, the largest cost pressure this year has been National Living Wage (NLW) which had a full year impact of £0.5m. However we introduced a more efficient labour rostering method in the year which has almost offset this increase. The increase to minimum wage from 1 October 2016 will be £0.1m and we will continue to monitor and react appropriately to future increases in the NLW."
It sounds so reasonable, a 'more efficient rostering method', but I wonder what the implications have been for the waiters, waitresses and sales staff in those shops.
On the other hand hard-core investors are probably peeved it wasn't in place before?
Patisserie Holdings (LON:CAKE) is making a lot of money, the board are extremely well rewarded, couldn't the bottom line have absorbed the increase? It's nearly Christmas, and it looks like the original Scrooge-like critics of George Osbourne's NLW look like they have been proved right, the benefit would in real terms never make it through to the people who it was intended to help.
£2.95 for a small slice of cake may not be all that cheap for everyone.
It sounds so reasonable, a 'more efficient rostering method', but I wonder what the implications have been for the waiters, waitresses and sales staff in those shops
Patisserie Holdings (LON:CAKE) is making a lot of money, the board are extremely well rewarded, couldn't the bottom line have absorbed the increase? It's nearly Christmas, and it looks like the original Scrooge-like critics of George Osbourne's NLW look like they have been proved right, the benefit would in real terms never make it through to the people who it was intended to help.
£2.95 for a small slice of cake may not be all that cheap for everyone.
I would have thought it's obvious what the implications are for staff. To be honest, I'm not really sure what your point is? I think you can find a moral problem with any business if you really want to, in terms of exploiting employees and/or customers, or should we only invest in not-for-profit charities? Have you ever bought anything from Amazon? If so, how does that square with their treatment of employees. Ever bought anything from a UK supermarket? How does that square with their treatment of their suppliers. Ever bought any clothes made in a sweatshop in India?
Probably best not bother investing in the stock market for people that get worried about such things, or buying anything from any retailer. Shit happens in the real world.
On the other hand hard-core investors are probably peeved it wasn't in place before?
I'm not sure I understand this either. Show me a business person that says his company cannot possibly be any more efficient and I'll show you a liar. In investment terms all I want to see is companies I hold adjusting quickly and efficiently to changes in circumstances which Patisserie Holdings (LON:CAKE) seem to have done. Companies that don't make such changes make very poor investments in my experience.
As for George Osbourne, the posting guidlines of Paul's blog do not allow me to say what I think of him, but if I hear him say the words "Northern Powerhouse" again I swear I will hire a hitman :-)
All the best, Si
CRAW-so basically similar to franchised business models which are now allowing store managers more flexiblity to move away from the 'model'? How much experience have these store managers got? They cannot be that well paid? I would suggest that in franchising( maybe an unfair comparator) then this move away from the 'proven' system screams the model is not working. It's not for me at the moment.
I agree completely, this notion of allowing poorly paid store managers to determine pricing is completely ridiculous. In the most recent interim they talked about installing a new EPOS system. If they paid money for the thing, they should really be using it and have someone at head office determining pricing. Anyway, this is northern England we're talking about, there really should not be the need for dramatic variations in the pricing of meat whether you're in Chesterfield or Chorley!
Having said that, I am starting to warm a little to Crawshaw (LON:CRAW). When you strip out expansion costs, there are real cash flows accruing to the business here.
Hi Tabhair
Crawshaw Store Managers - I think the idea is more to allow the store managers to decide what to sell, rather than how much to sell it for. Different shops will have different demographics - the pensioner is likely to want to buy smaller pack sizes than the large family. I'm sure all shops will cater to both - but with a nuanced offer.
The factory outlets tend to focus on larger packs, including reselling the bought in supplies (with no cutting / repackaging) to pubs, restaurants etc.