Small Cap Value Report (29 Oct 2015) - EGS, OMG, MTEC, SOLI

Good morning!
(I'm running late today, so will keep updating this article this afternoon, after lunch)
I enjoyed the latest small caps broadcast from Share Radio, with my friend David Stredder giving his views on a number of stocks. Of particular note, as ever, is the topic of Director greed. This time, my attention has been brought to the ridiculous remuneration of the CEO at eg Solutions (LON:EGS) who has plundered this tiny, and usually loss-making company for extraordinary levels of remuneration over the years.
I've looked at the last few Annual Reports, and extracted the following key data;
| Year-ended | 31-1-2015 | 31-1-2014 | 31-1-2013 | 31-1-2012 |
| Turnover | £7.5m | £4.5m | £5.0m | £4.7m |
| Profit/(loss) before tax | £407k | (£1,479k) | (£458k) | £146k |
| CEO total remuneration | £372k | £390k | £439k | £450k |
Adding up those figures, in the last 4 years this company made a total loss of nearly £1.4m, and paid its CEO £1.65m! You have to ask, what planet is this CEO on?! No wonder the company had to do a £3.2m Placing last year, to replenish its bank account - as the CEO's emptied it basically!
I am told that at a recent ShareSoc meeting, where the questioning can be tough, this CEO retorted to a question about her remuneration by saying, "If you don't think I'm worth it, then I don't want you as a shareholder!". Unbelievable.
So this stock is going on my Bargepole List as a result. It's always worth comparing Director pay with profits. It can then become alarmingly clear whose benefit the company is run for - and it's not shareholders, that's for sure.
There's nothing worse than management who use a small, loss-making company as a personal piggy bank. As an aside, it's a pity that Director expense accounts are not disclosed in Annual Reports, as I'm certain there are some horror stories there too at some companies - I've been told about some small cap Directors who enjoy lavish entertaining, first class flights, posh hotels, etc., all on the expense account.
I do wish shareholders would step up, and exert better restraint/control on Directors. No wonder we have so many corporate scandals, excessive pay, bonus culture, etc. The managerial class is totally out of control! I don't think Directors understand how angry private investors are getting about executive greed.
OMG (LON:OMG)
Share price: 41.9p (up 1.6% today)
No. shares: 117.4m
Market cap: £49.2m
Trading update - a solid update from this software specialist;
Vicon and Yotta have traded well in the second half, therefore overall the Group's full year revenue and adjusted profit are expected to be in line with market forecasts.
The Group has ended the year with a strong cash balance at £11.7m (FY14: £7.6m).
Market forecast is for 1.4p EPS for y/e 30 Sep 2015, so that means a PER of 29.9. However, if you deduct the cash of 10.0p per share, then the cash-neutral PER drops to 22.8.
Whilst that may look high, the interesting thing about this group of companies, is that performance has historically been harmed by one heavily loss-making company within the group. The losses from that company are now being eliminated gradually, so a much more profitable group should emerge.
EPS is forecast to rise substantially, to 2.7p in the new financial year, which would give a cash-neutral PER of only 11.8 - not bad for an interesting technology company.
My opinion - I've held this share before, and have been meaning to look at it again. It's on my potentially interesting list, so it's worth a look I think.
Matchtech (LON:MTEC)
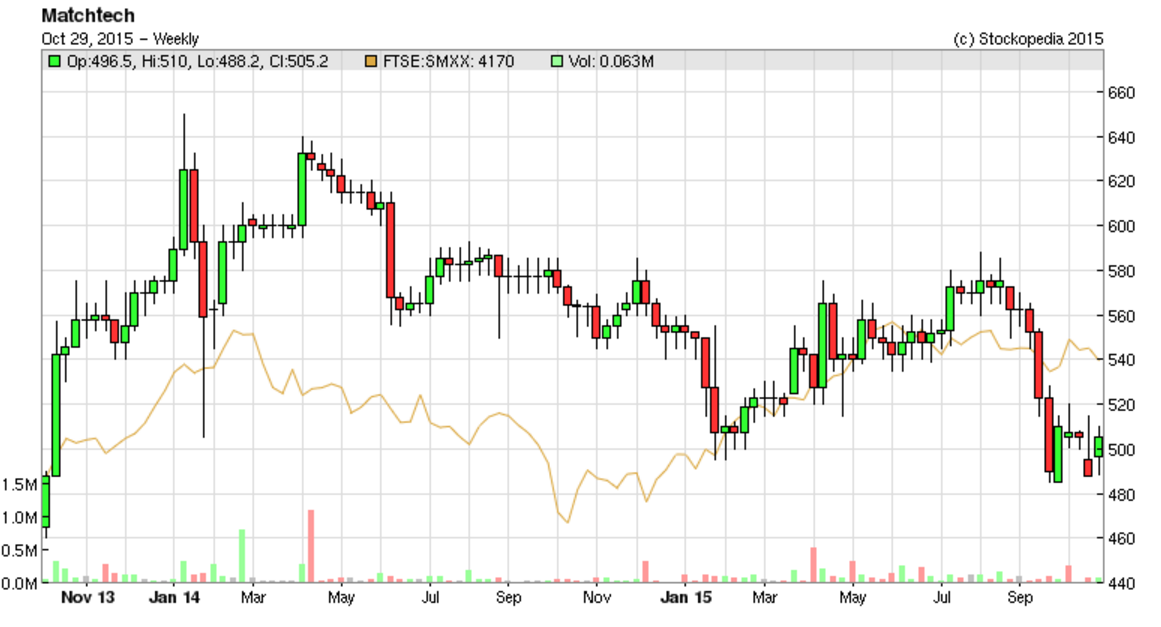
Share price: 505p
No. shares: 30.4m
Market cap: £153.5m
(at the time of writing, I hold a long position in this share)
Results y/e 31 Jul 2015 - as usual, I'm reporting my initial impressions on the results statement. There isn't time for me to plough through all the detail & narrative.
The key things I look for, are positive here. It's reported 45.3p adjusted basic EPS, reduced to 43.3p at the diluted (for share options) level. I'm not sure which basis the broker forecasts are calculated on, but the consensus is 42.0p, so the actuals are a beat at both levels.
Note that MatchTech did a substantial acquisition in the period, almost a merger really, of Networkers. The figures today only include 4 months trading from Networkers, and since it's decently profitable, that means there will automatically be another jump in profits/EPS for the next year, ending 31 Jul 2016, since a full 12 months of Networkers will be in those future results.
Forecast EPS of 47.9p looks a bit light to me, I'd be disappointed if the result is under 50p for the new financial year. So that puts this share on a fwd PER of only 10. That looks excellent value to me, for a good quality recruitment company, with some scale, and a sound balance sheet.
Dividends - very nice, with a forward yield of 4.6%.
Net debt - has risen considerably, due to the Networkers acquisition (which was part-equity funded, part-debt) to £33.6m, but in my opinion this is a reasonable level of debt, which does not concern me at all.
Balance sheet - staffing companies tend to have rather weak balance sheets, but this is better than many others in the sector.
Debtors seems a tad high, at £98.9m, but I think that's probably because annualised turnover is higher than the £502.3m reported turnover, due to the Networkers part-year effect.
Working capital (net current assets) is strong at £55.4m, so having £28.6m of long term bank debt to part-finance this looks acceptable. The current ratio is very good at 2.16.
Outlook - the CEO certainly sounds upbeat! Still, in a sales-orientated business, I like enthusiastic & positive management;
The 2016 financial year has started well in-line with management's expectations, with many buoyant markets across the Group's core sectors. The Group is realising cost synergies from the combination and early signs of sales synergies are coming through.
Looking ahead, we regard all our international locations to be a huge opportunity to advance our activities in local and regional markets across the world and are planning for substantial growth over the next few years.
We believe the high engagement levels of our exceptional people will continue to underpin the lasting loyalty of clients and candidates alike, delivering enhanced shareholder value and improved returns.
I am optimistic about the future prospects for the Group and look forward to strong growth in all our markets based on the truly global scale and the greater brand awareness that comes with leadership status."
My opinion - I already hold, and am buying some more today, it just looks a good business, reasonably priced, with maybe 20-30% upside on the current price, based on things as they stand now.
With management also optimistic about the future, and planning for substantial growth, then this strikes me as an excellent GARP share.
Why is the price depressed? I have a theory that it's possibly due to an overhang of sellers from former Networkers shareholders, who might still be taking advantage of greater (but still poor) liquidity to exit, for whatever reasons. I see such overhangs as a buying opportunity - if people want to sell me their shares at an attractive price, that's absolutely fine.
Note the high StockRank of 91.
The share price seems out of kilter with the positive results & outlook, unless I've missed something?
Solid State (LON:SOLI)
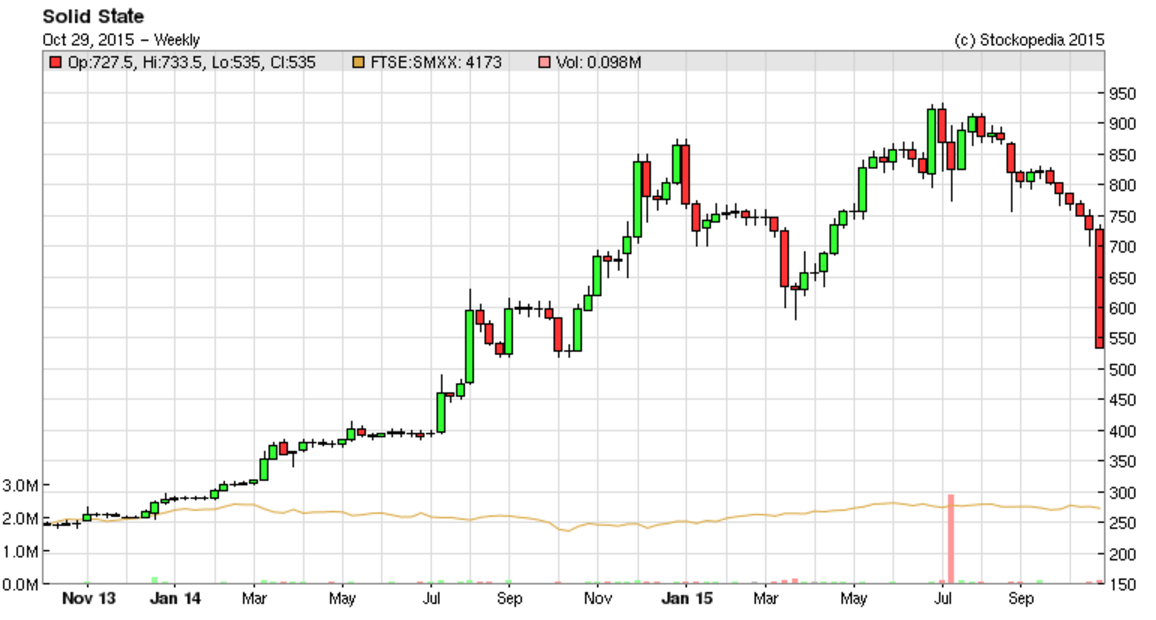
Share price: 530p (down 27% today)
No. shares: 8.4m
Market cap: £44.5m
Profit warning - a bombshell dropped on shareholders today at 1:15pm, and the shares have been sinking ever since. My commiserations - it's an occupational hazard for small cap investors I'm afraid - we all get hit by profit warnings from time to time.
It's just a question of weighing up the pros and cons, and then deciding what the best course of action is. The smallest shareholders have the luxury of being able to ditch their position immediately, but medium to large holders can't do that, due to liquidity restraints.The nightmare scenario is if a large holder decides they want out, and slams the price down repeatedly until they are out, which can take months with some companies. Then it takes time for confidence to return. Buying immediately after a profit warning like this one is nearly always a mistake, but often existing holders do so, perhaps in a subconscious attempt to arrest the fall in share price?
So what's gone wrong? Two things - general market softness, and a specific large contract being delayed.
Firstly, the company comments on H1, which sounds as if it's gone alright;
"Despite some softening in Solid State's markets as widely reported by industry peers, the Company has made a satisfactory start to the year. Results for the six months to 30 September 2015 are expected to show turnover and profits before tax of approximately £21 million (2014: £17.13m) and approximately £1.50 million (2014: £1.55m) respectively.
But H2 looks as if it will now disappoint;
"Following a customer meeting on 27 October 2015, delivery expectations for a material contract have been varied which will impact the second half of the year. The contract is high profile and a high priority for the customer and Solid State is confident that it is fulfilling its obligations to the customer.
"The Board continues to expect a second half weighting in the underlying business however, due to the contract variations and general market softening, it now anticipates that revenues and profits in the second half will be significantly lower than expected and, as a result, revenues and profits for the year as a whole will be below market expectations."
Revised forecasts - the house broker has put out revised forecast figures for the current year (ending 31 Mar 2015) as follows;
- Turnover down from £57m to £44m
- Profit before tax down from £5.3m to £3.2m
- EPS down from 56p to 36p
- Dividend from 20p to 12p (flat vs LY)
- 2016/17 forecasts withdrawn
Clearly then, this is a big miss, which would mean that EPS for this year would be little changed from last year's 34.3p.
Valuation - it's a matter of opinion how you value the company now. The prudent route would be to take revised forecast EPS for this year (of 36p), put it on a prudent PER (of say 8), and that arrives at a share price of 288p, which is about another 45% drop from where we already have fallen to.
Other investors might be prepared to pay a higher multiple, on the basis that this year had an unexpected wobble, and next year might be better. So perhaps put it on a PER of 10-12 times c.50p estimated EPS for next year. That would justify a share price of 500-600p. We're currently at the lower end of that range, at 530p at the time of writing.
My opinion - I'm trying to avoid contract manufacturing businesses, precisely because things can go wrong with contracts, and you suddenly lose 30-50% of your money when the company warns on profits. Companies with some degree (the more the merrier) of recurring revenues are much better bets, in my view.
I warned in my report here on 7 Jul 2015 that at 855p this share had become very expensive on the historic figures, so achieving forecast growth in earnings was vital.
More clarity is needed from the company, as to how this big contract is going to pan out now. It might be all systems go for next financial year, who knows? Investors do however need to think about what multiple is appropriate for a company with lumpy, unpredictable orders. I think a PER of about 10 is probably sensible, so a share price of say 300-500p perhaps?
It's worth noting that there was suspicious-looking selling for about 6 weeks prior to this profit warning. Were they insiders bailing out?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Thank you, Herbie. That's very helpful.
Paul, do you attach any importance to the fact that the only Stockopedia screen for which MTEC qualifies is the Beneish M-Score Short-Selling Screen?
I would take too much notice of that screen, HCM was added July 2014, since then it has gone up 2.7x, also on there is Trakm8 which has also done very well, since added it has doubled in price.
I think one reason its one there is the distortion of figures because of the Networks take-over.
Yo dawg, you missed year end results for SMJ, which offer great value. Mkt cap 47 mil, ntav 90-odd mil, of which 13 mil is cash.
Guys, I think that you are being a little unfair about the "Managerial Class." I am Managing Director of a small private company and unless there is money left in the pot at the end of the year I pay myself less than anyone else - even the apprentices!
I suggest that most readers of this board are "managerial" or "professional" class - this certainly includes Paul by background - so can we please be more specific when we take a swipe?
Hi Richard,
I don't think many here are knocking the small business owner-manager; I'm interpreting (rightly or wrongly) the type of director of a relatively small plc, typically with a small shareholding but a huge salary and share package relative to the size of the company.
These folk go on paying themselves over generous salaries and then on top of that large options with low or non-existent hurdles.
On top of that, sad excuses of NOMADS, auditors and other so-called advisors all have their snouts in the trough, gorging themselves on their fodder, which unfortunately is some hapless investor who has been mislead either by some crap tip in the daily mail, some discussion on a BB or worse some tin-pot broker such as the like that Rob Terry would invest in.
It's a wonder any of us still invest, given how much the deck is stacked against us.
I just had a skim through OMG (LON:OMG).
Its revenues have hardly budged in 5 years, and has an average ROCE of 6.3%. Free cashflow looks weak, and it looks like they're heavily capitalising expenses. Plus they raised £9m in 2013.
They make "image understanding solutions", which reminds me of Autonomy.
"The Group has ended the year with a strong cash balance at £11.7m". Yes, well, they raised £9m a couple of years ago, so that's hardly a major achievement on their part.
Can't say I'm enthused.
BWTFDIK
@Mark Carter OMG doesn't do it for me either but they are brave. Every few years they start a new business based on a different market for their technology. Sometimes they work (Vicon/2D3) and sometimes they expensively don't (OMG Life) and sometimes it takes a long time to establish as the firm learns about the market (Yotta - to be fair no-one saw Google Streetview coming). So unless the leopard has changed it's shorts you are betting that the next new business will work, or that the company will stick with developing Yotta and Vicon which both now seem to be relatively successful. It is OMG Life and House of Moves which cost money in recent years.
If OMG Life had been successful then it could have been very successful but introducing a new consumer gadget was always going to be a long shot.
The managerial class are out of control, possibly because most stocks are held by fund managers who do a fairly good job of feathering their own nests.
So any questions they ask might lead to the same question going in the opposite direction.
If the underlying owners of the fund and hence the stock had a mechanism to influence the process, perhaps the situation may change ? Although this is difficult to arrange in practice.
You asked if you may be missing something on the cause of the low SP for MTEC. Maybe the present depression in the oil and gas sector with its commensurate reduction in engineering vacancies will have a larger impact than you expect over the near future?
Re Solid State (LON:SOLI): This is what the RNS says: "“Following a customer meeting on 27 October 2015, delivery expectations for a material contract have been varied which will impact the second half of the year. The contract is high profile and a high priority for the customer and Solid State is confident that it is fulfilling its obligations to the customer."
This is how I interpret it: "The customer told us that they are very unhappy with the performance of our software and the progress of the installation and they have suspended further work by us until the performance issues are resolved. We think, however, that we are doing fine and are trying to persuade them that everything is ok. However, because they are big and important, we will have to incur lots of cost to put it right and to keep them happy."
Does "contract variations" mean "contract suspensions" by any chance?
The MOJ contract appears to have issues over IP that won't bounce back until next year , rumor has it Solid State is cutting staff, and the under performing Operations Manager at the Steatite business is to go ....
EGS loving the comment about her daughter. Come on, enlighten us ????
Maybe Elizabeth Gooch is just misunderstood? After all she rushed back to rescue the company just a couple of years ago when it looked like going belly up: http://www.telegraph.co.uk/finance/festival-of-business/10806545/How-Elizabeth-Gooch-came-back-to-save-eg-solutions-the-company-she-founded.html
OK the above bit is just a joke in case anyone thinks that I'm being serious! However the joke is really on shareholders isn't it?
Hi Paul,
Any comment on £REDD? I'm not a holder but they fit in line with Ed's recent articles about buying good quality shares hitting 52 week highs. This one is bolstered by the excellent recent record in dividends.
Ta
Chris
Hi Paul, The EGS situation is more alarming when you factor in her daughters salary as well, it certainly merits entering your bargepole list.
Hi Paul, like you I've held OMG (LON:OMG) before and received some nice divis. The elephant in the room for me was the failure to mention OMG Life in any way, shape or form - still an interesting company, particularly if they can sell the loss making one.
Regards,
Sully.
I owe an apology to whoever it was at the Sharesoc event grilling the CEO of EG Solutions - I thought his aggressive questioning overstepped the mark. She was upset by the end of the presentation and I sympathized with her. I now feel utterly, utterly stupid. Your figures are astounding.
Paul, One suspects that the CEO of eg Solutions (LON:EGS) talks a very good game but as you say doesn't deliver! The media coverage over the last few years suggests that her PR machine is very good at putting her in the public eye - to the extent that she was awarded an MBE in 2012. Click on her name from the Stockopedia list of directors and it pulls up plenty of press articles highlighting the fantastic success of her business. As you say the financial data doesn't back up the claims.
Echo a previous comment - would be interested to hear your views on Inland Homes (LON:INL). Today's results even allowing for accounting adjustments seem way ahead of market expectations - even those updated on 23rd July yet the share price has hardly moved.
I'd like to "second" the request for an opinion on the Inland Homes results. I have a some of these despite a few misgivings I had about some of the very financially complex (to me) announcements they made this year about adoption of new accounting standards (31/03) and a complex looking holding company loan by a subsidiary using zero dividend preference shares (13/08). Thank you, Simon
Elizabeth Gooch is the ceo. It is a staggering level of remuneration and no mistake.
The institutions are best placed to modify excessive rewards but certainly PI's can add their voice.
Paul, I nearly choked on my lunch when I read your post about eg solutions, and it prompted me to have a quick look. It seems that Gooch (CEO) has around 23% of the company. I'm not sure if this shareholding is due to options or from when she set up the company in the late 80s. Either way, far better to set herself a reasonable salary and then pay a dividend. Otherwise most PIs would not invest in what is clearly an instrument set up to feather her own nest.
And I can't believe the utter rudeness of what she said at a Sharesoc event. Maybe the company should not be listed in that case!
Matchtech (LON:MTEC) - Beneish M score high, any cause for concern?
Paul, the position at EGS is far worse than you suggest. Go back a few more years. 2011 paid £520,000. And back further still: 2003 £672,000; 2004 £825,000 and the winner, 2005 £1,086,000.
And was she worth it ? Operating profit in 2003 ££55,000; in 2004 £8,000 and 2005 £101,000. And cumulative losses 2006-15 are a loss of £1.96m
In thirteen years she has been paid a total of £6.5m.
Also any views on Ibex International (LON:IBEX) again, excellent results out today.
Paul, any views on Inland Homes (LON:INL) results today?
LWB All that an RNS should not be!!