Small Cap Value Report (3 July 2017) - PLA, QTX, FRP, TRAK

Morning folks,
Before getting into some updates, I thought I'd point out there was a really high-quality discussion in the thread for Friday's report, with a lot of comments on Game Digital (LON:GMD).
I'd particularly point out comments by Paul (who has a long position) and bestace.
I'm planning to update c. four stories by lunchtime.
Cheers
Graham
Plastics Capital (LON:PLA)
- Share price: 115.5p (-3.3%)
- No of shares: 38.9 million
- Market Cap: £45 million
Results for the year ended in March from this niche plastics manufacturer.
Plastics raised net £3.5 million at 117p recently, and suspended its dividends.
Paul and I have mostly been sceptical about this share, so perhaps I shouldn't dwell on it. Briefly:
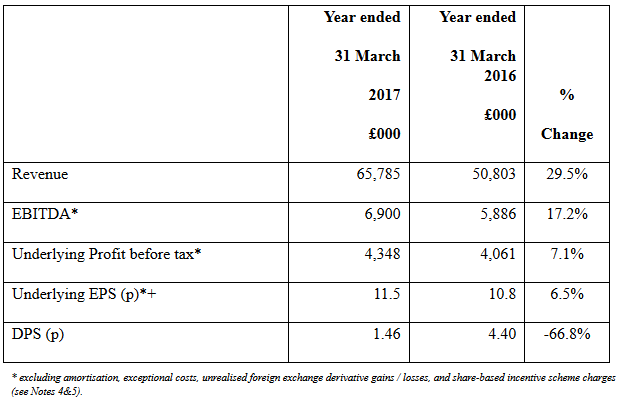
As you can see, underlying EPS is growing at a much slower rate than EBITDA and revenue, and that underlying measure involves quite a few adjustments.
The "like-for-like organic growth" reported by the company is 6.7%, about the same as underlying EPS growth.
It's a big exporter (45% of sales) and is set to benefit from the expiry of currency hedges.
Subsidiaries are classified by two divisions: Industrial and Films (plastic films!).
Of these, Industrial has produced the far more interesting growth rates this year: 27% organic revenue growth across the entire division, or 16.5% at constant currencies. Meanwhile, Films was up less than 2%.
Capital allocation for the year is summarised as follows:
In total, therefore we have spent approximately £6.7 million in these investment areas [GN note: capex, acquisitions and integration] compared to the £4 million estimated 12 months ago. We also spent £0.4 million to restructure and relocate of Chinese operations. Finally we paid £1.1 million out in dividends. All of this amounts to a total of £8.2 million and was funded by free cash flow of £3.7 million and an increase in net debt of £4.5 million.
I don't like being a perma-bear but I just can't get interested in a company which has the specific goal of doubling EBITDA (this goal being linked to management share options).
Targeting EBITDA usually means balance sheet expansion, rather than high-quality organic growth. Plastics has both raised new equity and increased its borrowings, which is perfectly consistent with this thesis.
Debt is now £16 million, while statutory profit for the year was £2.7 million if you add back the FX impact on derivatives and loans (otherwise just £0.5 million).
Outlook
"Trading for FY2018 started marginally below expectations but it is too early in the financial year to read much into this. We remain focussed on implementing the key initiatives outlined above as this will drive the long term growth of the Group and on improving day-to-day operational performance. The momentum of the Group as we finished FY2017 was strong and, if sustained, will deliver a strong performance in FY2018."
My opinion
I think it deserves a really cheap rating, probably cheaper than the current level.
Quartix Holdings (LON:QTX)
- Share price: 385p (unch.)
- No. of shares: 47.6 million
- Market cap: £183 million
A friend has flagged this to me, so it's my first time looking at this telematics business.
It has a business vehicle tracking system which helps management keep track of vehicle locations, mileage, driving times, driving styles, etc, along with a general fleet management service.
It has clients across the building & construction sectors, support services, transportation, security, distribution, etc. Pretty much what you'd expect.
2016 results, covered by Paul here in February, showed revenue up 19%.
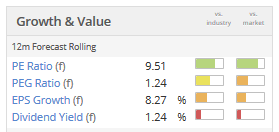
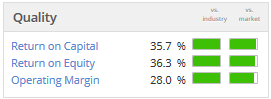
It's distinguished by very high operating margins and returns on capital, and the PE ratio is about 30x:
Today's statement sounds good to me, with some terrific growth rates:
"We have made good progress in all fleet markets. New installations of tracking systems grew by 44% to 14,300 vehicles and we ended the period with more than 10,000 fleet customers and over 97,000 active vehicle subscriptions. New UK installations grew by 44% to 10,450, increasing the subscription base to 78,000 vehicles; in France they rose by 30% to 1760 vehicles, reaching a closing base of over 11,400; and in the USA they increased by 60% to 2,090, lifting the base to 7,700 vehicles."
There is also an insurance side to the business providing data for car insurers, but management have apparently been scaling it back so as only to maintain that business when it offers attractive margins and returns - that's what I like to hear!
Most management teams prefer growth for the sake of growth, even if it's a poor use of capital.
What you really want is management with the discipline to shrink when something isn't working out properly. It sounds like Quartix has that.
This seems worth a closer look.
Fairpoint (LON:FRP)
- Share price: 10p (unch.)
- No. of shares: 48.3 million
- Market Cap: £5 million
Bank Debt and Funding Facility Update
This is below our £10 million market cap limit and the shares have been suspended but I thought I would mention it as a footnote to previous coverage.
The Company has today been notified by AIB Group (UK) plc ("AIB") that AIB has assigned its debt due from Fairpoint to Doorway Capital Limited ("Doorway").
Doorway is also going to lend money to Simpson Millar, the legal services division of Fairpoint.
It's hard to imagine that the existing equity is worth anything at all in these circumstances. I suppose you don't know for sure until the fat lady has sung. There's not a lot of public information at the moment.
But we do know that the annual report for 2016 couldn't be signed off due to the lack of support from AIB, and that bank debt was in the ballpark £20 million. So it looks like a 100% loss to me.
Trakm8 Holdings (LON:TRAK)
- Share price: 98p (-8%)
- No. of shares: 35.7 million
- Market cap: £35 million
This is another telematics business, often covered by Paul.
It has been a roller-coaster for investors over the past few years, and not a terribly happy one as the share price peaked over 400p in December 2015 before sliding back toward current levels.
In March of this year, it raised £2 million to reduce debt levels, with a placing at 65p. So participants in that placing have been doing ok so far.
Today's results are obviously quite mixed:
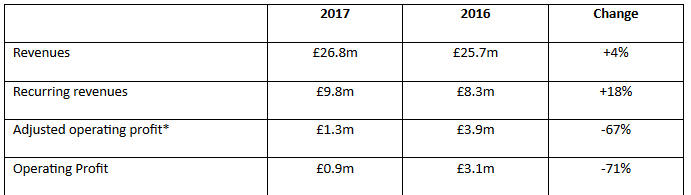
The adjustments to operating profit are "exceptional costs and share based payments", so to be prudent I would ignore these adjustments and use the £0.9 million operating profit figure.
Dividend: Suspended, which makes sense given that it recently raised money from investors. No point in raising money and then immediately giving it back.
New orders booked up 37%, with like-for-like growth of 33%. I'm not sure what to make of this, but with "renewed contract momentum", it sounds like it's picking up steam again?
The outlook statements are certainly promising a big improvement. Revenues for the first two months of this year are 10% higher than last year, and the Executive Chairman comments as follows:
We have recently announced new contracts with a roadside assistance technology company, and Mecalac, and renewed and extended contracts with Marmalade, Iceland Foods, Shell and Direct Line Group. These important contracts together with our strong pipeline of further opportunities provide additional visibility in our outlook for this year.
"Overall, we anticipate reaping the rewards of our investments as evidenced by our renewed contract momentum. As a result we are confident of achieving a much improved performance in the new financial year consistent with market expectations."
Operating costs have been reduced by £1.5 million.
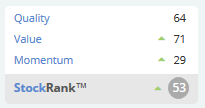
My opinion: The StockRanks are giving this a middling rating, and that's the best I can do, too.
Long-term, how will telematics companies maintain their competitive advantage?
Quartix and Trakm8 appear to offer similar fleet management and business vehicle tracking services. While I'm impressed by the financial returns achieved by Quartix, which reflect well on management, I think I need a bit more info on the specific product offerings and insight on how this industry might evolve over the next few years.
It's the classic problem with tech: what seems like an impressive piece of technology today might not seem very impressive in a few years. So which telematics products are still going to have pricing power in 3-5 years? Any informed predictions would be highly appreciated!
I'm not seeing a lot of other news today but I might add more later in case I've missed something worth commenting on - suggestions are very welcome!
Best regards
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Two things that stand out for me in Trakm8 Holdings (LON:TRAK) results - a large negative tax charge, and a large (and increasing) amount of capitalised development spend, both of which significantly flatter EPS. Last year they capitalised over £2m more than they amortised, which is significant relative to operating profit.
Thanks for that Gav
I wonder if Doorway have in some way "ring fenced" Simpson Millar? It seems odd to throw money at them without covering themselves with Fairpoint getting any benefit that results from the cash injection. Perhaps the devil is in the detail?
SQS Software Quality Systems AG (LON:SQS) is up today on a trading update. It seems a sound company with conservative management (I'm long).
I'm inclined to agree with davidjhill on this one. I can see no possible reason why Doorway would even consider it, particularly as they have backed competitors. I assume they judge that Simpson Millar ought to make a recovery, as a nationwide firm of reputation at a time when it is envisaged we will need more commercial lawyers to help with the problems of Brexit. Of course, what implications it all has for FRP as such are another matter.
The whiplash issue was fast becoming a drying well, long before the government began to mention it. Insurance companies, once awash with funds, would pay up on bogus claims because that was cheaper than fighting. As one who, for a while, supplied medical reports for such cases, spoke up at a joint meeting of docs, lawyers and insurance companies at a symposium at Barts. Each side wanted the other to be more proactive against the 'problem". Our trouble, as medics, is that we were highly sceptical that such a condition was common and we did not like the reaction we got if we put our scepticism into any report. It seemed to us that the lawyers and the insurance companies were cosy about it. Then, suddenly, insurance companies were poorer. Was that the changes brought about by Gordon Brown? Councils began to fight claims for tripping over paving slabs.
Similarly, the Government making it easier for any of us to go informally bankrupt was not kind to FRP
On balance though, I still don't see our need for lawyers disappearing any time soon.
Two very interesting announcements today for Tristel (LON:TSTL) one being an update on their EPA and FDA submissions in US, the other being an investment in an Israeli company producing a portable mobile phone based diagnostic system for HPV for which Tristel portable disinfecting products are an ideal partner enabling hospital standards of hygiene in portable applications.
As a company providing 'debt solutions' the Fairpoint (LON:FRP) situation is very ironic...
I sold out last November but the two lessons for me from this sorry tale are:
- Be even more sceptical when a company isn't being transparent about the performance of its business. It started when the Government made changes to whiplash and small claims and Fairpoint (LON:FRP) refused to reveal what it expected the impact on its business to be. Even when it did eventually provide some clarification it was in terms of revenue not profit impact.
- Be more wary of businesses growing through acquisition especially if it's not being funded through cash.
In response to the Fairpoint comment : I'm not sure why you draw the conclusion it is a 100% loss.....
AIB have offloaded the debt, presumably at sub par to Doorway. Doorway now own the debt and any repayment schedule and have also provided what appears to me to be new factoring facilities. That debt will inevitably need to be repaid at par plus interest.
Doorway are a specialist lender to law firms and know this particular market and the capital constraints very well. I suspect that the Directors have been dealing with them to take over the AIB debt (as hinted in previous RNS) for whom it is non-core and probably lack specialist skills required to properly assess the business.
Auditors could not sign off accounts due to lack of certainty around AIB. That is now cleared up.
There is no mention that the debt needs restructuring to wipe out equity.
So whilst I do agree with you that there is not really enough information in public domain at present there remains several possibilities with regards to the equity. I would imagine a further RNS is not far away when we will find out.
Thanks for flagging Quartix Holdings (LON:QTX) very interesting to compare it with Trakm8 Holdings (LON:TRAK)
QTX on 7.85x sales versus TRAK on 1.40x - I enjoy looking at similar companies and seeing if the valuation divergence makes sense.
I'm a little bit sceptical of the high level of profitability on QTX, because I'd prefer to see a small company in a fast growing, high potential sector not worry too much about reporting high returns....But that's a personal preference.
Disclosure, I'm long TRAK
Hi Graham re. Plastics Capital (LON:PLA)
By coincidence, GrinderTrader has written a good post today deriding companies whose accounts are heavily adjusted.
Here is an extract from PLA's accounts published today.
" Earnings per share
Basic earnings per share were 1.5p compared to 3.5p in FY2016. This is based on the shares in issue of 35.5 million shares (FY2015: 35.3 million shares). Adjusted earnings per share of 11.5p increased from 10.8p in FY2016.
"
Note the huge gap between the statutory earnings and the adjusted earnings. And with a sleight of hand, a fall from 3.5p to 1.5p on a statutory basis is transformed into an increase, from 10.8p to 11.5p on an adjusted basis.
These kind of companies go straight into my personal Room 101.
And the reason for the 'adjustments' is all too clear:
* an EPS of 11.5p shows up as a p/e ratio of circa 10.5 - i.e. relatively cheap)
* an EPS of 1.5p (statutory I.e. real EPS) would give us a p/e ratio of circa 80 - horribly expensive and only justifiable for a really good high growth business with a strong defensive moat.
Your conclusions are spot on. Companies with large and frequent adjustments go straight into the bin.
Thanks to you Graham and to you Ramridge for the analysis.
Cheers for that comment Ram. Me too, Room 101. Companies like this rarely go very far in the long-run.