Small Cap Value Report (30 Jan 2017) - CVR, SPE, WTM, FLYB

Good afternoon,
I haven't made the final decision about which stocks to cover, so please shout in the comments if you'd like me to mention something. Thanks!
Graham
Conviviality (LON:CVR)
Share price: 260p (unch.)
No. shares: 172.5m
Market cap: £449m
Half-Year Results for 26 weeks ended 30 October 2016
I have written very cautiously about these shares before, and I'd remain very cautious here, after today's results.
The group swings into pre-tax profitability of £7.4 million (up from a loss in H1 last year).
Ne debt is 1.2% below "pro forma net debt" (that will have been a tricky calculation, following on from a series of acquisitions), and is now £138 million.
And how about this covenant situation:
Leverage is comfortably below the Adjusted EBITDA bank covenant of 2.50x at 2.19x
At 87% of the maximum, it's comfortably below? Really?
Still paying dividends:
Interim dividend up 100% to 4.2 pence (H1 FY16: interim dividend 2.1 pence), which is currently expected to represent approximately one third of the anticipated full year dividend.
That 4.2p dividend is worth £7 million in total, so it's the entire pre-tax profit figure.
It's a big statement of confidence to suggest that c. £21 million in dividends could be paid out in total this year.
Interest costs added up to £2.7 million in the period. This might not seem much against the market cap or the near-£800 million in revenues.
My opinion: I don't think there is anything comfortable about the leverage here for what remains a low-margin business.
In that context, I don't understand how the dividend policy makes sense - it needs more breathing space for its covenants, in my view.
Management are heavily incentivised to grow EBITDA (contributing to a max 100% salary bonus for the CEO) and to grow EPS on a 3-year timeframe via the LTIP.
The shareholder base has obviously signed off on these policies, so in aggregate it must be content, but it looks to me as if management are incentivised to shoot for the moon - with all the attendant risk which that involves.
For these reasons, I view the low PE ratio and the dividend yield as value traps.
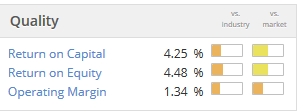
This Stockopedia table helps to illustrate some weak quality statistics:
Sopheon (LON:SPE)
Share price: 380p (+13%)
No. shares: 7.4m
Market cap: £28m
Posting this in response to reader request. Great news here:
"...a strong performance in the second half of 2016, driven by a large number of license orders in the final quarter, including substantial activity with major enterprise customers. In addition to the effect of the stronger sales performance, the profitability of the business was further enhanced by cost efficiencies over the course of the year, and to a lesser extent by foreign exchange gains linked to the sharp fall in Sterling.
As a consequence, the Board expects that reported revenues for the year ended 31 December 2016 will be in line with current market expectations. The Board also expects that, even when excluding the impact of the positive foreign exchange effects, EBITDA will be ahead, and pre-tax profits significantly ahead, of current market expectations."
So to be absolutely clear, the good news today is due to margins and not sales.
I haven't actually looked at this company before (it's great to engage with other investors, because you can get exposed to a lot more interesting ideas!)
Anyway, I see that these shares have "multi-bagged" over the past year, rising from 60p.
It's a software business, specialising in "Enterprise Innovation Management". Checking their website, I get the following summary:
"Sopheon integrated Enterprise Innovation Performance solutions support everything you need for the entire innovation, new product development (NPD), and innovation governance lifecycle."
And on the Introductory page for investors:
Sopheon (LSE:SPE) is an international provider of software and services for product life cycle management. Our Accolade® solution supports strategic roadmapping, idea development, product portfolio management and the creation, commercialization and replacement of products.
So that's reasonably clear, although without trying some of their software for yourself, or talking to staff, the company will inevitably feel like a black box as an investment.
When investing in software, a basic test is the strength of cash flow - does the company generate real earnings, or is it capitalising too many of its expenses?
Doing a quick test, I see that SPE capitalised £900k of development costs in H1, and amortised £1 million of intangibles (so that £1 million can be added back to net income, to arrive at operating cash flow). That looks like a fair match, and H1 in the previous year was also a fair match.
Checking the final results for 2015, I see a similar positive pattern in terms of the match-up between development costs capitalised and intangibles amortised.
So on an initial glance, I'd have good confidence in the earnings here.
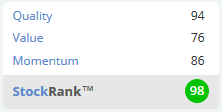
It has a huge StockRank of 98, and looks worthy of further investigation.
Waterman (LON:WTM)
Share price: 82.5p (unch.)
No. shares: 30.8m
Market cap: £25m
I last covered this engineering & environmental consultancy at its AGM, which included a slightly positive update to the end of October.
We are now updated for H1, which ran until the end of December.
This update is short, to-the-point and in line with expectations, so it's not much of a surprise to see that the shares haven't budged.
Waterman has experienced a positive interim trading period and the Board expects to report Interim Results consistent with market forecasts for the year as a whole, with revenue, profit and operating margin percentage generally in line with the prior year comparable period.
A continuing emphasis on working capital management has resulted in the Group expecting to report net funds at 31st December 2016 of £6.7m (£5.5m at 30th June 2016 and £6.6m at 31st December 2015).
Working capital management is not the most exciting of topics but it's crucial housekeeping for the majority of businesses.
Waterman's net funds position has evolved in the following way: £3.8 million (June 2015), £6.6 million (Dec 2015), £5.5 million (June 2016), £6.7 million (Dec 2016).
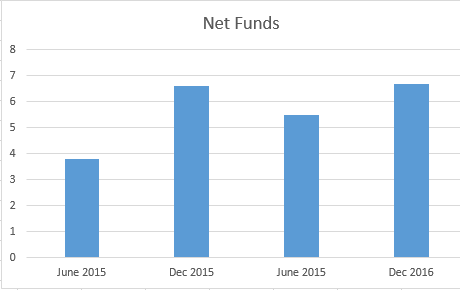
I'm glad that the company has emphasised this aspect of performance. It looks to me as if the movement in the net funds position has been about right, starting from that low in June 2015.
In the year from June 2015, WTM earned £2.7 million in net income and paid out £700k in dividends, so with perfect cash conversion and starting from £3.8 million, it would have reached £5.8 million in net funds by June 2016. It reached £5.5 million, which was close enough, and has gained an additional £1.2 million since then. That's slightly lower but within the ballpark of what might have been expected, given performance which the company has described as "generally in line with the prior year".
I see that the brokers left their forecasts unchanged here, as of last Friday. After today's update, there's no reason for anyone to change their mind on this.
Flybe (LON:FLYB)
Share price: 45p (-1.4%)
No. shares: 216.7m
Market cap: £98m
Flybe has a new CEO, formerly CEO at Cityjet from 2010-2015, who is upbeat on prospects:
"I have only just started work as CEO at Flybe. However, everything I have seen so far confirms my excitement at the opportunity we have to become the best regional airline in Europe. There is much to be done, but we have the firm foundations needed to develop the business. My first priority is to look to rebuild passenger unit revenue and to challenge all our costs. This will be assisted by Flybe becoming an even more customer-focussed business as we achieve greater control over our fleet size."
Today's statement reinforces the difficulty of the situation, telling us that "increased capacity and tough trading conditions resulted in lower load factors" in the most recent quarter.
Checking back to the H1 statement, the company said:
7.1% increase in passenger volumes to 4.8 million in H1 2016/17. The effect of adding new routes and rotations, together with a weak aviation market, meant that load factor fell by 4.3 ppts to 72.0%.
I tend to harp on about load factor, but it's the most basic requirement to have a successful airline. Short-haul airlines are even more sensitive, because of the need for ancillary revenue - and if the seat is empty, there is of course no ancillary revenue. The operationally leveraged business model, involving so many heavy up-front costs, can't afford this.
Today's statement informs us that load factor has fallen by another 1.7ppts, so that it was at 67% in Q3 (down from 69% in Q3 2016). By contrast, Ryanair Holdings (LON:RYA) achieved around 95% from October - December 2016.
Seat capacity at Flybe continued to grow, up by another 13%. It seems crazy to keep growing capacity when load factors are so low, but the statement insists that the growth in capacity has "started to slow". Four aircraft were added to the fleet, and another four are due, but six leases will be allowed to expire next year.
The balance sheet as of September shows net debt of £25 million (£142 million of cash offset by £167 million of borrowings), and net assets of £167 million which includes £247 million of aircraft assets.
My opinion: I don't consider this to be investable, or at the very least it's highly speculative, given the load factors and the likely difficulty of making a turnaround (though anything is possible, of course).
Perhaps the market cap at c. £100 million is a fair reflection of likely liquidation value, plus a premium for the chance that a turnaround could succeed? I doubt that, personally, but I'd love to be proven wrong.
That's all I've got for today, thanks for reading.
Best wishes
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
How delightful it was to see a confirmation of my own sense of disquiet about CVR. The company may well continue to do very well but I have the very same concerns about the core value. Having made a resounding profit, I cashed out today and set a buy-back alert of 203. Now I ought to find another Consumer Defensive to rebalance the portfolio but I have a sense that more troubled times may be looming fast for the entire market so I shall not rush into that.
In reply to johnrosier post 15.
Sorry John, fat fingers have intervened - meant to give you a thumbs up not down ( I blame in on the Pinot Grigio. I know it's sad, but it is a Monday). My apologies. Hope Stocko can remedy.
Thanks Graham for your detailed reports, you add a further dimension to the already awesome SCVR.
Thanks for covering WTM,Graham.Do you like it as an investment though ? You've sort of danced around that !
Graham - seemingly a good TU from INSE Inspired Energy today so wondered if you could cast your eye over this one?
Thanks for your comprehensive report on SPE. It is interesting to see that it has been in existence before 1996; Blew up then collapsed in Dot Com Boom , revived a bit to 2004 then started to fall again well before 2007 collapse which continued for them until 2015; then after just one year has suddenly revived yet again. The reasons they give are understandable but it seems a very big rise after such a long time ; does anyone have a better handle on the company ; what they really do and why has it taken so long for their products to be recognised ,seeing how long they have been around. Also like to know from those who hold it the reasons for buying back in Mid 2016. Many thanks
Hi Funderstruck -
In answer to your final comment, I bought in to Sopheon (LON:SPE) just after the Brexit vote in early July 2016. It seemed to be one of the few small cap stocks to be stable/ticking up in the immediate aftermath of the vote and I purchased a line of stock into my NAPs portfolio given the high rankings at the time (SR 99, V 83, Q 93, M91).
These rankings have been consistently high since and although the share price has had a few wobbles from time to time, compared to an entry price of 121p I am well up on the game. With hindsight I probably should have topped up but still not entirely sure of what exactly the company does!
Best,
Gus.
Hi Gus and Funderstruck,
I would think of Sopheon (LON:SPE) as a SAAS service like salesforce.
Salesforce is delivering enterprise CRM through sales and service automation and marketing database and campaign management.
Sopheon is enabling enterprise innovation which in its simplest form is ways to manage the capital allocation and priority projects that a business invests in across the enterprise and automating the end to end workflow through the different teams and stages to make them happen ... ideally fast, on time and on budget!!. Solving problems like this effectively and quickly is how businesses today are winning in making better websites, brining better products to market, creating efficiencies or becoming more agile.
I work for a global ecommerce company who's has invested billions $ in changing its structure, ethos technology and processes to prioritise investments in a data driven way, to drive constant test and learn and innovation through the business so that we can win and improve faster than others. This is bloody difficult to replicate even on a small scale, but a platform like Sopheon opens up a lot of these capabilities to smaller companies or legacy companies wanting to become more agile on a modular basis or across the enterprise. A low cost, light touch SAAS model means it has a very low barrier to entry for customers to start using it and then get hooked. Very compelling IMO!!
Key step up in my confidence is getting stats on new vs existing customer revenue growth and usage ... could become very sticky just like salesforce.
Happy holder!
Thanks Piecesof8,
for the explanation, as an Octo I am not abreast of current CRM methods which clearly utilise the very latest of technology to run the leading edge of the company. The capability of the clients for this system would be crucial for it's implementation or is that done jointly with Sopheon ?
Cheers. Tony.
Tony
That's why they have their own large integration service and business process service teams but are now expanding to integration and consulting channel partners who help companies implement and gives them more scale .... early days with the latter hence interesting growth ahead. Also it is fairly easy to just pick up and use as lots of templates and workflow already off the shelf if you start small and focussed.
Hallo Gus;
Thanks for the reply. Faith in the Stocko numbers certainly paid off here. interesting to see that since you bought the Q has inched UP due to big improvements in Roce ,ROE & doubling of margin. I agree about the business description , it struck me as Gobble de gook; put me off as seemed they have difficulty in clearly describing what they do.
Cheers Tony.
You're welcome Tony.
Taking this example into a wider context, Sopheon (LON:SPE) is one of several small-ish positions that I have bought into on a combination of Stockopedia number crunching and limited company due diligence to complement my usual approach of thoroughly researching and then taking a larger position on targeted stocks (usually trying to adopt a Q & V type approach).
Many of these factor picks are companies I had never heard of before screening them through Stockopedia so at the very least it has helped with my portfolio diversification. Rather than hunting big game all the time, I've tried being a "factor farmer" as well. So far the dual approach seems to be working quite well. Not all of these factor based picks have succeeded, but law of averages seems to working so far and this particular bit of the portfolio is up about 20% in the last 12 months or so. Jury is still out (not really seen what happens in an extended bear market yet), but so far this natural sceptic is quite impressed.
Best,
Gus.
For anyone considering a dabble in Flybe (LON:FLYB) , a colleague's son was formerly a pilot for them. He left recently to work for an air cargo firm. He mentioned rats and sinking ships!
Re: SPE substantial dilution?
RNS
Monday 21 March 2016
SOPHEON PLC
AMENDMENT TO THE TERMS OF CONVERTIBLE LOAN STOCK
Sopheon plc ("Sopheon", the "Company" or the "Group") announces that it has reached agreement with the holders of its convertible loan stock to defer maturity from 31 January 2017, to 31 January 2019.
In 2009 and 2011, the Company issued a total of GBP2m of convertible unsecured loan stock (the "Loan Stock") to a group of investors including members of the Board and senior management team. The Loan Stock was due to mature on 31 January 2017. The holders of the Loan Stock have now agreed to extend the maturity date of the loan stock by two years, to 31 January 2019. The conversion price of the Loan Stock remains unchanged at 76.5p per ordinary share. The interest rate of the Loan Stock remains unchanged at 8 percent per annum. Board members with an interest in the Loan Stock are Barry Mence (GBP640,000), Andrew Michuda (GBP45,000), Arif Karimjee (GBP27,000) and Stuart Silcock (GBP200,000). The current substantial shareholder in the Company with an interest in the Loan Stock is Rivomore Limited (GBP640,000).
The extension of the maturity date of the Loan Stock constitutes a related party transaction for the purposes of AIM Rule 13. In accordance with the AIM Rules for Companies, Daniel Metzger, as the director independent with respect to this transaction, having consulted with the Company's Nominated Adviser, finnCap Limited, considers that the amendment to the terms of the Loan Stock is fair and reasonable insofar as the Company's shareholders are concerned.
Re. Sopheon (LON:SPE) Convertible Loan Stock Amendment
I think the amendment has no immediate impact on dilution as far as I can tell. Here is the rationale.
The reports & accounts say
" For the purpose of calculating the diluted earnings per ordinary share (i) the group's convertible loan stock is treated as converted at 1 January 2016, with earnings adjusted for the amount of interest that would have been saved, and the number of shares adjusted by the number issued on such conversion, ...."
Since the terms of loan stock contract have remained unchanged except for the extended maturity date, the diluted earnings per share on February 1 is exactly the same as the value on 31 Jan.
I picked this stock up at 122p in June last year, so a very happy long term holder.
Sorry for failing to cover ATQT, FTC and PPHE! Appreciate the requests though.
Graham
Graham, I have held Sopheon for about a year. The reason revenues are flat while margins are on the rise is because of the progressive move to a SAAS licensing model.
Quote from Half Year report Aug 2016: "we are seeing rising evidence of prospective customers considering our private cloud software-as-a-service (SaaS) licensing model, rather than the traditional perpetual model that has characterized the majority of our business to date. This bodes well for the development of our recurring revenue base but could have an impact on up-front revenue recognition."
These results were outstanding IMO!
Any chance please of a look at Porvair (PVR)? Interesting little smallcap - results just out. Thanks
David. You mean £PRV
Hi Graham Filtronic (LON:FTC) Interim results seem to have greatly disappointed the market.
Hi Graham,
Thanks for your thoughts on Conviviality and I understand where you are coming from; it’s certainly no Bioventix!
It’s a low margin business but this story is about industry consolidation and increasing margins and returns through scale efficiencies.
You rightly question the statement Leverage is comfortably below the Adjusted EBITDA bank covenant of 2.50x at 2.19x.”
I too would like to see more headroom but think that it is a fairly stable business with thousands of customers and reasonably defensive in a downturn. Furthermore, working capital is near a high point ahead of the festive season and I would expect the situation to improve in the second half.
Further improvement should also come from the realisation of greater synergies moving forward. It is still early days since it acquired Matthew Clark, Bibendum and Peppermint.
You rightly say that it is a big statement of confidence that £21m in dividends could be paid out in total this year. I think that is exactly what it is. Management are confident about increasing margins and improving cash flow in the second half and going forward. I was encouraged by the strong trading in the first two months of the second half: “Group sales in November and December were 6.1% above the corresponding prior period6 with each business unit performing well. Retail like for like sales in the 6 weeks ending 1 January 2017 grew 2.1% and Conviviality Retail sales increased 6.9%. Conviviality Direct sales increased 6.2% and Conviviality Trading grew 3.1%.”
It’s difficult to argue against your view that it is a low-quality business with low margins and low returns on capital and equity as demonstrated by the Quality scores you show, because it is! (Although the overall Quality score of 70 is not so bad.) I just think there is a price for everything and in this case the story is of improving margins and returns. One is buying into a company, where management, through sound acquisitions has built a group that is likely to see higher margins and returns on capital.
I might be shooting myself in the foot here but the principal reason for Tesco’s bid for Booker is to realise huge buying synergies. Perhaps Booker will provide greater competition in beverage supply to convenience stores if the merger goes through.
It is one of my 27 holdings. My average in-price is 198p. Your post has certainly provided food for thought and has made me revisit my positive stance. In all honesty, given the 30% rise in the share price since the middle of December I was expecting the shares to fall back today; better to travel than arrive and all that. I am encouraged by today’s steadiness in a soggy market and am happy to hold on in expectation of a higher share price driven by improving margins and returns.
As you say, DYOR and just my opinion. I could be wrong, I often am!
Thanks for the fantastic comment and best of luck with the position, John!
Regards
Graham
I don't know if it's been noted on this board but it looks like their might be some storm clouds on the horizon for boohoo (which I hold) http://www.bbc.co.uk/newsbeat/article/38795537/boohoocom-staff-in-trouble-for-smiling-investigation-finds
Will this blow over, or turn into a sports direct size disaster ?
K
Hi Graham
Regarding your point about talking to the employees [SPE], a useful tool can be to check the companies glassdoor reviews, where people review their employer - https://www.glassdoor.co.uk/Reviews/Sopheon-Reviews-E12609.htm
As they are not a large company there isn't a huge amount, however the theme seems to be a good product, the project teams are quite pressed (possibly due to strong sales), and quite a bit of staff turnover.
Great analysis of Conviviality (LON:CVR) . Thanks for your insights.
Cheers FREng
any chance of having a look at flybe-some imorovement since last update
Conviviality's net-debt of £138.4m reflects seasonal working capital build-up ahead of Christmas trading so not as tight as it seems in my view. Cash generation is also very solid.
I agree on the incentives pushing for "all or nothing", though. Far from ideal.
Hi Graham,
Thanks for the update on Sopheon (LON:SPE), I've held for a while and I'm very happy with the performance of this share.
Could you comment on ATTRAQT (LON:ATQT) updates? How long do freezes typically last?
Thanks, Joe
The acquisition announcement for ATTRAQT (LON:ATQT) has a timetable of events. According to this timetable, resumption of trading is due to take place on 7 March.
I thought the end of year numbers from ATTRAQT (LON:ATQT) themselves I thought were good, insofar as a loss-making company can be! Yes it is loses money, but the gross margins, revenue growth were impressive. They have a very good product and it clearly has traction with customers, so I am ok with losses today to grow the business in the future. The important thing with this one for me is that the product is proven, their installed base is still tiny, so there is a huge runway on this one. Since much of the additional revenue is recurring, it will drop through to the bottom line as the company matures and grows. To put it this way, I think in five years time, they could conservatively be doing £10M revenue at an EBITDA margin of about 25%. From today's share price, that is (potentially a 4 bagger).
The acquisition though has really thrown me for six though. Firstly, the dilution for ATTRAQT (LON:ATQT) shareholders is nasty. The huge volume of shares hitting the market at 35p when the current market price is 46p is going to be a huge overhang. Secondly, the company who are selling Fredhopper SDL (LON:SDL) must be pretty pleased they are making a 4x gain on a company they bought for just £5M seven years ago now.
If I was a shareholder, I can't say I would be very pleased. Who knows what you're getting with this acquisition.
Hi tabhair,
Yes, waking this morning to read the results, I was pleased with the numbers (for a loss making company), I picked up a long position in ATTRAQT (LON:ATQT), mainly due to the success of their platform with Boohoo.Com (LON:BOO). Therefore, I felt the company was in a good position to attract (pun intended) more business. Currently a loss making company, but with high margins and a good client list I was willing to take a punt - this was back in the summer.
No sooner was I done reading the RNS this morning, they froze trading and released an acquisition RNS. It seems I have a lot of time to dissect this information now. It certainly dilutes my position in the short term; however, I'm hoping with a bolstered client list, increasing revenue and high margins, it may work out in the long term.
For the moment, I'm stuck with it. But as part of a well balanced portfolio, hopefully it won't hurt me too much....
Cheers,
Joe
Hi Graham.
I would be interested in your thoughts for PPH as a read through for the market regarding tourism in the UK. Although only about a 3rd of there revenue is from here.
Either way update seems generally positive considering the new hotels they are adding to the portfolio.
Thanks
Sean
Thanks guys, I'll cover SPE and WTM.
Me too please for Sopheon (LON:SPE) - it's been top of the Stockrank charts for a while now. Also maybe worth a comment on Waterman (LON:WTM) who reported an in line with expectations update - a bit of a "canary in the coal mine" as a barometer for sentiment in that sector of the UK small to mid caps.
Thanks,
Gus.
WTM -Waterman,please Graham.
And a third for Sopheon! Luckily I bought in on dip before results, want an opinion
Hi Graham, yes please Sopheon.
Hi Graham, Sopheon (LON:SPE) please - positive trading statement today.