Small Cap Value Report (31 Dec 2015) - SMXX

Good morning!
Well, here's my last SCVR of the year - making it a grand total of 251 reports in 2015!
I did a year-end recap on my own portfolio(s) results this year here, in my 24 Dec report, for anyone who hasn't already seen that.
2016 Charity Challenge
I like to do something worthwhile for charity each year, so have come up with a dual-purpose challenge for 2016.
1) Total abstention from alcohol for the whole month of January 2016. I usually do this anyway, so thought I'd add a twist this year, namely;
2) Instead of having fun nights out at the weekends, I will spend my weekends in Jan 2016 writing a report analysing small cap profit warnings from 2015. I've been meaning to do this for years, but never had time, as it's a big project, so have decided to make some time in 2016.
The idea is this - as I already report on most (nearly all) significant profit warnings in small caps in my SCVRs, then I'm going to re-read all 251 SCVRs from 2015, pick out the profit warnings, and prepare both some data, and summarised commentary on each one, then analyse what happened next.
The key themes will be - what percentage of shares recovered from profit warnings, over what timescale? Do profit warnings really come in threes? Is there an optimum time to buy x days/weeks after a profit warning? Are there any patterns from various sectors? Could profit warnings have been foreseen & therefore avoided? If so, what were the best signals in advance that something was going wrong? Should we sell on the opening bell when a profit warning occurs, or sit tight and ride it out? Should we average down on a profit warning?
It might prove too much work to cover all 2015 profit warnings, but I'll make a good stab at it anyway, and will aim to complete my report by the end of Feb 2016.
Ed mentioned that he would allocate me some time from a researcher to do more statistical analysis of profit warnings over the summer of 2016, so we might then be able to use my report as the starting point for a deeper mathematical approach, mining the data properly (whereas my approach will be more high level, as I'm not a statistician).
So the charity sponsorship will be to help motivate me to have a boring month with no boozing, and spending my spare time writing the profit warnings report. Feel free to sponsor in advance, or to wait until it's done. I'll set up the charity donations page shortly.
On to today's results. Well, there aren't any interesting ones - just a handful of junior resource stocks rushing to get 30 Jun 2015 accounts filed before their shares are suspended. Late accounts is a major bugbear of mine - and it's usually companies with the smallest, simplest accounts that take the longest to file them too. It shows contempt for shareholders, disorganisation, incompetence, and usually financial distress - as late accounts can often be due to auditors refusing to sign off re going concern.
Looking at results for 2015 overall, I find that a lot of people benchmark themselves against FTSE 100 Index (FTSE:UKX) - but unless your portfolio is focussed on the largest companies, it's a meaningless comparison, because the index is so overweight with oil/gas and mining shares, banks, etc. Obviously it's been a terrible year for the resources sector, so that has pulled down FTSE 100.
FTSE Smallcap Ex Investment Trusts Index (FTSE:SMXX)
I prefer to focus on SMXX and AXX as my two comparator indices, and they've both had an OK year overall.
If you're a Stockopedia subscriber (it really is worth every penny - and is my main tool for researching stocks & searching for ideas), then just put in SMXX into the search box, and that will bring up a very useful page showing not only charts, and stats on the small caps index (excl. investment trusts), but also shows all its constituents with customisable displays of data, that you can sort on any criteria you wish to. Here's a screen shot (which I have sorted by Stockopedia StockRank);
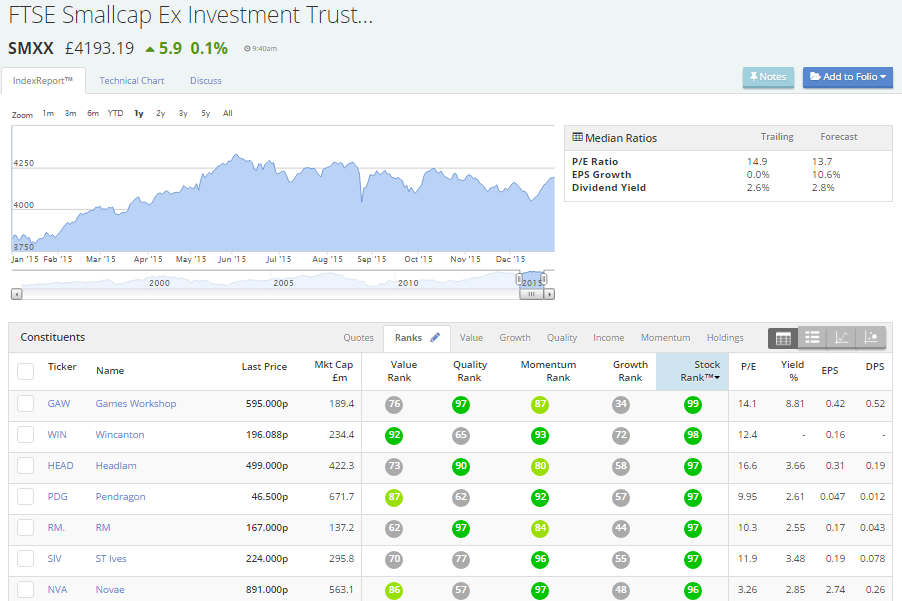
I'm surprised that the median forecast PER is only 13.7, so maybe there is more value in this index than I realised? That has prompted me to have a rummage and look for some bargains.
Note that good gains in small caps happened in a very strong patch from Feb-May 2015, but since then the index has drifted down gently, although a good Santa Claus rally has happened since 14 Dec 2015.
Overall then SMXX is up about 9.8% in 2015 at the time of writing (10:00 on 31 Dec), a respectable performance. With divis on top of that of course, so a total return of c. 12-13% - pretty good.
AIM All-Share Index (LON:AXX)
Turning our attention next to the controversial junior market, characterised sadly by its lax regulation, and where I would say that about two thirds of the companies on this market are complete junk, by my investing criteria. Some of them are worse then junk actually - as we saw very clearly in 2015, AIM has become a magnet for frauds from all over the world, particularly China. Some City firms willingly participate in and promote these frauds (or at the very least turn a blind eye), in return for lucrative fees. Shame on them, and of course such firms will inevitably go out of business in the long run, because after a while nobody will trust them, or any of the companies that they represent. It's amazing that this clear-out of dodgy advisers hasn't already happened. Investors are too forgiving, and should instead boycott firms which have consistently tried to sell them pups in the past.
Perhaps the highest profile fraud this year occurred at Quindell - where Rob Terry (and almost certainly others) were exposed for having cooked the books. The SFO are currently investigating, and Quindell was forced to admit wrongdoing, and restate its accounts, so let's hope that particular serial conman ends up spending some time at Her Majesty's pleasure. Otherwise, what's the point in having laws at all, if there are no consequences for breaking them? This country is ridiculously lax on punishing white collar crime. Well done to Tom Winnifrith for his astonishingly detailed investigative work on Quindell.
It is this failure to punish white collar crime in the UK which led one ex-banker to cheerfully comment on CNBC a while ago that US firms weren't worried about dodgy dealings, because "we just outsourced our fraud to London". What a state of affairs where the UK is becoming known as the place to commit fraud with impunity. A whole new regulatory/legal approach is needed, with a major clampdown on wrongdoing of all kinds. From what I can gather, UK regulations seem to just heap administrative burdens onto the honest.
Another significant fraud on AIM was of course Globo (GBO). Some investors chose to ignore a sea of red flags, and numerous warnings, including the 29 articles I wrote here, over 3 years, warning of the dangers lurking at this company. My articles are available here. One of my goals for 2016 is to produce a video, demonstrating all the warning signs at Globo - there were at least 13 significant red flags.
One or two red flags can maybe be forgiven, or explained, but in my experience where you have many red flags in combination, then the risk of it being fraudulent in some way rises exponentially.
It simply amazes me to see the capacity for self-delusion that so many investors have. Once they buy a stock, they simply cease to think. They instead reprogram their mind into blind faith, and shouting down criticism of the company. This is a natural urge in all of us, indeed I find it welling up within me too, far too often. Whenever that particular monster raises its ugly head, I actively force it back into hibernation, by engaging with bears, and listening to what they have to say. That has saved me a lot of money in the last two years - being one of the first into the lifeboats means you can escape the sinking ship relatively safely.
Stockopedia readers are often the first to hear about dodgy accounts, as my track record in the last couple of years shows that I can usually sniff out accounting problems from a hundred yards!
The absolutely key figures to look for, are inflated debtors. That is nearly always the giveaway. After that, you look for excessive capitalisation of costs into intangibles. Artificial profits require assets on the balance sheet to be over-stated, or liabilities under-stated. So it's the balance sheet which is where the bodies are buried. If anything looks wrong on the balance sheet, then don't touch the shares. That applies to quite a lot of overseas AIM stocks, so I don't touch any of them, with perhaps just a handful of exceptions, and exercising great care even then (i.e. only very small position size).
With AIM, it is important to remember that there are perhaps 300-400 good companies (some excellent ones) on AIM, which are profitable, do pay divis, and in some cases will be the stars of the future. So I feel it's wrong to rubbish the whole market. Part of it is good, and of course there are excellent tax breaks, in particular the Inheritance Tax loophole, which you could argue makes IHT essentially an optional tax - or payable only due to overlooking the need for tax planning perhaps?
Here's the same Stockopedia index page for AXX, sorted again by highest StockRank;
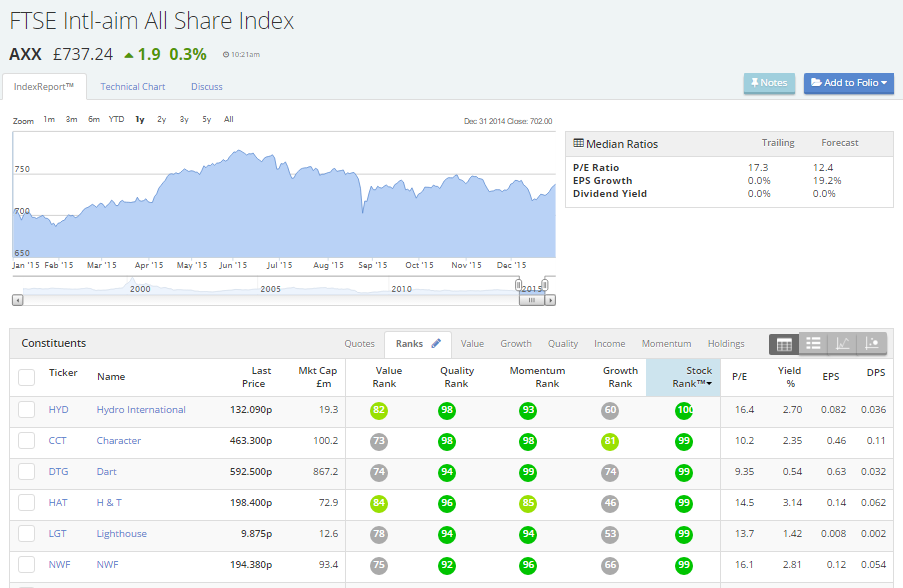
Note that the forecast median PER is only 12.4 on AIM, indicating that again there might be some decent, overlooked value, still lurking undiscovered. I'll have a good rummage here too. Mind you, one does have to be careful with forecast earnings, as often a huge leap in EPS is forecast, but doesn't materialise. So the actual PER might turn out to be higher.
Overall, AIM rose about 5% in 2015, which isn't a bad result considering how much rubbish there is in this market - although the junk is mostly smaller market caps, so has a lower weighting.
There's an article in Investors Chronicle today from one of the smartest investors I know, Mark Lauber, which is well worth a read if you subscribe, it's here. Coincidentally, Mark has covered a lot of the issues which I mention above, and gives common sense rules for how to avoid heave losses, or worse still frauds.
Well worth a read, and one of the best articles in IC for a long time. I'll see if I can persuade him to do an audio interview with me in the new year!
(this article is being updated in stages between 10am & 1pm)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
Solid State (LON:SOLI)
2nd April 2015: Trading Update
"The results for the year ended 31 March 2015 will, as anticipated, be significantly better than last year. Profit before taxation for the year ended 31 March is expected to be at least in line with market expectations although revenue is expected to be slightly lower principally due to exiting certain low margin, high volume business in the LED market during the year.
The Directors are confident that further progress and growth will be achieved in the current financial year. The current financial year commences with an open order book of 18.5m (30 April 2014: 14.7m) and an encouraging level of enquiries. In addition and as expected, the year will also benefit from the first material contributions from the three year contract with the Ministry of Justice, awarded last year, to supply monitoring hardware for GPS offender tagging."
Again everything looks pretty good, revenues slightly down because of ending of low margin contracts.
Then nothing until 29th October: "Following a customer meeting on 27 October 2015, delivery expectations for a material contract have been varied which will impact the second half of the year. The contract is high profile and a high priority for the customer and Solid State is confident that it is fulfilling its obligations to the customer."
Bang shares crash about 40% and fall further in following days. So again no warning I can see, although SOLI does relie on certain large contracts. The warning was the large director sales in July/August 2015.
Thanks,Herbie,but what was the warning [in the statement/signal] for Amino ? [As opposed to the actual profit warning].
Yes, definitely very useful!!! Particularly
"Could profit warnings have been foreseen & therefore avoided? If so, what were the best signals in advance that something was going wrong?"
I have been working on textual analysis of management statements, and seeing if a close reading of what management say in their statements signal any "red flags" (eg contradictions, incoherence, inconsistencies). I've just done it for banks though.
I think sometimes there are warnings in the statements, I think Paul in his reviews does a good job at highlighting these and other signals.
One I had experience of recently was Amino Technologies (LON:AMO).
21st July 2015 Interim results everything looked very good: "Today's results mark a real turning point for Amino. Following a significant amount of hard work, and thanks to a clear and well thought-out strategy, our business has reignited its organic revenue growth, extended its margins and profitability, and begun to put in place some very exciting building blocks for the future.
Our financial strength is allowing us to be bolder in our plans for growth. Our acquisition of Booxmedia Oy extended our credibility in customers' eyes as an innovator in the TV space. Today's proposed acquisition of Entone takes that credibility one step further still, not only adding excellent product and people to our offering, but transforming the scale of our business too. We enter the second half confidently and are excited by the long-term potential for a bigger, bolder Amino."
Then 2 contract wins in September. Then trading update 27 Oct 2015: "The Company now expects to report a second half shortfall in revenue versus expectations within its core Amino business. As a result, the Company expects profit before tax, before exceptional items, to be below expectations, but in line with that achieved in the previous financial year."
Shares fell 32%, did rebound a bit but now drifted down to around that level.
I will have a look at Solid State (LON:SOLI) next.
Thanks for the link Ramridge, a very interesting commentary. I note that on the same website there is also a quarterly report on LSE IPO activity, another useful resource.
Gus.
Hi Paul -
Re. Profit Warnings . In case you haven't come across this, EY do a quarterly analysis of UK profit warnings. Here is the link
http://www.ey.com/UK/en/Issues/Capital-and-transactions/Restructuring
You can download the full Q3 2015 report from the website. Useful material for the start of your analysis.
Yes very interesting, 3Q 15 is nearly 4 year high, but 2Q 15 was 2 year low, so all eyes on 4th Q, 4Q 2014 was a 6 year high. So is 3Q high because 2Q was low? Last 4 years the 4Q has been the highest quarter.
Hi Ramridge,
Many thanks for the links to the EY profit warnings reports. Looks useful background, but unfortunately they don't seem to give any individual company information, just summaries by sector, etc.
I might email their analyst to see if they would let me have sight of the granular detail, which is what would be more useful for me, as I'm really more interested in what's happening at the individual company level, and whether profit warnings could have been anticipated. Plus whether to sell on the warning, hold, or buy more. Or what is the optimal time to buy after a warning, that's the kind of thing I'm focusing on.
Regards, Paul.
Hi Paul - Yes I thought you will need the granular stuff for your purposes. You can of course contact EY for the raw data, although having dealt with them in the past, they are pretty protective about their research data, as opposed to freely disseminating reports designed to attract new clients.
Paul,
Just wanted to say thanks for the daily reports throughout the year. Your expertise around interpreting balance sheets has been a great help to me. I wish a prosperous 2016 to you and your readers.
Cheers
Paul
Thanks for these excellent reports. Look forward to reading loads more in 2016 and beyond.
Andy
As always Paul gives invaluable research details and is completly unbiased , lokk forward to his articles every day
It's easy to transmit apparently sencior words in online messages but your effort and guidance really is appreciated.. I still don't really know what I'm doing so reading your reports every day provides an honest and trustworthy education for me.
Thankyou very much and have a happy new year.
Thanks for all the kind messages, much appreciated!
Regards, Paul.
Paul
I do not have a lot of time and I find your insights and pointers most helpful. After reading your reports and doing a little research I bought both Avesco and Boo Hoo ( among others) and sold Tungsten far earlier than I might otherwise have done. Helped me towards a great result
Also as a result of you daily reports I have subscribed to this site which I find invaluable. Seems to suit my investing style.
Happy New year and Thanks
Brian
Hi Paul,
Many thank you's for all reports during 2016.
All best wishes for 2016
all the best
Richard
To echo what others have said, thank you Paul for your articles throughout the year - I started looking at them about a year ago. Reading them has I hope made me a wiser investor.
Looking back on my own investments, it's been an interesting year. My top performing holding by far has been 32Red (LON:TTR), whereas I took most profit from Amur Minerals (LON:AMC). But the real lesson is not to hold on to the lemons - I've had too many serial disappointers where I failed to cut my losses in good time. Good luck with your research - I think there's a lot in the "do something" motto...
Hi Paul. Thanks for sharing your insight and experience - I'm a fairly new PI who found you in 2015, and for whom everyday's a school day - it's great to have found a tremendous teacher! You've definitely saved me from a few mistakes, and pointed me in the right direction for some successes.
All the best for 2016,
Dan
Paul - thanks for your excellent and consistent analysis throughout the year.....just wish I'd found your website before investing in Quindell which looked like a sure-fire winner on so many counts....I didn't realise that companies were allowed to lie through their teeth in a "regulated" environment.....
Hi Paul I only came across you in the past couple of months, but have already become a big fan. I have followed a number of people in the past, most recently, Robbie the Naked Trader, however, I find your in depth reviews and honesty add a different dimension and I will certainly be following all you r reports very closely in 2016!
Keep up the good work and have a Happy New Year.
Regards, Max
Hi Paul - I would like to add my thanks and best wishes for 2016. Your reports and commentaries have made a major difference to my investing approach and results.
More power to your elbow.
Regards, Ram
I'll echo others on here and say thank you.
Personally you also make investing a less lonely affair...I'm a PI with a full time and don't know any other investors so it's good to hear from you and others who talk about companies, investing and your personal viewpoints :-)
Thank you Paul for all the SCVRs and great analysis contained therein.
Wishing you a very happy and prosperous 2016.
All the best,
Steve
Thanks Paul for all your reports. Best wishes for 2016.
Best wishes for a Happy New Year Paul... and all readers too.
Paul - a big thank you for all your reports this year. I have learnt a huge amount.
I look forward to your profit warning analysis. It's anecdotal I know but there seem to have been a lot of "warnings in H1 but don't worry H2 will be OK " this year. I wonder whether this can be tied back to management somehow.
Thats interesting about the SMXX, did not know about that feature on here. Had a quick look at indexs and the All Share has not performed very well over the last 10 years, only up about 20%, the FTSE250 is much better up about 100%, the Techmark100 is up around 270%.
I read The Art of Execution by Lee Freeman-Shor a couple of months ago. I recommend it. One of the main points I took from it is that you should always do something when things turn down. The successful investors either sell up and move on or add to their positions. It's the ones who get caught like rabbits staring into the headlights and do nothing that do worst.
I have found this a useful insight. Adopting the "do something" rule forces you to ask yourself if you have real conviction in the investment. If yes then add to it on the dip. More often the answer is no and it's best to get out quickly rather than hoping something turns up.
Paul,
Interesting article, and I will take your advice on SMXX. Interestingly, my portfolio has returned 7.5% this year, as opposed to 9.8% on SMXX. I have always benchmarked myself against the FTSE All-Share, but will now benchmark myself against SMXX, as it is probably more aligned to this. Happy New Year.
I think that your choice of benchmark should depend upon what it is you are measuring. I use the FTSE 100 as using an index tracker is the default option for me. Everything else (overseas funds, small cap etc) is a matter of choice designed to (hopefully) improve performance. So the test for me is not just stock picking but also allocation. These are strategic decisions about where to put your money - in reality the bulk goes in to small caps, but this is my strategic choice so I just need to know how I am doing against the main alternative use for my money. (If the main alternative is a bank deposit then of course the bank rate would be the appropriate benchmark).
If on the other hand you want to measure your small cap stock picking skills then clearly AXX or SMXX is most appropriate as it has the same investment universe.
The most sophisticated (complex) option is to a] measure the overall performance against the broad strategic benchmark (eg FTSE 100, bank account interest, FTSE All-World etc) and then b] measure each component asset class against the appropriate benchmark (eg SMXX for UK small cap). In fact now I've thought it through I might just do that later today!
"mining the data properly" Requires a sound hypothesis to test in the first place!
Paul, thank you for all your reports in 2015,
for your insights and knowledge that I lack,
for your very human and personal style.
Very best wishes for 2016.
Enjoy "Dry January" in that wonderfully green
and pleasantly alcoholic land.
Best wishes,
Jane.