Small Cap Value Report (31 Jan 2017) - CPR, JOUL, QRT, ALU, SCS

Good afternoon,
Apologies for the slow service today.
I thought it worked well yesterday, taking suggestions about which stocks to cover.
So if you have any suggestions, please let me know.
I provisionally intend to cover:
- Carpetright (LON:CPR)
- Joules (LON:JOUL)
- Quarto Inc (LON:QRT)
- Alumasc (LON:ALU)
- SCS (LON:SCS)
Thanks
Graham
Carpetright (LON:CPR)
Share price: 185.5p (+6.6%)
No. shares: 67.9m
Market cap: £126m
I covered Carpetright recently, in the SCVR of Dec 13th.
That was the interim results, when the company reported:
We have made an encouraging start to the second half with a return to like-for-like sales growth in both businesses. As we enter the important January trading period, we remain comfortable with the range of market expectations.
It has certainly delivered on that today, confirming as follows:
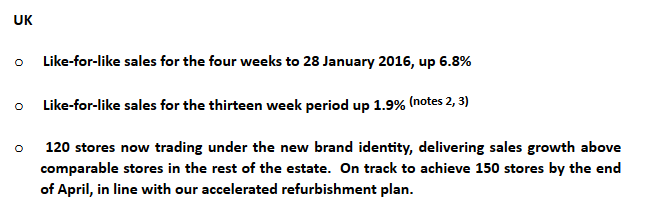
Other bullet points:
- Number of UK stores reduces slightly to 427.
- Rest of Europe like-for-like, constant FX sales (the best measurement) are up 5.4% (in reported currency, up 22.4%).
- The CEO comments and lets us know that the store refurbishment plan is on track. Excellent news.
I haven't got much to add to what I said last time - namely, that I think there is a good chance that management can execute their investment plan, at considerable cost but with the opportunity of creating attractive medium-term benefits.
More than three quarters of CPR's operating cash flow in H1 was spent on the refurbishment plan. We can't expect much free cash flow here for now. But if it helps to restore strong performance, it will certainly have been worth it.
Joules (LON:JOUL)
Share price: 216.5p (-2%)
No. shares: 87.5m
Market cap: £189m
Following the pre-close trading update in December, I warmed to this share, thinking that it could grow into its (then, 195p) share price.
The company is making that argument easier now:
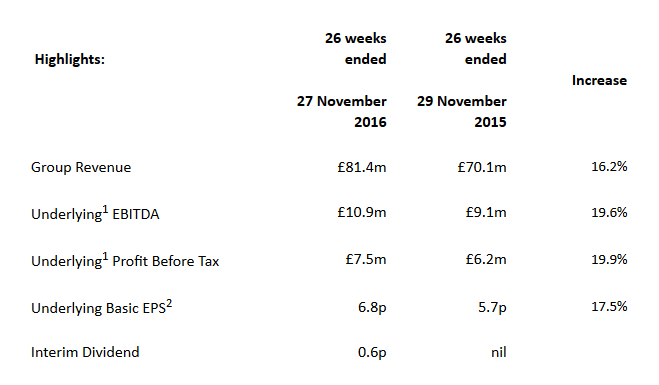
When I ran the numbers on last year's financials, I thought that a fair estimate of the full-year result was about £7.1 million in PBT.
Those results were riddled with "non-underlying" costs, and today's report again insists on making some adjustments.
They are fairly simple, though: just £0.3 million in IPO expenses and £0.3 million in share-based payments.
I feel strongly that share-based payments must be included in underlying results (just as if they were a part of ordinary salaries).
The IPO is a legitimate non-recurring event, however. So I think a fair adjusted result here is £7.2 million in PBT.
Not bad for a half-year result. And the maiden dividend is a strong signal.
My opinion: There are good reasons for confidence: active customer numbers are up by 30%, Christmas period sales are up 23% year-on-year, and retail e-commerce sales are up 30% too (now a quarter of all sales, including wholesale).
Even the gross margin improved by 1ppt, to 55.5%.
My only concern is that capex seems rather high for this period, at £7.2 million, which the company attributes to a variety of factors including new store openings (11 new UK stores were opened). Perhaps that's reasonable, but I'd want to keep an eye on it.
Overall, whereas before I said that the share price was overcooked, it looks increasingly reasonable to me now.
Quarto Inc (LON:QRT)
Share price: 295p (-7%)
No. shares: 19.7m
Market cap: £58m
The market is less than impressed with this trading update (a profit warning). To put things in context, the shares are still up by more than 30% since Jan 2016 - at this stage, it's just a bump in the road.
What happened:
With a continued decline in performance in Books and Gifts Direct (BGD), the Board has reaffirmed that BGD is not a core business and negotiations with a potential acquiring group are ongoing. Heads of Terms have been signed and the deal is anticipated to close in the coming weeks. The proposed total consideration of A$5.75m comprises A$1.0m of cash consideration payable on completion, with a further A$4.75m in interest-bearing loan notes which are repayable out of cash generated by the business, but with a long-stop date of 10 years. Assuming the transaction completes and the loan notes are repaid in full, this will result in a total writedown of approximately $11.0m.
Quarto is still not a company I feel fluent in, so I decided to check their website to better understand the company structure. This helps, sort of:
(I tried pasting a picture in here, but it didn't work - follow this link to see where BGD fits into the company structure.)
Books & Gifts Direct is Australia and New Zealand's largest direct seller of books and gifts. We sell our products from lunchrooms and reception desks in more than 55,000 workplaces around Australia and New Zealand - workplaces that include schools, child care centers, office buildings and community centers.
A quirky type of bookseller, then. Perhaps it makes sense to get rid of it and focus on the core publishing business,
It sounds like a horrible deal, though, based on the information given: just A$1 million in cash, with the rest of the money to be paid out of BGD earnings. It sounds a lot like just giving away any future earnings in excess of A$5.75 million or further than 10 years out. I wonder how such a deal can make sense? Maybe if the alternative was a costly bankruptcy or restructuring process? I'm not sure.
Another note for concern is the stubborn net debt position at $62.2 million, or about £50 million. BGD performance and working capital movements are blamed - that's reasonable in principle, but investors will need to watch carefully to see that it reverses.
The company went on a small acquisition spree in 2016, when it might have paid down debt instead. It also announces today that it's planning to increase its dividend.
It has a highly diversified catalogue, so maybe it can afford to take on this financial risk.
My opinion: This needs more research on my part, but I can see that there have been some huge operating cash flow results over the past few years. (Navigate to the Stockopedia cash flow page to have a look.)
Free cash flow generation looks pretty good, too.
Overall, I don't feel like I've managed to make sense of this company just yet. The best I can say is that I'm open to the idea of it being a good investment at this price!
Alumasc (LON:ALU)
Share price: 175p (+0.3%)
No. shares: 36.1m
Market cap: £63m
This company is new to me. Thanks for bringing it to my attention in the comments.
It says it has a "strategic focus on premium building products, systems and solutions for niche markets"..
The results today look good:
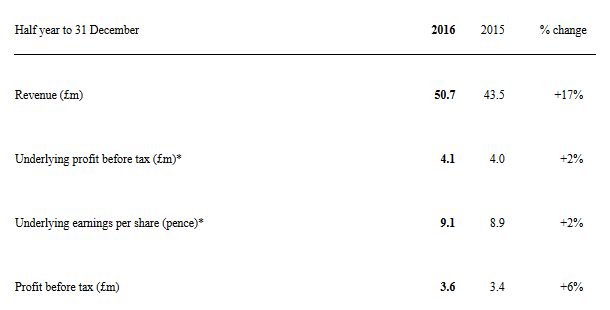
In the "key points", I find it a little odd that there is mention of this being "the fifth consecutive first half year of earnings growth". I suppose it's a good thing at least!
One might think that revenue growth of 17% would have translated to a better profit result, but:
Lower group margins reflect increased imported materials costs and continued investment to support growth.
Benefits of pricing actions and operational gearing will see margins stronger in H2.
Order book: now at £27.6 million, which is said to be at "close to record levels".
Annual revenues have been around £90 million in recent years, however, so this is just a few months of the work which would be hoped for - visibility must not typically be very strong here.
Outlook: "the Board's expectations for full year performance remain unchanged."
Brokers are forecasting EBIT of about £9 million for the full year, putting this stock in the "value category" (in current market conditions) with a PE ratio of about 9x.
I'd be interested to find out quantitatively how much the FX effect has hurt the result, as it seems to have been the only negative.
This is particularly encouraging
Sales to domestic markets grew by 9% to £43.2 million. This compares with UK construction market growth of around 1% in the period, providing further evidence of the higher than industry average growth rates generated by Alumasc's specialist systems and solutions, with over two thirds of the group's business now focused on managing the scarce resources of water and energy in the built environment;
Pension: a triennial valuation has been completed (actuarial, not accounting methods).
On this basis of valuation, the pension deficit was calculated to be £33.0 million and is to be recovered over a period of ten years, with Alumasc making annual cash contributions of £3.2 million (previously £3.0 million), to include scheme running costs. This outcome is in line with the expectations set out in our 2016 Annual Report.
That's quite a large chunk of earnings due to the pension over 10 years. Though it's far from terminal. I'd be happy to treat this the same as I would a £33 million bond outstanding, repayable in installments.
My opinion: I'm quite impressed at first glance. There is good financial evidence of a competitive advantage - excellent return statistics (ROE, ROCE) and industry-beating growth.
Valuation rests on the strength of that advantage. It will take some time for the company to work through its pension deficit, but if there if there is an advantage then I could potentially see this turning out very well for shareholders in 3-5 years.
SCS (LON:SCS)
Share price: 170.5p (+0.3%)
No. shares: 40m
Market cap: £68m
A short update for the H1 period ending 28 January.
Trading has been in line with expectations:
The Group achieved like-for-like order intake growth of 2.7% for the 26 weeks ended 28 January 2017, a pleasing performance against particularly strong comparatives. Two year like-for-like order intake has grown 12.5%. Trading over the Christmas and January sales period was also in line with the Board's expectations.
As flagged by Paul previously, management appear less than entirely confident about beating last year's excellent results:
We remain mindful that the Group still faces the key Easter and May bank holiday trading periods and faces very strong comparatives during the remainder of the year. The Board believes the business remains in a strong position to maximise opportunities as they arise and to grow market share.
Last year saw operating profit jump to £11.0 million (from £2.8 million in FY 2015), and brokers are looking for a slightly improved result to £11.3 million this year.
So there's potential value to be had, including a huge dividend yield (about 9%).
My opinion: I'm reminded of the adage which says that (ideally) you shouldn't buy a stock, unless you'd be happy to be left holding it even if the stock market was shut down.
So personally, I wouldn't try to buy this with a view to selling it before the next consumer recession or hike in interest rates. I would only buy it if I wanted to own it indefinitely.
Gross margins look acceptable to me but what's killing the operating margin is the expenses line, which I understand to be related to the advertising spend. It needs to get a grip on expenses to deliver a comfortable margin.
That said, I can see the potential value here, and would probably continue to hold it if I owned it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
No I'm not interested in the ozone layer,my thinking is not that deep! All I know about climate change is that we don't get any of the heat other countries get in the uk, it's still bloody cold from November till March, then rain in March @ winds in April,that's your I'm only going to do 6 months in UK & 6 months in Cape Town from now on?
Graham,
Not sure if you are aware (I don't think it has been mentioned yet) Paul interviewed the CEO of Quarto last year:
http://qualitysmallcaps.co.uk/ceo-or-fd-interviews/quarto-inc-qrt-ceofd-interview-9-aug-2016/
It is an enjoyable listen.
For all you Boohoo.Com (LON:BOO) fans out there - http://www.thefashionlaw.com/home/bankrupt-nasty-gal-files-suit-claims-vendor-is-threatening-20m-deal
Graham, thanks for your informative articles. While we look forward to hearing your opinion on SCS (LON:SCS) I hope you don't mind if I just point out that you have put the wrong share price, number of shares and market cap for the company in the header of the soon-to-be article.
Thanks dgold, I have a bad habit of missing that sometimes. Fixed now.
On Joules (LON:JOUL), the reviews on TrustPilot have a consistent theme of declining product quality and poor customer service:
https://www.trustpilot.com/review/www.joules.com
When you buy new IPOs, you have to take care as a common tactic of the private owner is to sacrifice quality and service in the 6-12 months before IPO, to aggressively grow top line growth (via marketing), increasing margins, and bumper profits, thus getting the maximum valuation when it IPOs. However, customers who are once bitten are twice shy.... and the impact of declining quality and service on brand loyalty only makes itself apparent 12-24 months after IPO.
By which time the original private owners have cashed out already, and so have management.
sorry all - just worked out how to do this United Carpets (LON:UCG) busines
RE CPR Carpetright... I wonder how this good news will impact on other likeminded companies e.g. UCG United Carpets Group a small outfit market cap of £8.45m
United Carpets (LON:UCG)
Hi Graham, any thought on EYE if you should find the time. Thanks!
I'm on holiday in cape town until May, enjoying the good weather, not interested in anything other than getting a decent tan
I'm on holiday in cape town until May, enjoying the good weather, not interested in anything other than getting a decent tan
What? Not even interested in the hole in the Ozone layer and the damaging effects of UVB radiation?
Si
I would go easy with the tanning bit. Trump's paranoia knows no bounds.
In reply to 26 - and 22
Thank you Fishcake, Yes, a good response from BooHoo which, it would seem, was largely ignored by the Dispatches programme.
I am not a holder of BooHoo (past or present)
Generally I don't have a high opinion of Dispatches reports. They often seem quite thin on content.
Whilst I am sure whistleblowing is an important source of stories, it can also be a cover for revenge or self righteoousness. No context was given to the whistleblower, other than he was changing job and had decided to call in an undercover TV report.
An important subject in this day and age is the responsibilities of online companies, but it left a question mark quite how this story had been shaped.
in reply to posting 22:-
Laughton, thank you for the lead to the BooHoo response.
I couldn't make contact - is the lead correctly stated?
Certainly the market has ignored what appeared to be a very biased report.
Michael
Try http://www.boohooplc.com/boohoo-social-responsibility/statements.aspx
That reads very well to me - though I didn't see Dispatches.
I'm afraid I don't take much comfort from this press release.
Many employer codes of conduct etc etc READ very well BUT the REALITY is never like the stated objectives. Very often employees will not speak out for fear of losing their job or not being promoted.
The bit about ''We have announced a £5m spend on new facilities for 2017, designed to improve the working environment of our employees. This will include a 24 hour subsidised restaurant as well as gym and leisure facilities'' is particulary galling... I guess that's for use by management who would have the TIME and ENERGY to make use...
Not quite naked slave labour as presumably they use some of the companies clothes to dress up a poor stae of affairs.
Ok, I've decided not to bother with OCDO and to do QRT ALU and SCS (would have done QRT anyway).
Many thanks
G
Alumasc and Pressure Technologies please
I have tried to work out the SCS LFL position over time dating back to the start of last financial year - it is possible to derive it based on the LFL figures they release at each point in time and this is what I believe it shows:
25 weeks to 16th Jan 2016: 8.80%
1 week 16th Jan 2016 to 23rd Jan 2016: 16.60%
19 weeks 23rd Jan 2016 to 4th June 2016: 22.13%
8 weeks 4th June 2016 to 30th July 2016: 15.93%
9 weeks 30th July to 1st Oct 2016: 4.50%
7 weeks 1st Oct 2016 to 19th Nov 2016: 5.64%
10 weeks 19th Nov 2016 to 28th Jan 2017: (0.98%)
Crude excel spreadsheet done in a rush at the minute so there may be errors but it looks to me as though the latest LFL figures have gone negative and I'd be concerned that may continue longer term.
I say that because it is also approaching some very impressive LFL growth at the start of 2016.
That's not to say the stock isn't cheap - clearly the low P/E and high dividend are value indicators but I'm not sure these latest figures will see it re-rate.
Hi Graham,
Apologies I clicked "thumbs down" to the article by mistake. Justo wanted to let you know I enjoy your reviews a lot.
Cheers
Thanks for letting me know, Fabrizzio!
And if you didn't enjoy it, I'd be happy to read criticism.
Regards
Graham
I too am interested in Graham's opinion of SCS (LON:SCS). This trading update contained just one relevant figure of "like-for-like order intake growth of 2.7%". Oh and they "traded in line with the Board's expectations". Whatever they are. More figures with guidance are needed. Not gnomic proclamations like "We remain mindful that the Group still faces the key Easter and May bank holiday trading periods". So they will still be flogging stuff throughout April and May then - good to know that.
Last years Trading Update - you can find it on the Investigate website - was similarly figure free, but stated "the Group expects to report profits significantly ahead of current market expectations for the year 2015/2016". So last year they use "market expectations" but this year just "Board expectations". Uh-oh.
Why should we be treated to such pointless banalities when trying to make decisions of whether to buy, hold or sell? They must have some real figures already, unless all the cash is just stuffed down the backs of their own sofas and every six months they turn them all upside down and then cash up.
This year's RNS was very similar template to last year so I hope they tell their PR to re-cash last year's cheque...
Cheers
Glen
+1 for Alumasc
White Paper re reducing cash prizes in Betting Shops. Will this effect stock market prices?
Skelray
Re Quarto
Q3 on 3rd November: "We have entered the last quarter confident that we will meet management expectations for the full year, reducing debt and delivering growth for a fourth successive year."
Q4 today: "Net debt on 31 December 2016 was $62.2m (2015: $59.5m). The increase was a result of both poor trading within BGD as well as negative working capital timing movements in the final quarter, which we expect will reverse in the first quarter."
Things changing quite so quickly between 3/11 and 31/12 I find very worrying; at best the visibility is much shorter than suggested, at worst the management doesn't know what is going on; sell before the placing/rights issue ...
(Why do I think they're going to need to go to shareholders? simply this: "We continue to invest in content with a portfolio of creative businesses underpinned by a scalable platform for organic and acquisitive growth.")
Re Quarto Inc (LON:QRT) Sold this morning and my notes below....
CEO delivering mixed messages which I don't like. Cheap PE for a reason. Agreed to sell BGD for £11M writedown. Debt increased somewhat. Not good. Ian
Alumasc (LON:ALU) and if possible at some point in the future, an outsider, SafeCharge International (LON:SCH).
Would be most grateful for your insight. Much appreciate your daily reports and many thanks,!
Ruth
SCS - some interesting points from investors on social media this morning - debate as to whether dividend sustainable; observation of very thin margins; superficially cheap; and most pertinently perhaps that LFL appears to have declined in past 10 weeks despite the headline +ve 2.7% figure. So a nice one to get stuck into!
Would be interesting to hear your's and Paul's thoughts on last night's Dispatches which featured Boohoo. Thanks!
Re Boohoo.Com (LON:BOO) - I wasn't going to say anything to browndogwork's request but as it's alrady got two thumbs up there are obviously others on here following BooHoo.
In case you haven't already seen it, excellent rebuttal issued today by the company to the Dispatches program.
http://www.boohooplc.com/~/media/Files/B/Boohoo/do...
Share price seems to confirm shareholders general response.
I don't think the TV people did themselves any favours by not accepting company's offer to film and interview staff openly at wharehouse.
Now waiting on result of NG auction.
Yes another vote for Alumasc (LON:ALU) please.
One more vote for SCS (LON:SCS)
I'd like your views on GNC. Announced this morning a trading update. Not sure if this one fits your parameters?
Would like some comments about Porvair (PVR). Announced very solid full year results yesterday, with positive trading continuing into the new financial year.
Could you add Carclo and ScS to the list?
Would appreciate your view on Quarto (QRT) Graham - has fallen today after Trading Update
Quarto Inc (LON:QRT) total assets have fallen from $226.6m in 2011 to 212.8m. Goodwill has remained the same but other intangibles have risen from $1m to $61m in these 5 years. So tangible assets have fallen by about $74m in five years. Is there a reasonable explanation for this substantial fall in tangible assets?
Revenue has hardly grown, so if cash has been invested in growing titles and other intagibles as an investment in the future, it hasn't been working.
Hi Graham
I'd cast a vote to cover Alumasc (LON:ALU)
The market is lukewarm about today's results. Currency headwinds for most divisions, but good growth plus currency benefit from an American division, talk of more capital expenditure, a bit of a hike in the dividend, and debt + pension liabilities in the wings. I've a small holding, but the strength of the balance sheet has deteriorated a bit since I've held. I'd appreciate your views if you should have time & it appeals to you.
Thanks.
(Edit: I notice others also posted, sorry to repeat, I should have refreshed the screen before posting!)
Thanks for the suggestions, I will try to include them
ALU and SCS if you can Graham. Thanks
Alumasc (LON:ALU) please, it issued its half year results this morning. Revenue up, it sounds like they have good sales momentum - stated to be higher than the industry average, but margins down, due to increased materials costs. They have increased cash, are on a low price multiple, and have decent exposure to North America.
I am a (recent) holder.
Thanks
Chris
Hi Graham
How about Joules?