Small Cap Value Report (31 Mar 2016) - SOM, SDY

Good afternoon,
Am running a bit late today, so I'll update this report throughout the afternoon, so please refresh this page later.
Somero Enterprises Inc (LON:SOM)
(at the time of writing, I hold a long position in this share)
Another day, another transcript. I was burning the midnight oil last night editing a transcript from my interview with the CEO & CFO of SOM back in Jan 2016. Reading back through the transcript, there's loads of useful info in there about the company - here it is.
They gave smashing, direct answers to my questions too - I get the feeling this is a very open management team, with nothing to hide.
There's been a bit of Director buying announced today (40k shares at 151p in total) from the CFO, and a NED. The chart looks poised to attempt a breakout, so it could get quite interesting. I like those points as confirmation, but it's the fundamentals that matter most to me, obviously. Note that SOM has a StockRank of 99, so all our ducks are lined up in a row!
The CEO sold £3.8m of stock, in 2 tranches, in 2014 and 2016, but given that he's already past retirement age, that looks to me like an orderly winding down of his position, in advance of retirement, which is fine.
As always, remember that SOM is highly cyclical, so when the next big US recession looms, we need to run for the hills without delay.
Spaceandpeople (LON:SAL)
(at the time of writing, I hold a long position in this share)
I thought the CEO & CFO here came across well in yesterday's webinar organised by ED. Management sounded upbeat about their various new projects. So I hope to see some out-performance here against cautiously-set forecasts.
The CEO has agreed to let me interview him on Monday morning, so as usual I am soliciting questions from you, here is the usual form to submit your (concise please!) question for me to ask SAL.
The good thing about doing interviews in this way, is that there's no judgement required on my part in terms of how probing to be. Since the questions actually come from you, I can ask pretty much anything! Although I reserve the right to tone down aggressive or abusive questions, or to not ask flippant or irrelevant questions. Generally though, I ask nearly all of the questions submitted.
Especially noteworthy was my mammoth interview with Trakm8 Holdings (LON:TRAK) where I asked 47 reader questions! The company's responses pretty much blew apart all but one of the bear arguments, contained in an ill-judged shorting attack on the company in Jan 2016.
Shorters are usually correct, but they do sometimes get things completely wrong, when they jump to incorrect conclusions, and whip each other into a lather, seeing things lurking in the shadows that are simply not there. Although usually most shorting attacks are well deserved, this one was not. Anyway, the numbers will do the talking when the next results come out.
So my interviews are certainly not soft interviews, or PR-driven things. The questions come from investors, and are asked by an investor. I don't charge a fee now either, as I think that can (even subconsciously) compromise my independence. It's a bit galling turning away fees, but integrity matters more than money.
Right, on to today's news.
Speedy Hire (LON:SDY)
Share price: 37.75p (down 1.3% today)
No. shares: 523.3m
Market cap: £197.5m
(at the time of writing, I hold a long position in this share)
Trading update - for the year ending today, 31 Mar 2016. Looks reassuring to me;
The Board confirms that the full year adjusted profit before tax is anticipated to be in line with market expectations and net debt broadly in line with the previous year end.
Following a review of the carrying value of intangible assets, the Board has concluded that the value of acquired goodwill held on the Balance Sheet (c.£45m) will be written off as a non-cash Exceptional Item in the full year results.
Writing off goodwill doesn't matter - it's just a book entry, and has no cash impact. The whole method of accounting for acquisitions is ridiculous really. So personally I write off all goodwill for every company I look at, as a matter of course.
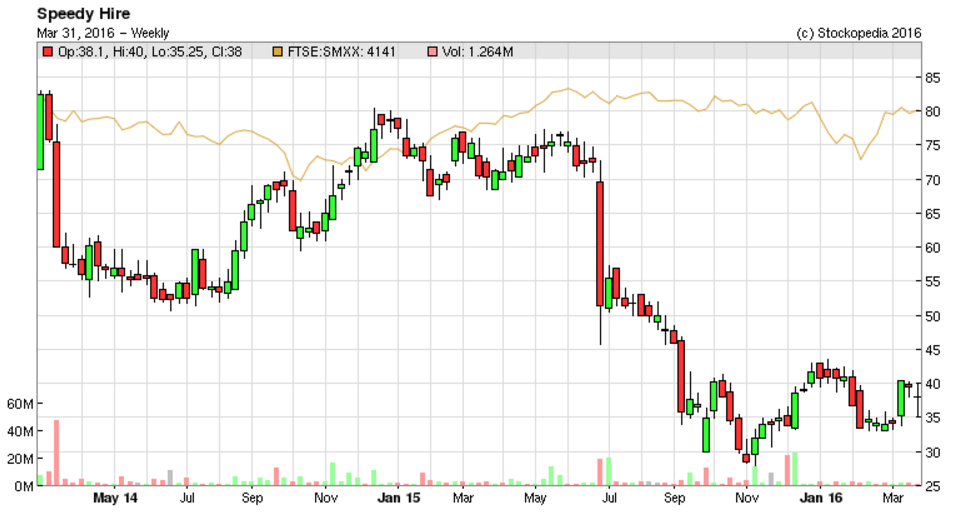
My opinion - this is a turnaround situation, as management seem to have botched up the basics of running the company in 2015.
The good news is that it has a solid balance sheet, so there are no solvency issues. I think it's just a matter of waiting for performance to improve, then the shares should recover. They've seemingly bottomed out over the last 6 months, so I am hopeful of better things to come, providing they don't manage to screw things up again.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
I've heard some 'celebs' have had their social media accounts taken out of their control by their management team due to inappropriate responses in the heat of the moment. :-D
Cheese
Phil
Paul. It was a joke and not meant to insult you. You referred to it in your report
"The good thing about doing interviews in this way, is that there's no judgement required on my part in terms of how probing to be. Since the questions actually come from you, I can ask pretty much anything! Although I reserve the right to tone down aggressive or abusive questions, or to not ask flippant or irrelevant questions. Generally though, I ask nearly all of the questions submitted."
paul - I have defended you on numerous times on here and on advfn. It was not meant as a dig and I was just joking. Perhaps it was hard to tell but a reply like that at 4.16am is unjustified.
Re. Lavendon (LON:LVD) , worth reviewing the commentary and follow up discussion thread on Paul's SCVR from 25 Feb. Some good stuff there on the whys and wherefores of the Lavendon SP.
http://www.stockopedia.com/content/small-cap-value-report-25-feb-2016-soli-tide-lvd-mlin-cwr-idox-122297/
Paul, your interview technique is a bit like Jeremy Corbin's at PMQs i.e. "this question has come from such and such.." ! Nice strategy - i'll try and come up with some probing questions after watching the Equity Development webcast and having a couple of beers.
Cheers.
Ben
Ben,
That's really insulting. Do it urself if u think u can do better.
#### right off quite frankly.
Getting pretty sick of this.
P.
Hi Paul -
A piece of advice from my past experience (over 40 years) in senior management positions. Always give yourself a 24-hr embargo on any sensitive or contentious external communication. This simple discipline saved me from a huge number of own goals, embarrassing situations, size 15 shoe in my mouth, etc. It is simple and very effective.
Paul, you seem to be buying quite a few IPOs after they have issued a profit warning, like Lakehouse (LON:LAKE), Entu (UK) (LON:ENTU), Speedy Hire (LON:SDY) is this a new strategy? Second mouse shares.
Thanks for the latesdt and previous transcripts. Have been happy to make a contribution today.
Paul, I prefer to read the transcripts of your interviews so why don't you charge a fee that covers the cost of producing them? That gives us a better service and saves you the hassle of finding funding for them, and as there's no net financial benefit to you it would take a very picky person to allege any impropriety. You could possibly even get the transcript provider to invoice the company direct so the money never flows through your books.
Paul,
Recognise your point on goodwill, and I normally adjust for its treatment. But writing off the whole amount (ie saying the money that created it was wasted) does perhaps suggest that something is or was very wrong somewhere. IMHO
There is potentially useful read across from Speedy Hire (LON:SDY) for Lavendon (LON:LVD) - the latter still trades on a low 132p on a current P/E of around 7 and a yield of over 4%.
There is potentially useful read across from Speedy Hire (LON:SDY) for Lavendon (LON:LVD) - the latter still trades on a low 132p on a current P/E of around 7 and a yield of over 4%.
I hold a fair few Lavendon (LON:LVD) and believe the main reason for the apparent anomaly in valuation are worries about the Middle East business. I have been kicking the tyres quite hard to try and get to the bottom of the recent under performance and to assure myself it is not a value trap. I cannot convince myself of the latter and so have not bought any more. Some businesses are just permanently cheap, particularly small caps, and need some kind of outer for the share price to rise.
The problem seems to be concerns overthe ME business which although it accounts for only ~20% of revenue, has much higher margins (>30%) than the UK and European businesses which translates to ~40% of profit. So if the ME market deteriorates, profits take a disproportionate hit. Add to this, the unknown possible effects of Brexit on the European business and you can make a reasonable case for the discount being applied by the market. I couldn't find any other reason, so if anyone has any ideas, please feel free to share them.
All the best, Si
yes Lavendon share price seems to be tracking the oil price,
On brexit , if britain leaves , there is no doubt , that borrowing cost will increase.
all ready looking at downsizing my holdings in companies that have signficant borrowings
It's a bit galling turning away fees, but integrity matters more than money.
Hi Paul,
I've never met you in person but have known your writing and ideas on TMF and now Stockopedia for about 16 years. If there's one thing that's never been in doubt in my mind it is your integrity. I might question some of the shares you choose to trade, I definitely question your favoured choice of beer (Peroni, really?) and maybe your love of late night Cheese :-) parties, but never your integrity! Personally speaking, I wish you would take any fees offered.
As for burning the midnight oil editing transcripts.... blimey, we are not worthy.
All the best, Si
Nothing beats integrity .i would like to echo these comments.
Regards,
martin