Small Cap Value Report (4 Dec 2014) - AMO, SEE, PRV, TPO, BVM

Good morning! I've been up since 4am, getting all the previous reports for this week up-to-date and complete, so here are the links;
Monday's report - new sections added this morning on accesso Technology (LON:ACSO) and Bonmarche Holdings (LON:BON)
Tuesday's report - completely new this morning
Wednesday's report - unchanged from yesterday
So, now that we're up-to-date, let's have another cup of tea and crack on with today's (Thursday's) report!
Amino Technologies (LON:AMO)
Share price: 121.5p
No. shares: 53.7m
Market Cap: 65.2m
Trading update - this reads very well. The company says that turnover for the year ended 30 Nov 2014 is in line with expectations, but that profit is ahead of expectations.
Cash conversion has been strong, with net cash having risen to £20.8m (or 40p per share), despite £3.3m of divis & share buybacks. So a third of the market cap is net cash - a very comfortable buffer.
My opinion - I've never quite known how to assess the company's prospects, as set top boxes is not really a market I understand. However, there seems a more positive change in tone in today's update, which sounds much more upbeat about new products, and the sales pipeline. Therefore I'm surprised the market has only marked up the shares by 4.5p at the time of writing - I'd say there's scope for them to rise further perhaps? Although they have had a good run already since dipping to 80p in Oct 2014.
Seeing Machines (LON:SEE)
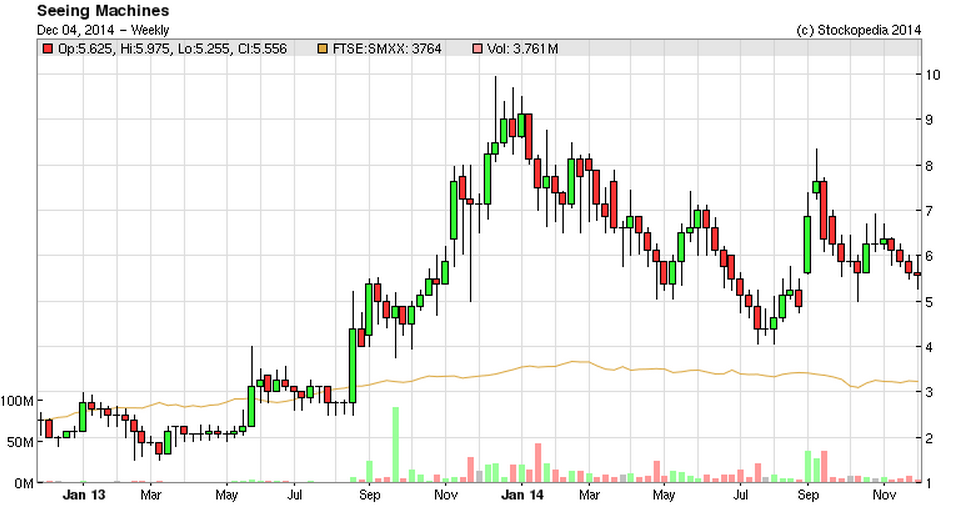
Share price: 5.62p
No. shares: 827.6m
Market Cap: £46.5m
Placing & Open Offer - It's very surprising that this Australian technology company has come back to the market for more cash, so soon after raising more than it apparently needed just under a year ago.
Today's announcement explains why - it reads very positively, with "more than 10" automotive OEMs interested in potentially developing products using Seeing Machines eye and face tracking equipment to detect & alert when driver fatigue occurs.
There's no doubt that widespread adoption of this technology will be a wonderful thing, saving many lives on the roads. The technology is already proven in the mining trucks sector, and is now likely to find its way into trucks, coaches, and cars. Insurance companies might play a part in accelerating its adoption.
So an exciting company & opportunity. However in the meantime, the company is cash burning, so the shares are clearly quite speculative still at this stage.
It seems to be 103m Placing shares at 5.5p, and another 18.2m Open Offer shares also at 5.5p. The discount to the market price is minimal, and the Placing was over-subscribed. This represents an enlargement of the share capital by about 14.6%, which looks fine to me. That can be done without an EGM, as there is existing authority to allot up to 15% of additional shares.
My opinion - although this fundraising has raised many eyebrows, I think on balance it's the right thing to do. This company is the world leader in this technology, so they have an opportunity to really go for it, and that is the right thing to do. History is littered with companies that had a great technology, and a lead over the competition, but squandered the opportunity through being too cautious. So personally, for what it's worth, I am supportive of Seeing Machines' strategy to grasp the opportunity they have.
It's almost impossible to value the company at this stage. Given the size of the opportunity globally, I don't see the market cap as being excessive at this level.
Porvair (LON:PRV)
I commented here on Monday that the valuation was looking stretched, particularly in view of some one-off big contracts ending. However, on a more positive note, the company has today announced a big new contract win >$10m in China. Sounds encouraging.
The Peoples Operator (TPO)
This is an IPO announced today. I've had a look at it, and it looks quite bizarre to me. The valuation is £100m at 130p per share, yet the company is little more than a start-up. The concept is to build a mobile phone company where a proportion of the bill goes to charity. Nice idea. The plan is to build it through viral marketing online, to reduce costs.
I think the reason it has got away at such a bonkers valuation is because one of the founders is Jimmy Wales of Wikipedia fame. Let's hope this company doesn't need to start emailing its customers for regular donations to keep going!
It will be interesting to see if the public take up the concept, but I suspect the marketing budget is likely to be insufficient to gain significant customer numbers. Why pay £100m up-front for an unproven idea? That looks a crazy valuation to me.
Redhall (LON:RHL)
A series of announcements this morning suggest that the company might just survive after all - the bank, HSBC, has backed its recovery plan with renewed facilities.
That said, the Balance Sheet is still shot to bits, and there are more exceptional costs, so it's totally uninvestable as far as I'm concerned.
It is astonishing how lenient the banks are being towards Listed companies in this cycle.
Belgravium Technologies (LON:BVM)
Oh dear, it's a profit warning from this micro cap electronics company.
A contract delay has slipped into 2015. The announcement is here.
I gave up on this company a while back, because it's too illiquid to get rid of even a small number of shares when you want to sell. Also, I think the company is too small to be Listed, and profits are too lumpy & unpredictable.
Somebody needs to come along and bundle together a lot of these tiny companies, into one, more liquid group, and strip out all the separate listing costs & unnecessary Non-Execs, etc, then give each company autonomy in running itself. That would make a lot more sense than having hundreds of tiny companies with separate, completely illiquid markets.
On that bombshell I shall sign off for the day. See you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in SEE, and no short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Not sure about Amino, they have recently won contracts in Turkey, USA and Netherlands so there seems to be demand overseas for their boxes. Shares have gone up about 50% recently.
I don't understand how TPO can obtain competitive advantage. How could they stop a competitor launching a charging tariff that gave a percentage to charity?
Cig- Amino's Market place is where the STB is also the point of broadband delivery enabling IPTV cloud and added value services and content. Sure you can use other apps but when the intelligence is available at IPTV STB level and the bundle price is superior - an area of leverage that operators need to maintain - then the demand for enhanced STBs will be driven. Agree that OTT STBs are last century but IPTV STBs are this century, which is why Amino is driving up sales. Agree that you can get smart TVs but for operators to enable smart services they need to do so regardless of the type or age of the TV set and this is where the demand is for smart IPTV STBs.
Re Amino. One of the factors in the set top box market is the need by operators to offer enhanced services . There's been speculation recently about mobile companies acquiring content companies as part of the drive to offer bundled services the so called quadplay of mobile, broadband, TV and fixed line and the triple play version of mobile, broadband and TV. Convergence of services requires smarter set-top boxes. It also requires add-on features that can drive operator revenues. Amino's newer generation of set-top boxes that can bundle in smart home monitoring for a monthly fee open up a new market and a new cross-sell opportunity for operators. This is area where Amino is competitive.
For TV over IP you can get Google Chromecast or Amazon Fire TV, or the Apple one, and/or TVs with built-in browsers/android. The smart bit is in the cloud. Hard to see how third party solutions can compete with that. The whole set top box model is based on the idea there's one master family TV "set" in the home, which is so last century.
Patent or no patent SEE still need to make the sales happen, and having top sliced this year twice already, awaiting some good orders, they have not materialised enough yet. The potential is there for the product but it does not seem to be happening at the moment. Compared with a year ago it is now hugely overvalued according to Vector Vest. From about July to November last year things looked extremely good but at the present it appears to be a waiting game.
If they can get the sales going like FLOW boilers have done, ( they have a patent) ,then things would have some action happening.
Re. SEE. Seeing Machines. Does anyone know if their technology is patented and therefore presents a high barrier of entry, once their product sales reach critical mass?
Patents are a mixed blessing. They have some patents, but for every one they have, they probably potentially infringe ten or more patents belonging to other people. A search for "eye tracking" in Google's patent search has more than 60000 hits... While not all of this will be relevant, there's doomed to be some. And what they're doing probably touches other areas of computer vision and software that is subject to many patents. You can't move a finger in software without touching hundreds of patents.
They can use their own portfolio as defensive against big boys like Google or IBM ("don't sue me, I won't sue you"), though there's still a risk some patent troll will sue them if they become successful (though they could mitigate that by selling themselves to a big boy with good anti-troll measures). If a competitor their size appeared their chance of enforcement may be pretty low (e.g. competitor may have their own patents, or be too expensive to sue).
Moreover if their strength was in some patent they could be argued to have the wrong product: they should license the idea or a software kernel, not a complete black box product. I think good execution of a finished product is a better USP than patents here.
Hi cig - yes, I agree execution is probably a better economic moat in this case... and maybe first mover advantage?