Small Cap Value Report (4 Dec 2015) - ESCH, IMO, BRY

Good morning!
It really feels as if we're dodging bullets left, right, and centre at the moment. Not only are many/most small caps expensive, but there seem to be lots of profit warnings happening too. This certainly makes me nervous, and more prone to cut positions where I don't have strong conviction, and a positive recent trading update - or solid reasons to expect positive trading.
Certainly the market is being brutal with anything where there is any hint of trouble, so it's not a time to be holding things that are based on hope over substance in my view.
Although in most cases, profit warnings don't actually come out of the blue. Usually common sense can allow you to steer clear of problem companies, and problem sectors. The previous trading update can often contain clues to a forthcoming profit warning (e.g. we expect an H2 weighted year, or we expect to close large contracts by the year end, etc), and often broker forecasts have been trimmed in advance of the profit warning, as the company gave a steer to analysts as it becomes increasingly clear they are likely to miss forecasts. So it pays to look for these signs, and act on them, before the proverbial hits the fan.
Escher Group (LON:ESCH)
Share price: 155p (down 29.5% today)
No. shares: 18.7m
Market cap: £29.0m
Profit warning - the key sections say;
Escher Group Holdings plc (AIM: ESCH, "Escher" or "the Group"), a world leading provider of outsourced, point of service software for use in the worldwide postal, retail and financial industries, announces that the Group will not now close additional license sales that it had expected in H2.
As a result, Group revenues are now expected to be approximately $22m for the year to 31 December 2015 compared to $21m in 2014 on a reported basis. On a constant currency basis, revenues are expected to be approximately $23m (2014: $21m). License revenue, which is high margin, will be materially lower than expectations.
As a result the shortfall in license revenues will feed through to the adjusted EBITDA*. However, Escher still expects to report adjusted EBITDA growth in excess of 80% from $2.1m in 2014.
Following on from my introductory comments above, you can usually see problems coming. Indeed, I warned readers here on 14 Sep 2015 that there were numerous issues with the interim accounts - a flawed business model, which is overly reliant on unpredictable licence revenues, excessive debtors, too much debt, a complete absence of any dividends in recent years, the list goes on & on. So really, anyone holding this stock was just choosing to ignore many problems, and hence got caught out with a not entirely unexpected profit warning.
EBITDA - a totally meaningless figure for software companies. As an example, in this case the company refers above to $2.1m EBITDA in 2014, but it capitalised $2.2m into intangible assets (thus by-passing EBITDA). So in real world terms, which is how these companies tend to measure performance internally, i.e. cash profits, it actually made a slight loss in 2014.
The last sentence in the quote above has left me flummoxed. How come they are saying that EBITDA for 2015 will be 80% UP on last year? Looking back at the last interims, adjusted EBITDA was up 66%, so it looks as if H2 will be up about 100%, in order to arrive at +80% for the year as a whole.
My opinion - this looks like a disappointment, rather than a disaster. So if you like the company, then there's an opportunity to buy the shares at a 30% discount today. That's not an offer which particularly appeals to me, as I've always had reservations about this company's business model.
Additional detail given in today's update suggests that the company is feeling the pain from trying to move to a SaaS model, where licence fees have to be foregone in the short term, in order to secure longer term recurring revenues.
On the upside, I feel that this company must have strategic value to an acquirer, due to its customer relationships, with many of the world's largest postal operations. Maybe a larger software group might pounce for it, with a takeover bid, given that the shares are currently weak? Although are postal services a growth area, given email substitution?
I wouldn't completely rule out a smallish, speculative punt on this share, but it's not a sleep at night investment. The danger from jumping in after a profit warning, is that an Institution (or several) might have already decided to wash their hands with it, and hence could be drip-feeding stock into the market for months to come. So it usually pays to hang back, and wait for the share price to stop falling, and build a base over several weeks or months.
IMImobile (LON:IMO)
Share price: 150.75p (down 3.4% today)
No. shares: 59.4m
Market cap: £89.5m
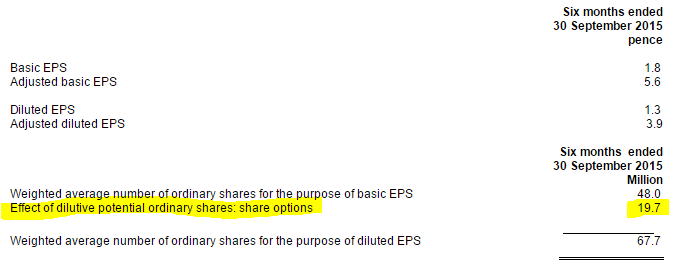
Share options - many thanks to the reader(s) who added comments after yesterday's articles, pointing out the apparently very high level of potential dilution from share options at this company. It's been worrying me, so thought it good to return to this issue and investigate.
As our eagle-eyed readers spotted, the disclosure in note 5 to yesterday's interim results, showed a huge potential dilution from share options. Share options are commonplace, but a conservative level of potential dilution is under 5%, and certainly 10% is seen by most investors as the absolute limit of what can be tolerated.
As you can see from the figures below, the share options at this company appear to have the potential to dilute existing holders by an astonishing 41%:
My next port of call, is to get more detail on the potential dilution, from the last Annual Report, which is on the company's website.
Note 23 of the Annual Report concerns me. It details a second class of share, B shares, of which there are only two shares issued, but it seems to be saying that holders have the right to convert them into 11.3m ordinary shares. Checking the RNS of 23 Sep 2015 about share options, it seems that the 59.4m figure which Stockopedia has for number of shares in issue already includes the potential dilution from this 11.3m of new shares. I think this is related to Indian subsidiaries, and the peculiar rules which restrict foreign ownership, so this might be a work around related to that, possibly?
Turning to note 24 in the accounts, there are a number of share option schemes mentioned;
Plan A - nil outstanding
Plan B - nil outstanding
Flowering - 3m shares (exercise price £0.03)
2014 Unapproved - 6.37m shares (exercise price £0.33)
CSOP - 994k shares (exercise price £1.24)
Rollover scheme - 820k shares (exercise price £0.30)
Total - 11.18m share options
Adding together the 11.18m options, and the 11.3m B share figure, gets to about 22.5m potential dilution shares, which is in the same sort of ballpark as the 19.7m share dilution figure mentioned in the extract from the interim results above.
My opinion - I don't know what to make of this, other than it very much puts me off buying any shares in the company. Or at least I would want to work out my valuation using the fully diluted number of shares, and only consider a purchase if the valuation looked reasonable on that larger diluted shares figure.
I have asked the company's advisers to comment on this issue, as it would be interesting to understand the rationale for the B share dilution, and the seemingly excessive level of share options for employees/Directors. I'll publish any response from the company or its advisers here in future.
Brady (LON:BRY)
Share price: 45p (up 1.1% today)
No. shares: 83.0m
Market cap: £37.4m
Forthcoming interview - regular readers might recall that I was pretty scathing here about the profit warning which halved the value of this software company's shares on Monday this week.
The company's advisers have been in touch, and requested that the company be given the right to reply, and that they would like to do an audio interview with me, so that they can answer the questions raised in my report on Monday, and answer any further questions that readers & investors may wish to put to them, and put their side of the story.
I sometimes charge for my interviews, but as this is likely to be a tricky one, I feel it's essential that I am seen to be completely independent, so on this occasion I will not be charging the company any fees. So it should be a very interesting interview.
To submit questions, please don't reply to this thread, but please use this form, as it will collate all the questions in one place for me, so I don't have to rummage around on various bulletin boards to pick up all the questions.
Should be interesting!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Hi Paul
Just to wish you and yours the very best.
B
Vislink's main incentive scheme doesn't look too bad from where the price is now: you can buy at the current price, put a limit sell at the price where the incentive kicks in (69p or so). If the business works out, you're guaranteed to more than double your money before management makes a penny on the incentive scheme (and if lots of people did that, they wouldn't make anything as there would be a sell wall on the payoff price). And you get some additional upside potential in case a shareholder revolt successfully changes management.
(Not holding myself, but it's becoming tempting.)
Fair enough Paul. It's your IP so yours to do as you wish with it.
Notwithstanding, I found your comments in response to Novice Investor in the link I pointed out above interesting, especially the reference to the charisma of the CEO Mahmud Kamani. In a previous life, I was lucky enough to be involved in the financing of Philip Green's acquisition of BHS from Storehouse in the late 19990's and subsequent aborted bid for M&S. Quite a "Marmite" individual, but an incredible grasp for detail and vision as to how to be successful. I swear he knew the cost of production, retail price and sale clearing price of every single piece of merchandise in his stores. I think the rag trade success stories depend on such individuals and I like to identify and follow good entrepreneurial management that live and breath their businesses.
I'm with you on your high hopes for Boo. With two teenage daughters I get a good inside track on what's good and sometimes not so good in the Boo customer space - maybe Boo could offer shareholders and their progeny a discount code or two a la M&S?
Anyway, thanks for taking the time to respond. I enjoy and value your regular column, as do many on this site, and look forward to some interesting times ahead.
All the best,
Gus 1065.
I suspoect Escher are wrongly using 'growth' when referring to their adjiusted EBITDA. Certainly if the EBITDA figure was at least 80% of the 2014 figure, this would make sense.
Check out post 8 on Paul's 25 November SCVR. I think he quite rightly got p***d off with some trolls on another website about the B. word. Some good on site feedback here.
Gus.
BOO is my favourite, long term superstock.
I'm not writing a report on it, as trolls just soured things for me, and if it's not enjoyable, then I won't do it.
That's it.
P.
hi cig,
not all in really, as I have a % in each long position, and all my "shorts" only make up 6% of my overall portfolio value in total, so I'm about 80% cash at the moment.
just sat waiting and watching....
regards
Paul,
Have I missed your eagerly awaited write up of the Boohoo visit?
Paul is not doing a write up on Boohoo. He made this clear in a tweet a few weeks ago.:-)
Hi Paul. Just a random enquiry. Have you looked again at Vislink (LON:VLK) since the price fall (almost 50% in a couple of months)? It is now cropping up again on my basic Value screening, though the PER is so low (sub-6) it falls into the same catagory as some rather suspect looking miners that I would not touch with someone else's bargepole. Any coment would be much appreciated. (I hold a few already, and have for some years).
( Escher Group (LON:ESCH) strikes me as a triumph of hope over experience. There are no dividends, so it is not for me. The company is too dependent on a couple of large contracts, and if these cease the company is fins up).
Paul did comment on Vislink (LON:VLK) in November.
Hi beginner
I would put Vislink (LON:VLK) on a bargepole list IMO. You can not trust the management. Additionally a PE of 6 and a yield of 5% looks to good to true, which usually means that it is.
A change in a management may well be the time to look at an investment but it is good to see that shareholders doing what they should when they don't like the actions of the management and selling the stock down rather than protesting at AGM's or writing letters. Just love to see these directors being hoisted by their own petard!!
Hi Beginner,
I think the track record of the guy in charge of Vislink (LON:VLK) is appalling - in my eyes he's a greedy, self-serving financial manipulator. The total opposite of what you want to see - solid, hard-working, hands-on management.
So for me, anything he touches is a total bargepole.
Just a personal opinion. Make up your own mind.
Regards, Paul.
Agreed. Just wish there was an easy way to identity these oafs and any company they are connected with. Vislink is a complete no-no for me, based on comments from Paul and others here concerning their overly-greedy compensation scheme.
Kudos to everyone on the board who identifies these rats. Long may it continue.
Hi Paul,
I think we are on the cusp of a bear market to be honest.
I know many don't subscribe to charts of any sort, but generally, as you have pointed out, anything with a slight wiff of a miss is being hammered, not a sign of optimism going forward.
Maybe it will start (carry on?) after the fed meeting next week, it being used as a "damned if you do, damned if you don't" moment as an excuse to wipe off billions in company valuations to make money(short etc) as upside looks limited possibly?
who knows , time will tell, but I am net short, and only have 3 long holdings, 1 arb play, 1 gold miner(in SA) and one silver miner (in the US), and short 8 positions, all in the US.
time will tell.
regards
Gold and silver miners are likely to inversely correlated (with leverage) with a macro equity rebound so you're almost all-in short effectively, with a highly concentrated portfolio...
It's been an exceptionally good year for me and many of us I suspect. However things have did take a turn for the worse a few weeks back knocking quite a few % points of this years's performance. Possibly just random bad luck but I'm a but reluctant to take any new positions at the moment. I can't find much value.
I'm much more drawn to quality stocks with a proven track record of growth but they all looking pretty fully valued right now with few under a PE(f) of 20. The start of the year was very different.
Hi Paul,
Personally, I avoid software companies these days. The few that I've owned down the years apart from Sage and Microsoft have been poor investments, some of them terrible. I just think the odds of finding a good one, particularly in the small cap area, are not good enough to warrant the risk. I know there are exceptions to the rule but for every good one you name I bet I can name half a dozen software companies that were complete dogs.
Talking of which I got bored with BDI recently and sold into the recent small rise and today they have announced that after nearly 9 months they still have no conclusion to there "strategic review". What on earth have they been doing? Who wants to hold shares in a company that doesn't even know itself where it's future lies? Not me!
Best Regards, Si
Thats interesting about software companies. I have just sold my dotDigital (LON:DOTD) shares, they have done well up nearly 40% in about 6 months. One reason I sold was the very large directors sales recently.
herbie47,
It's just a personal thing, I'm not telling anyone else not to invest in software companies or saying there are not good one's out there - I just can't be bothered to try and find them any more! Also I don't think the SaaS model is good from a business perspective as they are giving up chunky up-front revenue for the future hope of growing recurring revenue and IMHO you need to be careful holding shares in any company going through that transition in business model.
Taking BDI as an example that I'm familiar with, they have always had a high percentage of recurring revenue but the best years were when they had chunky one-off revenues from customer specific installations or benefited from an acquisition kicking in. Recurring revenue, although higher quality has in itself never done the BDI share price any good whatsoever.
All the best, Si
Hi Paul
Thanks for the write up of Escher Group (LON:ESCH), but have you seen the spread on this stock. According to Level 2 its nearly 20%! Why would anyone be buying the stock at the moment?
Best wishes,
Imran.