Small Cap Value Report (4 Jan 2016) - ZYT, BRY, EPWN

Good morning, and Happy New Year!
The FTSE100 Futures market looked healthy last night when I went to bed, so it was rather a surprise to see it heavily down this morning, pre-market opening. That means something bad has happened overseas, and sure enough it has - the Chinese market has lurched down heavily again overnight. So we enter 2016 with a 2% fall on the FTSE100 at the time of writing, mid-rnorning, not a great start!
Having pondered things over the long weekend, I feel that many investors have perhaps become complacent, particularly with highly rated growth stocks. Many growth companies had a superb year in 2015 - rises of 40%+ were quite common. However, the ratings are now, in many cases, very expensive. So if you look at things fresh today, would you buy that stock at the current rating? I wouldn't, in many cases, unless the company is absolutely trading its socks off, and likely to significantly beat market forecasts.
So I can't help feeling that it might be a good time to take some money off the table, in shares that have had a very strong run in 2015. It depends on your attitude towards short term losses though. Most investor/traders are terrified by the idea of say a 20-30% loss. Whereas what I have observed, is that investors who ride out such fluctuations, and hold the right stocks for the long term, win the really big prizes.
So as ever, "when to sell?" remains the most difficult question in investing. There's no simple answer unfortunately, each investment is unique. Personally I just try to weigh up risk:reward in each situation. If the price looks full, with limited upside, then I'll take some (or all) money off the table - you can always buy them back on any dips. However, if it's a high conviction, long-term investment, then I'll just hold permanently, and ride out the short term fluctuations.
Sometimes it works, sometimes it doesn't. My win:loss ratio in 2015 was 60:40, which gave a very good overall result. Although I can't help feeling that with more discipline, and fewer impulsive purchases, I could improve that ratio significantly. That's my aim for 2016 and beyond anyway.
It's fairly easy to create a successful strategy. Actually implementing it in a disciplined & consistent way is the difficult bit. Most of us break our own rules constantly, which is usually a drag on performance.
Audiocasts
I've been busy over the long weekend, with 2 new transcripts of my CEO interviews published (for people who prefer to read, rather than audio), on Zytronic here, and Brady here.
Also, just published is my recorded chat last night with renowned small caps investor David Stredder. He achieved +41% in 2015, on his Top 15 picks, as published by him at the start of the year (so verifiable) - a remarkable achievement, coming after many former years of brilliant investing. If you don't follow David, you really should (Twitter: @Carmensfella) - his track record is astonishingly good. His focus is on finding good management, above all else, combined with a promising business opportunity. So he extensively meets, and talks to management, which combined with his entrepreneurial flair, means he just has a nose for finding overlooked bargains, and then flagging them up to the wider investing community.
I'm hoping to record a lot more audiocasts this year, when time permits. There are 2 new CEO interviews planned for late next week. I only interview companies that I think are good, or at least interesting in some way, or to give a "right to reply" for companies where I've been highly critical in these reports. It's the same with investors - I only interview people who I know have made millions from the market in an ethical way, because I've seen them do it! That way yours & my time is not wasted with promoted rubbish.
Epwin (LON:EPWN)
Share price: 132.7p (up 0.9% today)
No. shares: 136.2m
Market cap: £180.7m
Acquisition & trading update - looking at the trading update first, it says;
The Board announces that despite challenging market conditions in the RMI markets in the second half of the year, the Company's profits for the year ended 31 December 2015 will be in line with market expectations.
Of course, "In line with market expectations" are the magic words. Although "challenging market conditions" makes me worry that performance could deteriorate in future perhaps?
I would prefer it if companies didn't use abbreviations in statements, as readers may not be familiar with the terminology, especially where we have to cover dozens of different sectors, and hundreds of companies. RMI stands for repair, maintenance, and improvement, but I had to Google it to find out what the i stood for.
Epwin floated in Jul 2014, and surprisingly perhaps, hasn't had a profit warning (yet). Its sister company, Entu (UK) (LON:ENTU) has of course bombed out, on the closure of its solar division, and more general worries about the company.
Valuation - given the sector, which should be relatively modestly valued, the figures here look about right to me;
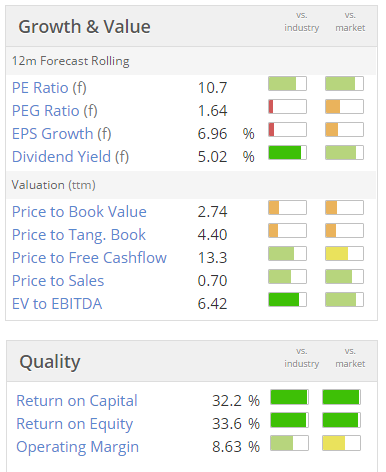
Note the good dividend yield, but there is only a short track record of paying divis, as it's only been listed for 18 months. A big promised yield was (perhaps) used as a way to help get the IPOs away of DX (Group) (LON:DX.) and Entu (UK) (LON:ENTU) , and they have both since flopped, so caution is needed when placing emphasis on a high forecast dividend yield.
Acquisition - Epwin is buying a UK company called StormKing. On the face of it, this looks a sensible deal, priced at 6 times EBITDA, and said to be immediately earnings enhancing. The company makes moulded products for the housebuilding sector, clearly a good place to be right now, due to the pressing need for more affordable housing in the UK.
I like the reason for the sale - the founders are both retiring. That gives comfort that there is no other more worrying reason for the existing owners to cash out. In my view, many acquisitions destroy value for the acquirer - since it's the seller who knows the business best, and if they're prepared to sell, the chances are that the price is a better deal for the seller, rather than the acquirer - who may be chasing EPS growth targets, and over-paying, especially when using cheap debt.
Total initial consideration is £27.0m, of which £20.25m is in cash, the rest in shares. An earn-out of up to £8.0m is potentially payable in Mar 2017. Therefore, it's a fairly decent sized deal, in the context of Epwin's £180.7m market cap.
The cash element has been funded through extended bank facilities, so investors would need to check the balance sheet to ensure that the company is not becoming too highly geared.
The big problem with gearing, is that, especially in an ultra low interest rate environment, companies can drive their earnings growth very strongly using debt to buy up other companies. That's great in the short term, but when the next recession hits, it can leave some such companies in a real pickle - when profits collapse, and often the acquired companies turn out to not be as good as hoped, and the bank starts getting jittery when covenants are in danger of being breached.
The same cycle plays out over & over again, and it's amazing that so few businesses seem to plan ahead for such cyclicality. Optimism seems to trump all in periods of economic growth.
My opinion - I've had a look back to Epwin's last published accounts, and its balance sheet looks fine to me, and is ungeared. So overall I'm happy that funding this acquisition from debt looks fine. It looks a sensible deal, and will increase earnings, so that might well provide a catalyst for the shares to go higher.
The market tends to value shares mainly on a forward earnings multiple, and lots of investors just ignore debt, so there is an opportunity perhaps to make some profit from this?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
Paul, you were discussing 'overstated assets' in your SCVR last week. I've been following the CVS Veterinary Practice Group recently. Their a/cs to 30/06/15 show current net assets at £25.9m, property, plant etc at £20m, long term items at £1.9m, goodwill at £21.9m and intangibles at £57.3m.. So it would seem that more than 60% of their assets are made up of goodwill and intangibles.
Furthermore I note that they have recently acquired The Albavet Group for a consideration totalling £11.3m. Their RNS states that 'further intangibles and goodwill totalling £11.6m are expected to arise on completion.
This high level of goodwill and intangibles probably arises from their many purchases of small veterinary practices but it does end up distorting the balance sheet.
Their recently renegotiated banking facility had a nasty sting in the tail too with covenants requiring:
1). Borrowings to EBITDA must not exceed 3.5 times and
2). EBITDA to interest due must be not less than 4.5 times
it all makes for sleepless nights!
Potential car crash.
Hi Paul
Have just finished listening to the David Stredder podcast. Really good from an expert investor who knows his stuff.
If there is one takeaway for me, it is his rule "management, management, management". I will clearly follow this rule but also the converse one. If I have any doubt about the competence of a company's management, don't waste any time considering it, no matter how well other factors stack up. In the medium to longer term it will come back and bite you.
Paul, just listened to the David Shredder chat could you summarise the problems with Renew Holdings (LON:RNWH) balance sheet and is it getting worse or better. I see their debt has reduced considerably in the last year.
Herbie,
It's all in my previous articles, which you can access by putting in the ticker into the search box, then clicking on the "Discuss" tab. Here's a quick link:
http://www.stockopedia.com/share-prices/renew-holdings-LON:RNWH/discussion/
Regards, Paul.
Ok I did have a quick look before, have now found it: http://www.stockopedia.com/content/small-cap-value-report-20-may-2014-bmy-rnwh-sncl-83506/
Hi Paul, where's the best to follow David Stredder - Twitter?
Hi mikelevie,
You can follow David Stredder on Twitter: @Carmensfella
I'll add this into the article too now.
Regards, Paul.
Hi Paul
Anywhere else to follow David, as I have followed him on Twitter, but he doesn't appear to have posted since October 2015?
Regards
Max
David is also on ADVFN under the name 'davidosh' if that helps.
Cheers, James
Hi Paul, Happy New Year, I've been thinking the same and sold some Norcross (NXR) this morning, I've been holding this share for over two years waiting for a gain, I'm thinking I'll get a better return reinvesting elsewhere but will hold as cash for now.
Good Afternoon Paul, thanks for Epwin (LON:EPWN) update, I'm a holder.
I believe you use InvestEgate, today I had 3 incorrect alerts, not sure if this is just an isolated incidenent or not, I've reported it waiting for their advise. Whats has happened they have mixed up some of the EPICs, so I have EMR on my list and today I get Sports Direct alert, IMO I get Meggitt alert.
Paul, I'm already about 40% in cash with my portfolio now concentrated on UK consumer-facing and consumer-spending-facing or population-growth-facing stocks, apart from two special situations where I bought at a low price and that are now picking up nicely. Tbh, I have nothing where I feel uncomfortable about the PER (because I tend to build in my margin of safety right at the start through "bottom-fishing"), although of course that doesn't mean these stocks would not be affected by a market slump. I see the greatest risk in geopolitics, particularly in Saudi Arabia, where the country is effectively being run by the impetuous, unpredictable and inexperienced Crown Prince, only 30-years-old and who could well be there for half-a-century more, that's if he's not overthrown in some kind of palace coup or through terrorism. Either way, there's bound to be some kind of upheaval in Saudi Arabia and that would give the investing opportunity. Since I look long-term and hold less than 15 stocks, I feel quite comfortable now but would be looking for opportunities in oil and in commodities, should that geopolitical opportunity come about. Otherwise, I shall stay focused on the kind of UK stocks I am now holding.
Why not simply sell stocks you wouldn't buy? Anything else is really anchoring bias (the anchor being a stock's presence in one's portfolio, usually of no relevance whatsoever when it comes to future prospects).
Happy New Year, Paul.