Small Cap Value Report (4 Jul 2016) - TRAK, PLA

Good morning!
The US market is shut today, so that usually means a slower day in the UK.
It's worth noting again the considerable disconnect between the FTSE 100 and small to mid caps. Its high dollar earnings means that the FTSE 100 has been remarkably strong recently - because once translated into sterling, those dollar earnings have of course gone up significantly, due to the recent weakness of sterling, caused by Brexit.
At the time of writing, FTSE 100 is down 0.15% today, whilst the mid caps index is down 1.5%. If you're a small cap investor, and you benchmark (or hedge) yourself against FTSE 100, then you're using the wrong index!
Corporation Tax
There has been a very important announcement from George Osborne, saying that he intends to keep reducing Corporation Tax to below 15% in due course. This is on top of existing reductions of 1% p.a.
This is clearly a positive development, and necessary, since companies need to be persuaded to remain in the UK, and continue inward investment. Having a super-competitive tax regime is likely to achieve that aim.
Obviously it will go down like a lead balloon on the continent, as a beggar-thy-neighbour policy, but there we go.
The annual reduction in corporation tax will of course give us, as investors, a gentle tailwind. Since earnings are after-tax profits, then the lower tax rate will be a gentle boost to earnings each year, for companies with UK earnings. That's helpful in the current circumstances.
Trakm8 Holdings (LON:TRAK)
Share price: 255p (up 8.5% today)
No. shares: 32.3m
Market cap: £82.4m
Results y/e 31 Mar 2016 & contract win - for the avoidance of doubt, I don't currently hold this share, but am mulling whether to buy back in or not. The headline figures today look really good, and have benefited from 2 acquisitions in the year - both of which have been profitable so far.
Adjusted EPS comes out at 13.44p, up an impressive 115% on last year. Although note that this is flattered by a negative tax charge. The rest of the results are self-explanatory, so I won't regurgitate that here.
It probably adds more value if I outline the Q&A session that I had with the Chairman & FD this morning, to answer my particular queries on the results statement. Call me old fashioned, but personally if I have queries about a company's accounts, then I pick up the phone and ask the company for an explanation. I then assess whether or not the explanation makes sense.
1) Debtors of £7.6m looks high relative to turnover of £25.6m. Normally I would expect debtor days to be about 60 days. So (including some VAT in debtors), that suggests to me debtors should be around £6m. Therefore it looks as if there's a an excess of about £1.6m in debtors, above a normal level, which could indicate problems.
The explanation from management is that RM was acquired near the year end, and therefore it contributed little to the P&L, but the full year end debtors are consolidated into the group accounts. Furthermore, RM is a project-based business, so tends to accumulate large debtors, which are then periodically paid in large lumps.
I was one of several commentators who looked up the pre-acquisition accounts of RM, and found them utterly bizarre! TRAK confirmed today that they have revised RM's accounting treatment, to make their revenue recognition much more conservative.
Putting a figure on it, the impact of RM debtors on the group accounts is about £1m, of the £1.6m which is my estimate of the unusually high element of TRAK's debtors.
There was also a £250k impact on debtors from one particular client contract which is payable over an extended time period, as agreed with the customer. I think some of this should probably be moved from current assets into non-current assets - the element which is receivable after 12 months from the year end.
Overall then, these factors are a satisfactory explanation as to why year end debtors is somewhat higher than normal.
2) Development spending - the group capitalised £1.9m of development spending during the year. The amortisation charge for previously capitalised development spending was c.£800k. Therefore you could argue that reported profit is flattered by £1.1m.
Personally I prefer a conservative view of development spending, writing it all off to the P&L as incurred. Therefore I would adjust the profit down by £1.1m when valuing the company.
3) Why is the tax charge negative? The group was able to bring in over £2m in previously unrecognised tax losses, to offset against its tax liability. Also, they benefit from the UK's generous tax regime regarding R&D tax credits.
I asked what a normalised tax charge would be, once the tax losses are used up? FinnCap has worked out the figures, and believes a 5-10% corporation tax rate would be normal in future.
Therefore, in valuing this share, I think investors should adjust EPS to a normalised tax charge. I imagine FinnCap probably do this in their forecasts, but I'll check that.
4) Are they happy with the Route Monkey acquisition? The RM acquisition raised some eyebrows at the time. However, management say it has gone well. RM contributed £596k towards group profit in its first 3 months. I queried this figure, as it seems unexpectedly high.
The explanation is that it does project-based work, so profits and cashflow are lumpy. This was an unusually good quarter. In a full year, RM is expected to contribute c. £3m revenue, and c.£1m profit.
As an aside, the Chairman mentioned that prospective customers always react favourably, when shown RM's products. So if customers like the product, it's probably going to do well.
The first new products incorporating RM's software are due for launch soon.
5) Are there any acquisitions in the pipeline? They didn't want to answer this question directly. They did however point out that there is plenty of headroom on the banking facility, and that it's a very fragmented market. So more acquisitions are possible.
6) Impact of Brexit & forex changes - this is referred to in the results statement. Weaker sterling will cause some cost increases for imported components. However this is partially offset by gains from sales contracts priced in Euros. Management didn't wound worried about this overall - it's likely to only modestly impact on their margins.
Brexit - could cause some customers to delay contracts, but none have so far. The return on investment from TRAK's products is so compelling, that management feel the sales team should be able to overcome any reluctance of customers to sign contracts. Also they pointed out that rising fuel costs further improves the case for telematics products.
7) Any other comments? I always end calls by asking management to mention any key points that we've not covered. In this case, TRAK management flagged up the maiden 2p dividend. Also they flagged the group's good cash generation.
EDIT: Broker note - I've just received the latest FinnCap note, which emphasises the free cashflow of £1.9m, "refuting the recent cash flow criticism" (from Winnifrith).
Finncap's forecast for FY2017 is as follows;
- Revenues £34m
- Adj. PBT £6.4m
- Adj. EPS (fully diluted) 17.0p (based on a 10% tax rate)
- This equates to a new year PER of 15 - hardly excessive.
So if TRAK achieves forecasts for the current year, then the shares will probably be higher this time next year. There's no guarantee they will hit forecasts of course, as with any company.
Balance sheet - there are a lot of intangibles, due to the series of acquisitions made, and also capitalised development spend. However even if you write off all intangibles, the balance sheet still looks OK in my view - in the context of a good stream of recurring revenues.
So no concerns here.
My opinion - I like it. This is a strong growth company, operating in an exciting area, with compelling commercial reasons for customers to buy their products & services. The client list is impressive, and growing. I also like that the company is continuously developing new products - this is a fast-moving space. I also like that customers typically pay on monthly contracts - so there is strong visibility of revenues, and hence earnings.
In terms of valuation, once you adjust for a normalised tax charge, and take a conservative view on expensing development spend, then the price is probably high enough for now, in my opinion.
It's good to see the flimsy bear case against this share collapse in ruins. I don't like it when decent companies are attacked on the most spurious of grounds. Bear raids should be reserved for basket case companies, which this one is very far from being. It's generating genuine cashflow, and organic growth. Basically the bear arguments are just sour grapes, from people who have got it completely wrong. Ignore them! This is a good quality growth company, with capable management. I think the shares are probably priced about right for now.
Plastics Capital (LON:PLA)
Share price: 93p (up 2.2% today)
No. shares: 35.3m
Market cap: £32.8m
Results y/e 31 Mar 2016 - the headline figures look pretty good. Although note that adjusted EPS has remained static at 10.8p, since there has been an increase in the number of shares in issue;
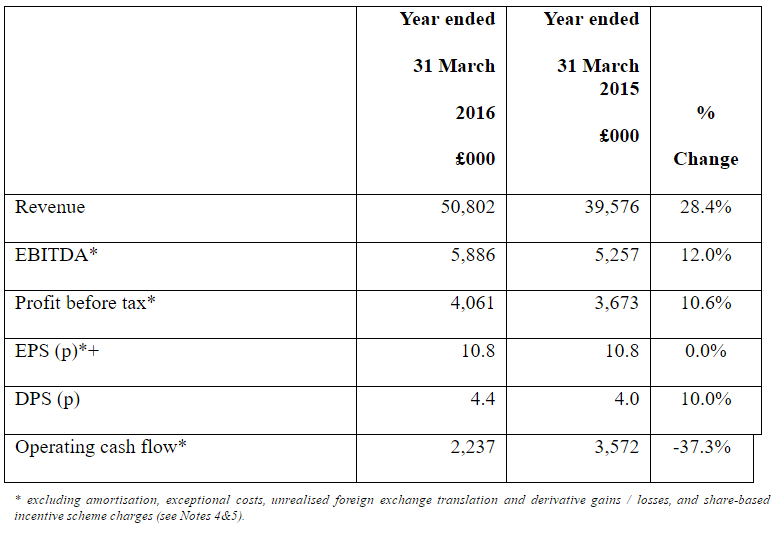
I'm also concerned at a few other issues;
- Negative tax charge on P&L, thus flattering EPS.
- Complicated presentation of results, with lots of adjustments, concerns me (as mentioned before). Adj. EPS is 10.8p. but basic EPS is only 3.5p, a very large difference.
- Finance charges are high, and overall I'm not terribly comfortable with the overall level of gross debt.
- EBITDA is highlighted, but this ignores hefty capex of £2.3m, plus £349k of development spending was capitalised.
Dividends - the yield has risen well, and with 4.4p total divis for the year, that represents a healthy yield of 4.7%. Although I'm not keen on highly indebted companies being generous with the divis. The danger is that they have to do a placing to shore up the balance sheet in future, thus diluting existing holders. Wouldn't it make more sense to retain cash for reinvestment in the business, rather than paying out divis?
Outlook comments sound reassuring;
Trading for FY2017 is currently in line with management's expectations. Trading continues to follow the slowly improving trend we have seen as FY2016 progressed. We remain very focussed on implementing the key initiatives outlined above as this is what will drive the long term growth of the Group, as well as maintaining day-to-day operational excellence to ensure customer retention and cost efficiency. Integration of our recent investment in CCM is also a priority.
However, I can't find any comments specifically about forex movements post the Brexit vote. I feel that all companies need to spell out exactly what overall impact is likely on their future results from the material movements in exchange rates recently. Without this information, it's very difficult to value a share.
My opinion - with apparently quite aggressive accounting, and no guidance on exchange rates, I don't feel able to assess this share properly. So in uncertain markets, I'm not interested in taking the risk.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
On 23 June 2016, Trakm8 Holdings (LON:TRAK) stated "the Company intends to take advantage of the following disclosure exemptions from the requirements of International Financial Reporting Standards (IFRS) in accordance with FRS 101." Some of the things they appear to be exempting seem quite important to me, 10d statement of cash flow, • Paragraph 17 of IAS 24, 'Related party disclosures (key management compensation)
• The requirements of IAS 24, 'Related party disclosures' to disclose related party transactions entered into between two or more members of a group
there are quite a lot more areas covered by the RNS, not being an accountant I wonder why they have done this, and should, as a potential investor, I be concerned ?
I agree , I'm not a holder but if I was I'd be keen to get a response from the company as to their rationale.
Microsoft have announced they will paying Corp Tax in some local jurisdictions, which will include the UK. So perhaps winding back some of its traditional allocation of revenues generated in UK to Eire.
Paul
On a separate tack, your Tweet yesterday evening makes a good point...
"Surely the very poor weather in most of June would have been a big contributory factor in the poor construction figures today?"
Cheers, Martin
Just to flag to readers: over the weekend I researched Kainos (LON:KNOS) which another reader and Paul have flagged recently when it was around 200p. It has been hit following Brexit and is now 136p, I assume because of a combination of shareholders buying on the story and then being annoyed by a large decline in the SP over the last few months and perhaps also because it has a large Polish office - although it looks like less than 10% of its revenue is from the EU so I don't see Brexit having a major impact. Its operating profit has doubled in two years, has a gross margin of 53.4%, cash balance represents 10% of market cap, and yet is currently trading on a P/E of 13 based on results for year ended 31 March 2016. I'm biased in flagging this as I just bought it today but I think it looks very promising at the current share price. DYOR.
A lot of business done by the likes of Microsoft and Apple etc. that are really UK sales currently gets booked in Ireland or Luxembourg to take advantage of their low corporation tax. Presumably when we are out of the EU that business will have to be booked and taxed here, generating more revenue for HMRC.
As to the correct rate of corporation tax, that depends on your views on the Laffer curve and where we sit on it. Simplistically, if you tax something at 100% you will get nothing because people will stop doing it. Similarly a 0% tax raises nothing. Somewhere between is the optimum rate that raises the most revenue. In a competitive environment such as corporation tax for multi-nationals it's very difficult to model what that optimum rate is but a lower tax will definitely attract and retain more companies to pay their taxes here so it's not as simple as saying a lower tax rate automatically means less revenue.
There is nothing that suggests post EU exit Google, Amazon etc will pay more corporation tax in the UK. Corporation tax is not an EU competence. Apple also pays very little tax in the US - it is the set up of national tax systems and the ability of large corporates to game them that led us to where we are with this. not the EU.
Herbie
Look at the tax cut another way, attract companies who employ lots of people who pay lots of tax and NI. Or do nothing and see profits and employment fall thus leading to huge tax revenue reduction and corporate failure. Which would you do, or is it a no brainier ?
Well a 25% tax cut is a lot you will have to attract or not lose a lot of companies to make that up. Will have to wait and see.
Here's the link to Trakm8 Holdings (LON:TRAK) CEO John Watkins discussing FY results, acquisitions and Brexit.
http://www.piworld.co.uk/videos/2016/7/4/trakm8-trak-fy-results-31316
Nice presentation.
Ramridge
My understanding is that you are correct. Ireland had low corporation tax until they needed help in the financial crisis and the anomaly became an issue. The EU in fact suggested unifying corporate tax across all its members, but the UK objected. The UK then complained when other countries undercut them with lower corporate tax - all a bit bizarre, really. A race to the bottom on corporate tax could prove a pyrrhic victory if other countries choose to cut more - but then as others have said, it's all academic: Osborne is unlikely to be around long enough as Chancellor to deliver on this or anything else he says at the moment.
Re. Trakm8 Holdings (LON:TRAK)
I had a good look at the report this morning and I largely agree with your conclusions. A few points of detail.
1. The adjusted diluted eps is 12.38 (Note 7)
2. The segmented analysis (Note 3) shows that the UK represents over 97% of total sales. So nearly all of additional costs of purchasing components due to a weakening sterling will need to be absorbed and will hit margins. Yes export sales might rise but for the near term that is likely to be marginal.
3. On today's sp, PE is near 20. This is on the rich side IMO, given the uncertain times ahead.
(No position)
Many thanks Paul for the great detailed explanation of the Trakm8 Holdings (LON:TRAK) accounts - very helpful.
We filmed John Watkins, CEO with a quick presentation, talking through the results, this morning. I'll post here when the edit's finished.
Tamzin (piworld.co.uk)
Brilliantly detailed breakdown of the results and how to interpret them. Thank you.
But can he cut corporation tax? Until we are out of the EU not sure he can. Also a 25% cut is a lot of lost revenue for the treasury.
Of course he can - its been done throughout the coalition and current parliaments
Or are you asking if he'll be in the job to effect what he says - in which case you're right - he won't be able to cut it
I was referring to that article, yes he probably can. I'm concerned that with 25% tax cuts to large companies how are we going to repay it. Seems a bit excessive to me.
I'm don't know whether cutting companies tax bills is the right course or not, but if we are going to go that route I'd much rather see employers NI cut than corporation tax. Seems to me it has the dual advantage of being naturally focussed at businesses that provide the most UK employment, and also being less blatantly beggar-thy-neighbour than a corporation tax cut.
Herbie - As far as I am aware, there are no EU rules concerning direct taxes, such as corporation tax. The UK government (or any member state) can set whatever corporation tax rate it sees fit.
Could be wrong,
I discussed this with a Chartered Tax Advisor a few days ago. As far as she's aware, EU countries are free to set their corporation tax rates as they wish. Ireland's is (or was, last time I looked) very low, and I believe some EU countries have complained about it.
Paul,
Regarding TRAK I would love to hear your views on the RNS post entitled "Adoption of Financial Reporting Standard (FRS) 101 - Reduced Disclosure Framework". I was very concerned as it sounded like "Things we would prefer our shareholders not to know". Especially concerning was the timing of the RNS feed, 5:17pm on the day of the EU referendum.
If corporate tax is reduced by such a huge margin then this surely means that the tax to IR is a lot less... so presumably they will just have to raise taxes elsewhere to compensate... such as the high-earner thresholds and/or rates, VAT, duty... etc?
Perhaps but it is worth noting that the chancellor has binned balancing the books by 2020. It therefore paves the way for more government borrowing to bridge the gap and/or binning of the pension triple lock rather than increasing taxes which could be detrimental in current environment.
I expect the chancellor will have long resigned by 2020 anyway and/or there will have been a change of government... so it won't be his problem then :-/
Now that is one of the 2 biggest problems with western democracy. The majority of governments lack the responsibility & morality to balance the books.
As that is the case, what we need is a constitutional requirement to run a balanced budget over every rolling 5 year period so and an independent body to call the governments to account. After his appalling performance, Gordon Brown & his fellow MPs should have their pension docked by about 90%. George Osborne should have already earned a cut.