Small Cap Value Report (4 Nov 2016) - BOTB, GATC, HFG, DIA, QRT, SVCA

Good morning!
I'm starting early today, to catch up on the backlog from yesterday.
There's only one trading update (and no results statements at all) in my universe of stocks this morning, a rather pleasing update from BOTB, so let's start with that.
Best of the Best (LON:BOTB)
Share price: 212.5p
No. shares: 10.1m
Market cap: £21.5m
(at the time of writing, I hold a long position in this share)
Trading update - covering H1, the 6 months to 31 Oct 2016. This sounds encouraging;
Best of the Best plc, which runs competitions to win luxury cars online and at retail locations, is pleased to announce that trading for the six months ended 31 October 2016 has been strong with profits before tax generated ahead of management expectations.
Revenues have been in line with management expectations and the proportion of online sales continues to increase.
Operating margins have improved and marketing investment in customer acquisition during the period was slightly lower than originally anticipated.
Ahead of expectations is always good, although it's an important distinction to note that this seems to have been achieved by containing costs, rather than top line out-performance.
Broker expectations have increased this morning. FinnCap has increased its EPS estimate for the current year from 9.1p to 11.3p. With the share price currently at 212.5p (before the market opens - I expect it will rise maybe 10% today, at a guess?) that makes the PER 18.8 times.
Next year's FinnCap forecast has gone up from 10.7p to 12.4p, giving an FY18 PER of 17.1 times. Although FinnCap does indicate that they've been conservative, giving scope for upgrades.
My opinion - this is a long term holding of mine. The reason I bought the shares, is because I see this as a unique business. It's built up a strong reputation from operating at airports for about 15 years. However, business is increasingly moving online. Therefore the PER could shoot up at some point, if the market recognises that there could be much more impressive growth in future from internet sales really taking off.
Imagine what sales could rise to, if a larger gambling company were to acquire BOTB, and put some serious marketing spend behind it? I sometimes wonder if management are being too cautious - they've created something special, but arguably haven't exploited its full potential yet.
Anyway, the advantage of a cautious approach is that it's profitable, very cash generative, and has paid out some smashing divis in recent years.
The game is great fun to play, and I buy tickets nearly every week online.
This share is horribly illiquid, so can be very tricky to trade. So building (or disposing of) a position requires patience, and lots of little trades over a period of time.
Gattaca (LON:GATC)
Share price: 293p
No. shares: 30.9m
Market cap: £90.5m
(at the time of writing, I hold a long position in this share)
Results year-ended 31 July 2016 - this share has been a poor performer this year, slipping backwards from c.500p to under 300p now. Does it represent value at this level? I think it probably does.
Gattaca is the new name for MatchTech and Networkers - brands which are still used, but under the new corporate name. Equity Development ran an excellent webinar yesterday, which I participated in. Management said they had "completely repositioned" the group as a specialist in engineering & technology staffing. About three quarters of revenues come from providing contractors, typically on about a one year contract. The business is also expanding internationally, and they see this rising from about 30% of revenues, to c.50%, over time.
Cost synergies of about £3m have been achieved from combining MatchTech and Networkers, although this has mainly been reinvested in growth.
Profitability - was roughly flat against prior year, on an underlying basis.
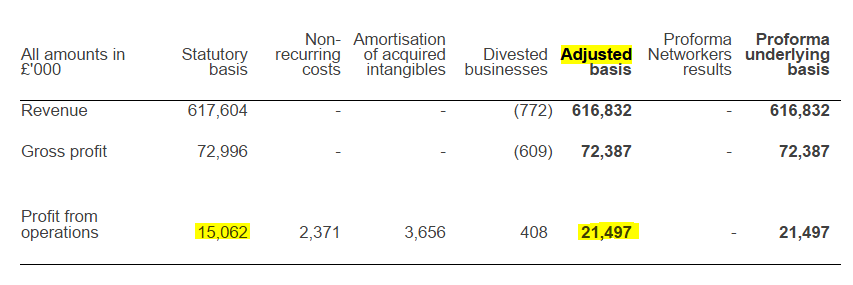
People often say that staffing companies are low margin, but that's because most revenue is "pass through" - i.e. the contractors' salaries. Therefore reported underlying turnover of £616.9m sounds a lot, but Net Fee Income is much lower at £72.4m underlying. This latter figure is what I personally see as the real revenues, excluding pass through salaries.
Underlying operating profit was £21.4m, so actually quite a good profit margin if you compare it with NFI. The prior year comparison number is £21.2m.
In terms of EPS, I think the company has caused some confusion by only highlighting basic EPS, of 31.0p (diluted). Someone asked about this in the webinar yesterday, wondering if the share price fell because the company failed to highlight adjusted EPS, which was 44.3p. That makes quite a big difference to valuation of course - the PER is 9.5 using basic EPS, but drops to only 6.6 if you use the adjusted EPS - a big difference.
Here are the reconciling items to get from statutory, to adjusted profit. I'm happy with these adjustments, so to my mind this stock looks dirt cheap, on a PER of only 6.6 .
Of course, a PER is only cheap if earnings are sustainable. What the stock market is probably doing, is discounting a fall in future profitability. I think this is due to heightened worries about a possible recession in 2017 - not an unreasonable position, since I think the economic outlook is very uncertain at the moment.
Outlook - there are various outlook comments scattered throughout the results narrative. I've collated them below;
Since entering the new financial year we have a seen a slowdown in trading in the UK with Group NFI in 2017 Q1 forecast to be down 3% on 2016 Q1 (Contract down 2%; Permanent down 7%)
We are continuing to Invest in our overseas operations which continue to enjoy growth and which will to some extent mitigate the uncertainty around UK economy in the medium term
Full year effects of Networkers acquisition to come through in FY17, with first concrete sales synergies now being realised
...However, the outcome of the vote continues to make the economic outlook uncertain, yet it is still too early to say what its near-term impact will be for Gattaca. Whilst the amount of business we conduct in Europe is not significant, the same cannot be said for many of our clients and any uncertainty can have a knock-on effect in the investment decisions our clients make.
In the longer term, our strength within the Engineering and Technology sectors transcends international boundaries, and as the trend towards globalisation continues, we are in a good position to respond to any EU exit settlement eventually reached.
The medium term outlook for Gattaca is positive, despite some weakening in demand in the UK. The Board will continue to assess UK trading over the coming months as clearly there is uncertainty over how the EU referendum result will affect UK investment. We are, however, well placed to increase our market share in the UK, while pursing strong international growth through our regional hubs.
The overall tone of the webinar was completely different to the above, I thought. Talking about the business, management sounded far more upbeat than the RNS indicates. So some mixed messages, which probably explains why some shareholders exited yesterday, pushing down the share price.
Obviously the slowdown in Q1, and cautious comments about Brexit, haven't helped sentiment. In the webinar though, management sounded enthusiastic about the potential for improving UK business due to Heathrow expansion, Hinkley Point, and other big infrastructure projects - which will need large numbers of engineers, from the design stage onwards.
Divdends - brokers seemed to be assuming a cut in divis, but the full year divi has actually been increased by 5% to 23p, with management saying this reflects their confidence in the future. Again, that doesn't really tally with the cautious outlook comments above. So I'm confused!
The dividend yield is excellent, at 7.8%. Therefore if you think that's sustainable, this could be an attractive time to buy. The divi cover is quite healthy too, at almost 2 times (using adjusted EPS).
Interestingly, management said on the webinar that they didn't cut the divis in the last recession.
Balance sheet - one of the better ones I've seen, amongst small cap staffing companies.
NAV is £81.6m, then I always delete intangibles, making NTAV £33.2m.
The current ratio is very healthy at 1.84, so a strong working capital position - basically a massive debtor book, partly funded by bank debt.
Note that net debt of £25.0m is down £8.6m on a year earlier, and that Gattaca has tons of headroom within its total £105m of bank facilities - recently extended to Oct 2020.
The £1.1m P&L finance charge is consistent with the reported net debt too.
Note that forex gains boosted profit by £1.0m.
Overall then, I don't have any balance sheet concerns - this is a well-financed company that could weather an economic downturn.
Tax rate - is high, due to overseas operations, and not being able to reclaim some overseas tax. This is a pity, but of course is accounted for within EPS (which is post-tax profits).
My opinion - it's not often you find a sustainable dividend yield that is higher than the PER, but that is the case here. It has a strong balance sheet too.
Therefore I very much like the value characteristics of this share. The trouble is, the market isn't interested in value shares at the moment, it's all about growth. Having said that, I think the valuation here is so compelling, that I'm very likely to increase my existing long position here at some point - probably after the US elections are out of the way, so it's going back onto my buying list.
Intangible assets
A reader sent me a message recently, complaining about my policy of writing off intangible assets. He pointed out that a lot of physical fixed assets don't have much resale value either, so why don't I write off those too?
My thinking is along these lines. Most intangible assets are usually connected with acquisitions - goodwill in one form or another. The trouble with this is that many acquisitions destroy shareholder value, and often the goodwill ends up being written off at a later date. So I take a cautious view of goodwill, and prefer to write it off straight away.
Also, many businesses develop goodwill internally, which never appears on the balance sheet at all. Therefore, acquisitive companies need to have all their goodwill written off, in order to make their accounts comparable with other companies which have grown entirely organically.
Development spending is another problematic area. One can argue that companies are obliged by accounting standards to capitalise development spending. In practice that's not true though - plenty of companies write off everything, and don't have any problems with the auditors.
I've seen so many companies boost their profits by aggressively capitalising development spend, that it can make the accounts so far from commercial reality that they become ridiculous. Examples include YouGov (LON:YOU) - which dramatically over-states its profitability using this method. Also I've long been sceptical of the accounts of Lombard Risk Management (LON:LRM) - due to it capitalising a large chunk of its costs.
This is the method of choice for fraudsters too - Globo used to create fake profit by, amongst other things like falsifying revenues, shoving a lot of costs onto the balance sheet into intangibles.
Investors generally are far too uncritical of company accounts I think. Many market participants don't look at the balance sheet at all, and never question any adjustments to earnings, let alone the underlying accounting policies. This is dangerous, and leaves you wide open to being scammed from inflated profits & hence share prices.
So my approach is to be conservative, and write off the intangibles. That gives me a much clearer picture of a company's underlying financial strength or weakness.
You don't have to agree with me though. That's why I usually give both figures for NAV (including intangible assets) and NTAV (having written off intangibles).
Hilton Food (LON:HFG)
Share price: 596.5p
No. shares: 73.6m
Market cap: £439.0m
Trading update - this is a meat-packing business, which operates internationally. I've not looked at it for 3 years, so please forgive me if this section is brief, and not particularly insightful.
More detail is given, but the key paragraph says it's trading in line with expectations;
In overall terms, the Group continues to trade in line with the Board's expectations.
We have experienced local turnover growth in most of our markets and, as anticipated, we have also continued to benefit from the strength of the various currencies in which the Group trades in relation to sterling.
Balance sheet - I've had a quick look at the last set of accounts. Food producers often seem to gear up, but this company last reported a net cash position. Although it's unusual to see £56.2m in cash, simultaneously with bank borrowings of £34.6m. That seems inefficient, in terms of interest costs.
Overall its balance sheet looks fine to me.
Valuation - this looks priced about right to me - note the very low operating profit margin, but the other quality scores are good - it seems to generate decent profits from not particularly large fixed assets;
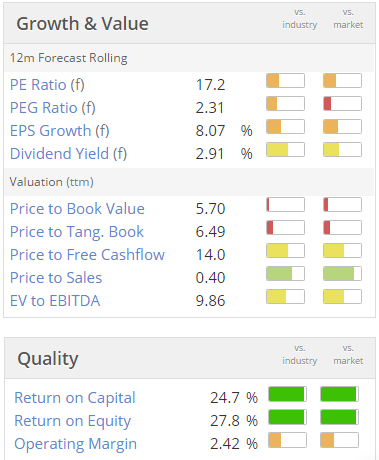
The StockRank of 90 is high.
My opinion - I can't see anything to get excited about here, it doesn't float my boat at all.
Although management talk about further expansion, which could drive profits higher.
Dialight (LON:DIA)
Share price: 665p
No. shares: 32.5m
Market cap: £216.1m
Trading update - in line with expectations, and it sounds like they're benefiting from exchange rate movements;
The Group is targeting a modest constant currency revenue performance, with reported revenue to benefit from a positive FX impact.
The Group's trading performance for the full year remains in line with current market consensus.
My opinion - it's had a great recovery this year. Price looks toppy to me now at 670p/share. That's 33 times this year's forecast earnings, and over 20 times next year's. What happens if something else goes wrong? The company has been accident-prone in the past.
Risk:reward doesn't look good to me, at this level.
H & T (LON:HAT)
Share price: 290p
No. shares: 37.0m
Market cap: £107.3m
Trading update - a missed opportunity here. A friend told me I should buy some when they fell to 240p last month, but I dithered too long & missed it. Also, I don't really want to own shares in a pawnbroker.
A very good update came out yesterday, and the share price is now 290p;
H&T Group plc ("H&T" or "the Group"), is pleased to provide a trading update for the financial year ending on 31 December 2016.
The Board expects full year profit before tax to be above the top end of market expectations.
The principal reason for the strong performance is the higher sterling gold price since the EU referendum result. The increased gold price benefits the Group's Pawnbroking Scrap and Gold Purchasing segments.
The Group's development of its lending activities continues, at 31 October 2016 the pledge book had increased to £40.5m (30 June 2016: £39.0m) and the Personal Loans book to £8.2m (30 June 2016: £6.3m).
I'm told that the personal loans product has good growth potential.
I've just checked their website, and as I feared, the personal loan product is extortionate in cost, and therefore brazenly exploiting the poorest in society. I find that completely unacceptable, and hence wouldn't want to buy this share. Yuck!

Quarto Inc (LON:QRT)
Share price: 281p
No. shares: 20.4m
Market cap: £57.3m
Trading update - sounds alright, with the key bits saying;
On the basis of current levels of trading and order book visibility, the Group remains confident that it will meet management expectations for the full year and deliver both debt reduction and earnings growth.
Marcus E. Leaver, Chief Executive of The Quarto Group, commented:
"We have entered the last quarter confident that we will meet management expectations for the full year, reducing debt and delivering growth for a fourth successive year.
We are pleased with the integration of Harvard Common Press and becker&mayer into our publishing portfolio, both of which are performing to expectations and complement the organic growth we are seeing in the core business.
We have a solid model in place: the right people, high-quality and long-lasting product, efficient processes, a balanced portfolio of imprints and a scalable platform."
Overall - I'm warming to this share, but for my personal taste the debt is still too high. You don't have to agree with me on that though. Indeed, the Stockopedia computers are telling me I'm wrong, as this share has a very high StockRank of 98.
Servoca (LON:SVCA) - a small staffing group. It said yesterday that it's trading in line;
The Board is pleased to announce that it expects to report that its results for that period will be in line with market expectations.
This covers the year ended 30 Sep 2016. No outlook comments were given.
According to the 2.22p EPS forecast shown on Stockopedia, that equates to a PER of 10.2.
I'm struggling to understand why a smaller staffing company should be priced a good bit higher than bigger companies like Staffline (LON:STAF) and Gattaca (LON:GATC) (both of which I hold long positions in).
All done for today, and the week!
I'm off into the City now for lunch & meetings, but will see you back here on Monday.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
.
Daily Mail had a sympathetic write-up on BOTB yesterday
http://www.dailymail.co.uk/money/cars/article-3894318/Do-people-win-supercar-giveaways.html
Comments not so positive, but who takes notice of those anyway?
Taken to extremes, one might argue that share trading is for some akin to gambling/ lottery, but that would be stirring a hornet's nest!
Sorry to have ruffled feathers regarding BOTB. My aversion to such outfits concerns the easily swayed addicts spending much more than they can afford on obviously poor odds. Anyone who can afford to blow £20 a week on it well fair enough, after all it's only £40k over a working lifetime.
Regarding Best Of The Best (LON:BOTB) , Trust Pilot has 75% of customer reviews as 5 out of 5 stars and a score of 9.1 out of 10 so I would assume the large majority of people are playing it because it is fun and good value for money..
I've never really used trust pilot so not sure how much relevance to give it but have started looking at a few companies recently that Paul has covered. £G4M gets similarly good scores with 88% giving it 5 out of 5 stars. Having used both companies recently I can see why they get good reviews. Topps Tiles (LON:TPT) on the other hand, a pretty lousy score of 4.2 out of 10.
Does anyone have any thoughts of using trust pilot / any other review system to gauge if a company is offering a good product / service for consumers?
I'm pleased to see SCS (LON:SCS) has a 9.2 score on trust pilot, I therefore think it is a great source of info on consumer facing businesses ...
I do have a frustration with payday loan companies, so I'm not targeting h and t here as I think their pawn broking side of things is legitimate and fair.
But these extortionate payday loans do target the less fortunate, and most of the time people living beyond their means, and it creates a vicious circle of debt that has never been earnt. Someone somewhere is going to be paying for this debt, until one day the house of cards comes tumbling down again.
This is almost the same situation as the events leading up-to 2008 yet just on a smaller scale.
Thanks for flagging Gattaca (LON:GATC) Paul, looks interesting. One thing that puts me off slightly is that the CEO barely owns any of the company. According to morningstar he only owns 92,722 shares which seems like a ridiculously small holding. Although he has bought in 2013 and 2015 around the 500p mark. It'll be interesting to see if he boosts his holding. FYI Ric Piper, of Lakehouse (LON:LAKE) fame, is on the board of Gattaca (LON:GATC).
Where I grew up, an impoverished ex coal mining village, we had doorstep lenders (Greenwood?) whose rates were even higher , the usual pattern of events is that some people would permanently rollover small balances, and occasionally one of those would hit the limit and go to the unofficial lender of last resort. He was a scary guy who eventually ended up in jail for murder. In that light a regulated player like H&T isn't a bad option and the key thing to remember is that customers in this space are generally a nightmare to deal with as can be seen from the net margin H&T generate.
I once knew very well someone who reportedly made millions out of being a fixer on defence equipment supply contracts. Yet this person always took a stand against the supposed immorality of gambling.
Concepts and constructs of morality and immorality vary greatly, often depending on personal interest.
" whatever people say, and how they try to argue that blue is yellow, it just feels wrong to me." - I sort of know this is just a gut feeling you have, Paul. No worries.
For anyone who doesn't have the same gut feeling, they can rest assured that H&T offers very competitive products in its niche and is one of the more responsible lenders in the marketplace.
It's not for me to push my moral views on anyone else.
However, if I find a company repugnant, then I'll say so. For me, H & T (LON:HAT) is a repugnant company, that is exploiting the poor. So I wouldn't enjoy the divis, I would feel guilty about receiving them. That's why, whatever people say, and how they try to argue that blue is yellow, it just feels wrong to me.
I've been down on my luck before, and had to claim benefits, and lived on the breadline, 3 times actually. So the worst thing people in that situation can get into, is debt. So I feel that facilitators of debt to the poorest in society, at scandalously high interest rates, are absolute scum. I don't know how they sleep at night.
You may take a different view, which is fine.
There is no comparison at all with Best Of The Best (LON:BOTB) - it's a fun competition, which has fair odds that you can work out from the accounts. I play the BOTB game because I enjoy it, and can afford to waste £20 a week on it. It's so exciting to see how near you get, and get booby prizes. Vastly better than picking some random ball numbers - how boring!
Anyway, each to their own!
Regards, Paul.
"So I feel that facilitators of debt to the poorest in society, at scandalously high interest rates, are absolute scum. I don't know how they sleep at night."
But are those rates scandalously high?
They seem to be making a net margin of around 10% which seems very normal and suggests the rates are high because the write-offs are too.
I am very surprised that you feel that the protection of the populace against possibly unfair odds boils down to their ability to access and analyse accounts !
"There is no comparison at all with Best Of The Best (LON:BOTB) - it's a fun competition, which has fair odds that you can work out from the accounts. "
slartybartfast
I am very surprised that you feel that the protection of the populace against possibly unfair odds boils down to their ability to access and analyse accounts !
I'll bet that more people have lost more money on the stock market than on BOTB perhaps because they cannot analyse accounts. I would also argue that BOTB has a lot less manipulation of the odds than those on the stockmarket. Do you want to protect everyone from a little innocent fun?
Thanks very much for the information on Gattaca Paul. It has made a big difference to my perception of the company now that I realise that the net fee income is relatively small compared to the revenues. This means that the profit margins are so much more robust. The company would do well to make this more widely known. I also wonder if the company is deliberately creating low public expectations as a safety first ploy even though, from what you say, some of its comments sound more optimistic. I always prefer companies that underpromise and overperform rather than vice versa. Also alot of recent comments on ethical considerations when investing. My opinion is that the large tobacco companies have probably caused a greater amount of suffering from their products than all the other "unethical" companies put together. However my view is that whether I invest or not will not make any difference to this, so I do invest in companies which I consider cause harm. However, I do oppose them in other ways by lobbying against them whenever possible and I think this has a much greater impact than simply not investing in them. I can think of one company which I have successfully taken legal action against because of the unfair way they treat their customers (including me) but I also hold their shares because one of the reasons their profit margins are so high is because they behave in this manner and, unfortunately, they are likely to continue to get away with it. I could mention their name but this might not be allowed so I won't, but they are pushing the legal boundaries rather than doing anything evil.
The moral arguments of investing or not investing in a company I have noticed come up regularly on these threads. It is something I have had to think about. Im sure their are some invsetors who detach themselves from their investments and see them only as figures and ratios, profit and loss. As a private investor managing your own portfolio I think you are more acutly aware of what your buying into. Should you buy into a drugs company who is testing its latest drug on Orangatangs? re The companies mentioned in this post; I could Ironically see a situation where BOTB customers spend too much of their pay playing and have to go to H&T to cover their bills. Or H&T lending money that is then spent on BOTB!
Good evening Paul. Thanks for your continued hard work with your postings. I have just read your report from yesterday regrding GBG. I am not intending to comment much myself because for one it was yesterdays report and want to keep things more topical. You commented that GBG is not a bargain, which I agree is true; however looking at the fundamentals I believe it is a strong company with strong management. Profits are forecast to increase along with organic growth if not at their previous rate; so I don't see a lot to worry about, just a set back with the share price. Anyway, enough about GBG.
Paul - may I ask you a general question. If I look at a number of trades for companies, doesn't have to be a specific one, on a number of occasions I see many small parcels of shares traded at the same price, either a buy or a sell; perhaps 8, 9 or 10 parcels. The number of shares traded in each parcel are so small that individually they don't make sense. They are usually if not entirely shown as "A" trades. Can you throw some light on what these trades mean please?. Co-incidentally or not they seem to have a disproportionate affect on the share price movement. Should this be a reason to be anxious?, is it a sign of shorting?. I have tried to work it out myself but I can come to no obvious conclusion. I am sure others would be interested in your answer.
Thanks for your attention and regards
CM
To be fair, a personal loan and overdraft are not the same thing. An overdraft more closly resembles a 'payday' loan facillity. Overdraft fees have not all that long in the distant past also come under scrutiny and if I remember righlty some banks gave refunds as the charges were ruled as excessive. I looked at BOTB as Paul had mentioned it and am sort of kicking myself now after the rise. However I hesitated, for the same moral reasons Paul states he would not buy into a payday loan company. So many of the testamonials I read on the net were from customers who loved the competition, but, it was so sad reading how they spent hundreds of dollars a week trying to win.
Yes, I would agree that H&T are a reputable company. Short-term loans to people who couldn't borrow from a bank are always very expensive. That's the way it is. They are much cheaper than a lot of other outfits and have a good business model.
As an H&T shareholder I would remind readers that the company's personal loan product at the quoted APR (450%) is far cheaper than Wonga (1300%) and many other short-term loan providers.
Also worth noting that the cost of a £300 overdraft at Barclays for six months would cost £137 under their current fee structure, which is not much cheaper than the £178 quote from H&T (who accept higher credit risk from their customers). Of course, Barclays might not be considered paragons of virtue either but it seems wrong to single out H&T as offering significantly worse value than others in the financial sector.
Hi Graham,
I challenge your figures on Barclays.
Last week I took out a personal loan with Barclays, to bail out a friend who was stuck in a 16.9% APR loan arrangement (a 2nd mortgage type deal) which he couldn't afford.
Barclays gave me a loan at 4.9% APR. This will reduce the monthly payments from an unaffordable £350/month, to £150/month, as my friend will reimburse me for the monthly payments. OK, I've taken on the credit risk, as an informal intermediary, but it should be OK as it's someone I trust & have known all my adult life.
There were no arrangements fees, or other fees at all, as far as I know - although I didn't actually read the documentation so that might not be 100% accurate. I'm pretty sure it is though, thinking about it - the total repayable was only about 1/8th more than the amount borrowed, and that was over 5 years.
So to see H&T ripping off poor people with those appalling rates, makes me angry. Personally I wouldn't want to receive divis from any company, knowing that some poor person has had to go without food or heating to make the payments.
Regards, Paul.
You're comparing apples and oranges there, Paul. Or maybe apples and bowling balls. A Barclays personal loan is usually several thousands of pounds (typically £7,500 - £15,000) and is repayable over 2-5 years. With that size and maturity, and with the credit rating which Barclays requires, of course they can afford to have a much lower APR. There are fixed costs and therefore there is operational leverage in the lending business (the more you lend and for longer, the lower you can charge).
I referred specifically to the Barclays overdraft, which is the type of small-value product which competes with an H&T personal loan or a payday loan. Many pawnbroking customers have already been turned down by their bank for an overdraft because the bank considers them too high-risk, but companies like H&T are willing to take that risk. Thanks to them, their customers are able to buy food, heating or a few Christmas presents even if they have temporarily run out of cash. And the products would not be profitable if the customers were not able to make the repayments.
I don't regard BOTB as a scam, but like many gambling companies it appears not to provide meaningful value for money to its customers in any sense, except of course the extremely few lucky ones. On the other hand it could be regarded as just another parasitical prey on the less intelligent. Bargepole for me I'm afraid.
Crusty,
I've got to take issue with you here! You said;
I don't regard BOTB as a scam, but like many gambling companies it appears not to provide meaningful value for money to its customers in any sense, except of course the extremely few lucky ones. On the other hand it could be regarded as just another parasitical prey on the less intelligent. Bargepole for me I'm afraid.
I think that's an outrageous comment! People such as myself who enjoy playing the BOTB weekly competition, are not necessarily "less intelligent". I play the game because it's great fun, simple as that. I don't expect to win a car, and indeed I don't need a car, because I already have a rented one, which I rarely use.
If you have £20 spare in your pocket, and fancy a flutter, I'd much rather have a guess at where the head ball is on BOTB, than just picking boring old random numbers on the National Lottery - which has always seemed to me the most boring thing imaginable.
I'd bet on anything - which ant will be the fastest to traverse a piece of A4 paper! Anything, as opposed to magic balls rotating around a carousel.
P.
If you would like to view yesterday's Gattaca (LON:GATC) webinar please go to: https://www.equitydevelopment.co.uk/webinars/?d=%3D%3DwMyIjM
Kind regards,
The Equity Development team
I think it is the case that intangibles should be depreciated over 10 years but goodwill is subject to an impairment review which often results in it not being depreciated at all. If you look at a company such as Accrol you will see that they bought customer lists and goodwill from the previous company. The customer lists are depreciated and the goodwill is not although there does not seem to me to be a lot of difference between the two. The simple issue with many smaller companies is that if goodwill is depreciated it will have a big effect on profits and on the ability to pay dividends. If companies dealt with this honestly then there would be no problem because it is easy to see that with a successful business far from falling in value the goodwill can increase substantially over the years.
Equity Development put out an interesting comparative report on Gattaca (LON:GATC) yesterday.
https://www.equitydevelopment.co.uk/edreader/?d=%3D%3DgMyIjM
Gattaca (LON:GATC) does look good in the longer term, but it is intesting that they are suggesting LFL Net Fee Income will drop in 2017. The price DOES look attractive at the moment, but this suggests it may well get even nicer next year.
The other thing with Dialight (LON:DIA) is that you will almost certainly be paying 33x adjusted earnings as they have guided £13m costs of UK manufacturing closure and haven't provisioned anywhere near that so assuming those cost hit H2 they will be asking you to ignore exceptionals again. Given that they have had exceptional costs every half year since 2013 you could question how exceptional these really are.
You are also paying 33x earnings which have excluded capitalised development expenditure. We don't know what will be capitalised in 16H2 but the trend has been for increasing capitalisation in the recent past so is likely to have an impact.
The trading statement reads like the FX impact has saved them from a miss rather than an incrementally positive development. This combined with the factors above mean that an in line statement is largely worthless until we see the actual figures and can judge how much FX, removing 'exceptional' costs & capitalising development have contributed to them being able to hit market expectations vs actual business performance.
Another point about Intangibles. Current accounting standards don't encourage write-down of intangibles unless there is an impairment of the assets. Way back in time writing down annually a % goodwill (amortising) acquisitions costs used to be established practice. Admittedly it was in the gift of the company and the auditor to assess the write down period, but this meant that goodwill reduced over time through the p&l write down, and the intangibles figure on the balance sheet itself reduced.
Now if there is an impairment you have a potentially big write off taken through the p&l, and this can devastate the p&l loss account surplus, which is needed to allow dividends. So it could be argued at some level that the current practice of accumulating intangibles gives a false view of the profit cover for dividends.
Of course in the old days the system of annually writing down a percentage of goodwill was also abused. The purchase of a company for say £1m could be written off in five years, and the company could be sold in year 6 for £0.5m and trumpeted as a gain (remember now zero cost on the balance sheet) when in reality it was a capital loss in real terms.
The accounting standards bodies currently feel accumulating intangible costs gives a better view of the companies activities. But as with everything over time new potential distortions grow
A very useful article on Gattaca which I hold. I was tempted to buy some more yesterday but did not in the end.
I thought the results were reasonable and the reaction was overdone as so often the case.
Hi Paul,
Thank you for the detailed analysis of Gattaca (LON:GATC), which I also hold and indeed topped-up on yesterday. I am reassured by what you have said about the webinar.
Yesterday's research note from Equity Development may also interest readers with an interest in the company.
http://www.equitydevelopment.co.uk/edreader/?d=%3D%3DgMyIjM
Steve
Hi Paul,
Thanks for your summary on the BOTB update today, I too hold a long position and I am a frequent player of the competition also. I only wish I had the capital behind me to invest back in 2012/13, when this was becoming very popular at my university!
One thing that does concern me, the sentiment from the loyal fanbase of players - I regularly check the facebook comments to get a feeling for this, and see more and more people calling out scam etc. Obviously to you and I, it's a legitimate well run business with a long history. But what are your feeling towards existing customer sentiment and attracting new players who maybe sceptical to play.
Thanks,
Joe
Hi Joe,
I haven't seen any of the comments you mention, but will check it out.
I'm afraid that the internet & social media have given a loud voice to the most demented people.
So I am continuously appalled by the horrendous comments that are widespread on YouTube comments section of newspapers, Facebook, Twitter, etc.
Mind you, we all have our moments, especially after a few shandies! :-/
Regards, Paul.