Small Cap Value Report (5 Feb 2015 ) - PRES, WIN

Good morning! I'm running slightly late broadly in line with previously advised timescales today. Profit warning of the day seems to be from Pressure Technologies (LON:PRES) which we were only discussing yesterday. Let's have a gander (please refresh this page regularly, as I will be updating between noon and 3pm).
Pressure Technologies (LON:PRES)
Share price: 267p (down 29% today)
No. shares: 14.4m
Market Cap: £38.4m
Profit warning - being a group of companies mainly serving the oil & gas sector, this company was obviously going to warn on profit, and it has done today. I think this is probably a buying opportunity, because the price had already factored in the (inevitable) profit warning, so the sharp drop today is double-counting, in my view.
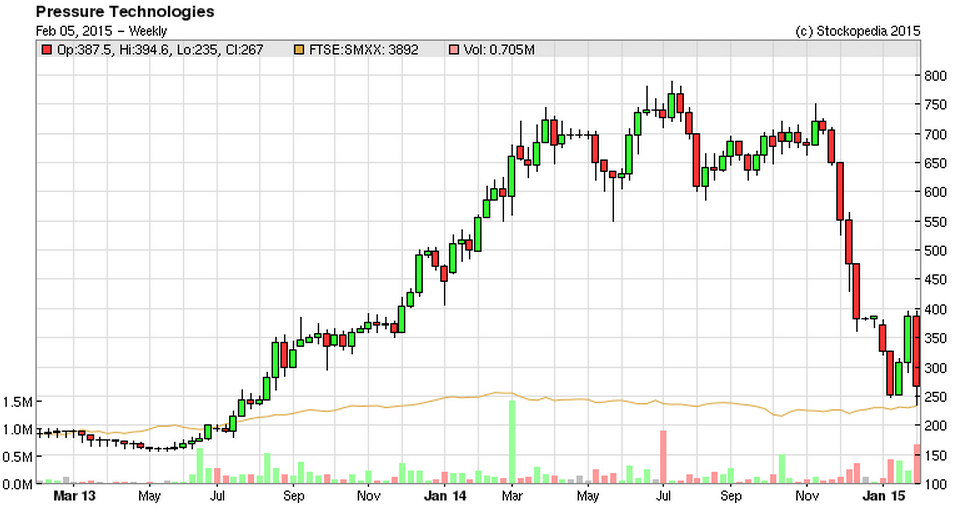
You would have to have been living on a different planet not to realise that oil services companies would have reduced profit this year (and probably next year too). Therefore, as you can see from the two year chart below, the price of PRES had already dropped dramatically, in anticipation of a steep fall in profits in the short term. So it's bizarre to see another steep drop this morning when the company simply confirms the inevitable. Anyone selling today must be seriously myopic to have not seen this coming, which makes it all the more illogical for the price to be down so much today.
Markets are meant to anticipate obvious things like this, and then barely move on the actual news.
Looking at the detail of the profit warning, I think they have handled this badly. The announcement today is far too long-winded, yet contains hardly any specifics. What they should have done is said something like this: due to the collapse in the price of oil, we are likely to have a period of poor trading in 2015, and probably in 2016 too. We anticipate that profit in 2015 will be £x, and that profit in 2016 will be between £y and £z. We will update the market every three months on any changes to this guidance. The company has more than adequate cash resources to weather the downturn in our markets. Business should return to normal when oil prices return to normal.
Instead, today's announcement is long-winded, but light on specifics. The tone is wrong too, sounding almost as if the company is surprised that business is deteriorating, when it should be glaringly obvious to everyone that the whole sector is struggling in the short term.
My opinion - good companies with sound balance sheets will survive and prosper in the long term. That's how I see this company. I suspect that buyers at this level could end up looking smug in a couple of years' time, but should be prepared to look daft in the shorter term!
Wincanton (LON:WIN)
Share price: 166p (down 6% today)
No. shares: 121.7m
Market Cap: £202.0m
Trading update - if you've never heard of a balance sheet, or have no idea what they are for, then this is the share for you! The company says that it continues to trade in line with expectations. It notes some new contract wins, and mentions that the fall in the price of fuel has had no material impact on profits, due to it being a pass-through cost to clients.
My translation of that would be: we remain marooned in a rather smelly creek, and are still looking for a means of propulsion.
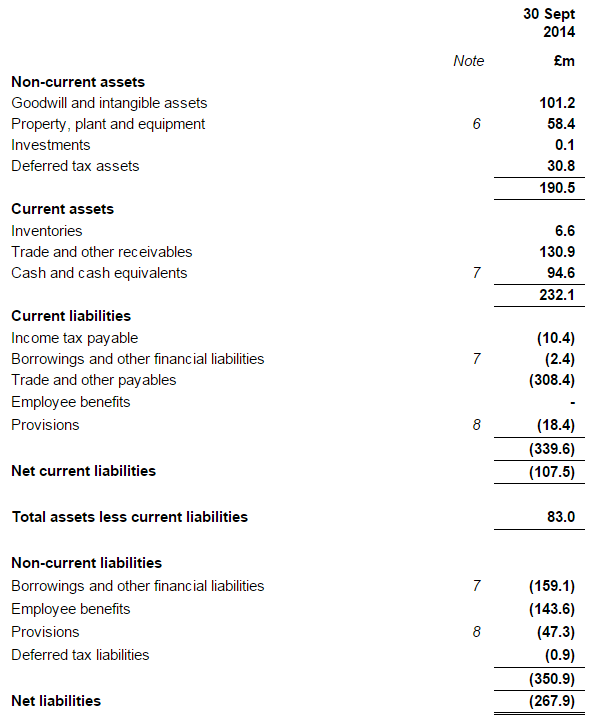
Here is the last reported balance sheet, it's so bad I just have to copy it here in full.
The current ratio is very poor, at 0.68 (I don't normally invest in companies where the current ratio is below 1.2).
There is also a mountain of long-term liabilities, at £350.9m, mainly bank debt, and a large pension deficit.
Overall, instead of having net assets, it has net liabilities of a gigantic £267.9m.
Strip out intangibles, and that worsens to an appalling net liabilities position of £369.1m.
So this is very much a zombie company which can only continue operating because its bank and customers continue to support it with generous cash advances. Dividends stopped in 2011, and it's difficult to imagine the company ever being able to safely resume them.
I cannot understand why anyone in their right mind would buy these shares, when the company is in such a dire financial position.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
Spread Increasing at higher level...It is clear sign market maker dont allow others play around!!!! Only convinced players buying ....
Yes ...Smart operator/market makers yesterday companyies comment and Mr Paul's comment utilized smartly......they acquired more qty at lower rate....I am sure more informed people buying.....problem is most of the people trying to interpret balance sheet....but they cant able to visualize business opportunity and changing environment....... let us watch how things will fold out
Last time also samething happend...Paul comments came when it was 150p then it crashed 120 p after that it never come back that rate !!!!!!!!!!!!!!!!!!!!!!!!!!!
Cheers
Happy Investing
Re. Wincanton (LON:WIN) "Curiouser and curiouser"
From a balance sheet strength viewpoint, this is about as bad as you can get for the reasons stated before by Paul. And the b.s. figures have been bad for some time.
Received wisdom is that companies with weak balance sheets get hammered (or at least badly impacted) at the time of a stock market correction. So I put this to the test.
The last major correction was during the period 4/9/2014 to 15/10/2014 when the FTSE250 dropped just under 10%. How did WIN fare? Well the sp actually went up +1% !
Hmmm. Time to dig deeper to try and understand why.
Regards, Ram
A good rule of thumb is to do the exact opposite of what investors chronicle recommends - I don't have any stats on the performance of their recommendations but the ones I looked at seldom made sense.
Shares Magazine used to be slightly better, but again was more targeted towards the unsophisticated investor.
Far better off reading Paul's daily reports and other postings on stockopedia.
As for Wincanton (LON:WIN), I once worked for their parent company before they were demerged. They had a lot of debt even in those days, and it was always a high turnover low margin business. I don't know what their pension deficit was, but their sister company Unigate, which became Uniq, essentially got swallowed up by the pension fund as the deficit was larger than the value of the company itself.
IMHO Paul is totally correct in looking at levels of indebtedness of companies (on / off balance sheet and pension fund deficits) and placing great importance on this. High debt is manageable when interest rates are low, but when they go up (as they surely must) and / or your market changes in a matter of weeks (just look at £AFR) investors can get a nasty shock...
Paul has been berating me about Wincanton's StockRank for most of the last year due to the quality of its balance sheet. The StockRank has been up in the high 90s for much of that time.
Wincanton's Quality Rank is shaved down dramatically due to its balance sheet issues, but that doesn't stop it from scoring highly for Value and Momentum, and thus highly on our blended QVM system. It also qualifies for two of our Value+Momentum 'Guru' screens.
I wrote a section in a recent article (November) all about Wincanton and how to think about high StockRank stocks - I suggest a re-read. Wincanton has since surged another 16%. It's been probably one of the best performing of the high StockRank stocks over the last 12 months.
I find this fascinating. Wincanton may yet go bust - the balance sheet issues are hardly hidden - but the stock has been a top performer. It's a classic case study in why strategies that focus on Value & Momentum work regardless of Quality. Our own ranking performances show that buying 'cheap, improving' stocks (Value+Momentum) outperforms buying 'cheap, good' stocks (Quality+Value).
There's a John Maynard Keynes saying that "the Market can remain irrational longer than you can remain solvent" - people can be very right on a stock, but very wrong on timing. That's one reason why momentum will always remain a key part of Stockopedia's ranking system. It lowers the risk of short-medium term underperformance.
I'll be blogging further on this next week.
Another approach is to emulate fund managers Nick Train and Terry Smith and buy a portfolio of undervalued high quality companies and holding them forever (or at least for many years), ignoring any profit warnings or share price drops when they occur. This approach seems to have worked very well for them, as their funds have consistently outperformed the FTSE All Share Index.
This is really interesting, looking at the two Stockopedia pages.
Paul blasts Wincanton for it weak balance sheet, but which has positive free cash flow.
Paul backs Pressure Technologies for its strong balance sheet but which has negative free cash flow.
If cash is king, are the Pressure Tech accouts a bit smelly?
@JollyBiologist, I quite agree can't believe some of their tips, most I missed fortunately but some are mad to me, chinese cos, 3 or 4 have seriously crashed. My theory IC ignores debt. I read their FTSE 350 review and I was amazed that only about 10% of the shares were considered sells, about 50% were buys and rest were holds, seemed very odd to me. Is it some promotion to buy shares?
I think the problem with WIN is the large bank debt, yes they are trading well at the moment but if things do go wrong, recession or lose some large contracts then the banks may remove support. Also pension deficit will be soaking up profits?
I have seen quite a few companies get into trouble last year, then I have read Paul's reviews on them and found very often he has been warning about them well before they crashed. Of course no one gets it right all the time.
I think something wrong with analysis (WIN).If balance sheet give clear picture then I am sure CA people will be multimillionaire...I am one of the employee working in P&G at WT .Their WIN have contract..My understanding ..they are doing well....WIN contract continues renewing ...Yes this stock is not good for one who looking for div....................One thing i Know well..Company doing well....I have observing this last 4 years
Why has WIN got a high rating on Stockopedia?
And why is it still rated a Buy in the Investors' Chronicle?!?! I'm currently a subscriber to the IC, but I've not been impressed over the last year, so I won't be renewing. Stockopedia is all I need!
Well I was surprised how much the shares had gone up from 250p after the previous fall. Now they are back down again, if I had seen them first thing I would probably have bought some, I was in before but sold out when they fell.
WIN is also a surprise how the sp has gone up, I did have some, its an IC tip, after reading Pauls reviews I sold out at around 164 a few weeks ago. I do find it surprising that professional share tipsters do not seem to look at balance sheets. So no surprise that IC tips do not perform very well, I will not be renewing my sub. next month.
PRES announced the purchase of its buildings last week.
This gave the shares a fillip as it is a measure of management confidence.
The fall on the rns included this sp increase, so is not as odd (or pehaps as violent) as it first seems.
apad
" Business should return to normal when oil prices return to normal."
Isn't that the tricky bit?
How about if the US$100-150 of the last four years turn out to have been abnormal?
Hi Paul
Surely it was not today's fall that was bizarre but the SP recovery that preceded it? As it is, the SP is only back down where it was after the previous profits warning. Perhaps as expected, PRES have stated, with lots of commentary providing almost no useful information, they have no clue on trading going forward, so it is no surprise the SP took a major hit. The only fairly clear and specific information relates to Kelley GTM which looks to have been a very poor use of funds.
All IMHO DYOR.
Cheers, Martin
I agree Shanklin and found the lack of guidance around financial performance worrying. As a consequence it's difficult to value Pressure Technologies (LON:PRES) so I'll sit on the sidelines, and wait and see what happens.
73% of PRES business is from the oil and gas sector,
much of that in expensive offshore developments.
Imo, there's a fair chance that this company is looking
at trading at a loss, if not FY15, then for FY16. Imo, not
bargepole but definitely a lottery ticket, unless the price
of oil shoots straight back up and pretty quickly.
Hi Jane,
Sure, in a low oil price environment, a company like Pressure Technologies (LON:PRES) which is heavily exposed to the oil & gas sector, will undoubtedly see profits fall considerably. Losses? Possibly, but I don't see any risk to the company's solvency, as it has a very strong balance sheet. The low oil price is self-correcting, it's only a matter of when, not if the oil price goes back up again. Supply contracts and demand increases when the oil price is low, so it will go back up again, we just don't know when!
The only surprise is that anyone is surprised that PRES has reduced profit expectations!
Regards, Paul.
Hi Paul, sorry to hound you when you're running late! Any chance you could take a look at Fusionex (FXI) at some point? Seems like good results to my novice eyes, but sp is down 2.5% today.
Thanks, James
jimbobjames2002,
Paul has a strict rule of not investing in overseas AIM companies so doubt he'll comment on FXI. :-)
The interim results announced this morning look good to me although I think the valuations are warm at current level. Also, despite the 30% increase in revenue, net profits barely changed from last year due to higher costs of growing the business.
However, unlike some of the dodgy Chinese companies out there, I have no doubt that this is a genuine company with real technology and people behind it. The founder, I believe, has not sold any of his shares despite it being offered to be bought off him during IPO.
Also, their client list, probably unknown to you gwailos, are proper local blue chip companies. :-)
(disclosure: I own some shares in FXI)
Gavin
Hi Paul, totally agree with your comments re pricing in the oil price impact already. I was already holding PRES, having bought after the previous drop. I took the opportunity to average down even further this morning once the decline halted. After the rebound, I am near a net break even (after a gouging spread from the MM this morning) on a solid company which has a good track record and is diversifying across other energy markets. I believe it will come right in time.
Cheers, Mark
No Paul, you are not really late, you are 'running broadly in line with your expected schedule'. Get with the Directorspeak! :-)
Steve