Small Cap Value Report (5 Jan 2016) - NXT, John Lewis,

Good morning!
My attention is mainly on retailers at this time of year, given that it's my specialist sector - having been the FD of a ladieswear chain between 1993-2002, which we grew to about 150 shops by the time I left.
So I look at the trading updates at this time of year from large cap retailers, to provide the context with which to judge small cap retailers' trading updates.
Next (LON:NXT)
Trading update - compared with the often imprecise reporting from small caps, it's a real treat for me to look at this update from the UK's stalwart mid-market clothing retailer. The company gives clear guidance on profit throughout the year, adjusting, and narrowing the range as the year progresses. It's just superb, and is typical of the way the company is run overall.
We already know that the UK saw probably the mildest winter weather for several decades, in Nov & Dec. This does genuinely impact clothing retailers, since winter coats, and other products designed for cold weather, just don't sell very well. They then have to be cleared at deep discounts, impacting on margins, as well as reduced sales.
On the other hand, consumers do have more disposable income this year, so it's not all doom & gloom.
Personally I think the slowdown in sales shown in the last two months in the table below looks perfectly reasonable, given how extreme the weather was;
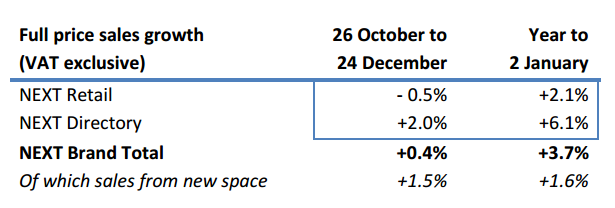
Clearly the market was expecting Next to have somehow worked miracles, as it has marked down the shares by nearly 5% today to 6835p. The shares don't appeal to me, as the business is looking increasingly ex-growth now, so perhaps needs to come down to a slightly lower PER? I'd be tempted to pick up a few at the 6000 level, but not higher than that.
There's a super graph in the Next announcement today, which clearly shows the correlation between mild weather, and reduced winter clothing sales, as you would expect;
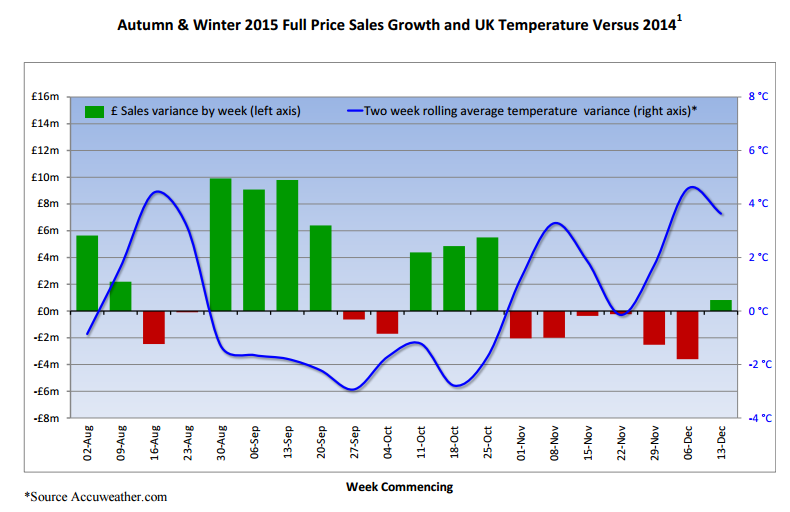
Impressively, Next owns up to some mistakes too, unlike many others, who are likely to use the weather as an all-encompassing excuse for weaker performance;
Whilst warm weather may have been the main reason for a difficult fourth quarter, we would not want to allow difficult trading conditions to mask any mistakes and challenges faced by the business. Specifically, we believe that NEXT Directory’s disappointing sales were compounded by poor stock availability from October onwards. In addition, the online competitive environment is getting tougher as industry-wide service propositions catch up with the NEXT Directory.
Note also the very interesting last sentence, which I've highlighted, re competitive pressures, as online catches up, as they modestly put it!!
Full year guidance - if only all companies reported so thoroughly, promptly, and accurately to shareholders throughout the year;
Full price sales for the year to date are currently +3.7% ahead of last year, just below the bottom end of our previous guidance of +4.0% to +6.0%. However, good control of margins, costs and stock, along with healthy clearance rates means that we expect profits for the full year to remain within our profit guidance of £810m to £845m, issued in October.
Our revised central forecast for full year Group Profit is now £817m, though this might increase or decrease by £7m depending on trade in January. £817m would represent an increase of +4.4% on last year...
Outlook - the company indicates an expected range of +1.0% to +6.0% for sales and profit growth in y/e Jan 2017. A wide range is fine, as that will narrow as the new year progresses.
My opinion - I think Next has performed well, in a very tough Autumn/Winter season. This is now the benchmark for other clothing retailers, and I imagine others will generally have done worse than this, with perhaps a handful of stand-out good performers, probably including SuperGroup (LON:SGP) which seems on a roll at the moment.
John Lewis Partnership
Xmas trading update - Another high quality retailing outfit, but of course not stock market listed, because it's owned by its staff (and doesn't it show, in customer service, and quality generally?).
Updates from John Lewis are however useful for read-across to other retailers.
Performance looks absolutely excellent - LFL sales are up 4.8%, which comes on top of strong figures last year.
Online has been very good, up 19% vs LY, and now 36% of total sales.
Click & collect is proving extremely popular, and is now more popular than home delivery, with 56% of online orders being collected in this way. This is extremely important in my view, as it has obviously good read-across for Argos (Home Retail (LON:HOME) - of which I am long), if UK consumers are now gravitating towards click & collect as their preferred method of receiving goods. Although this might be skewed due to the demographic of John Lewis' customers, being affluent & mobile.
Black Friday is described as a "stand out success", so it looks as if this is here to stay, and has perhaps permanently changed the UK's shopping habits, from the previous gradual surge up to Xmas, to now being a sharper peak at end November (for Black Friday on 28 Nov), then softer sales in December.
Electricals are mentioned as a strong category, up 6.8% YoY. This might also be behind today's spike in the price of HOME.
** BREAKING NEWS! An announcement has just come out that SBRY is interested in buying HOME, I will come back to you on this once I've read it in more detail.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
I was amused to note that Paul made no mention whatsoever about Boohoo.Com (LON:BOO) and how their business model should make them far less affected by the weather.
Interesting view on Next Paul. What drives your view that £60 is your buying level? FYI, I bought some today as I think over the long term they will continue to outperform given the strong management and clearly impressive business model. Also, the buyback programme and history of special dividends gives and extra comfort factor. However, I would be really interested to know what is key in your mind about £60. Feeling quite happy as nearly bought at £75 in recent past, but I'm glad to say I listened to my new rule about patience with names I like and not rushing in.
Click & collect is proving extremely popular, and is now more popular than home delivery, with 56% of online orders being collected in this way. This is extremely important in my view, as it has obviously good read-across for Argos (Home Retail (LON:HOME) - of which I am long), if UK consumers are now gravitating towards click & collect as their preferred method of receiving goods.
Clipper Logistics (LON:CLG) is a way to play this - http://www.clippergroup.co.uk/clipper-announces-new-collaboration-with-john-lewis/ (disclosure I'm long)
Hi Paul, Happy new year. Interesting re John Lewis, I mentioned the click and collect to my wife as a success and she made the point that Waitrose provides a collect point and they are in many towns. I guess she might be right !
Charles
Yes but I think John Lewis now charge unless you spend quite a lot of money, I was going to buy their towels but when I saw the new charge I did not bother, think I will try Dunelm's instead as that is free. Sports Direct also charge £5 but give a £5 store voucher but then store prices are higher.
Yes but I think John Lewis now charge unless you spend quite a lot of money
Yes, there's a £2 charge for click-and-collect orders under £30. There is a sound business reason behind this based on human psychology; they know that for everyone like yourself there will be two or three others who will order something else to make their order up to £30 or more and in the process feel like they've saved £2! i.e. they feel like they've gained but do not see how their behaviour has been influenced.
It's the same with Amazon... I still prefer to own music CD's but Amazon increasing their free delivery limit up to £20 changed my behaviour to downloading MP3's. I know they have used this approach to influence my buying behaviour and increase their margins on the music I purchase in the process.
All the best, Si
There may be a bit of that, but there's also a fixed cost to each parcel being processed and they're not going to recover that cost if too many people order one matchbox at a time and get free shipping.
There may be a bit of that..
Actually there's quite a lot of that, and as the JL numbers have shown, the £2 charge does not seem to have effected the growth in click-and-collect, quite the opposite. If you are not familiar with them, you may find the books of Dan Ariely and Robert Cialdini interesting reads.
All the best, Six
I see. I thought it was more than £2. Problem is nearest Waitrose to me is some distance, looking at the prices it may well be over £30 anyway. It was free until recently. I prefer no charges. I often order online and then collect otherwise it can be a wasted journey and its easier, also online is often cheaper and you can use Quidco for many stores.
As for cds I don't buy many now as you can most streamed, the ones I do buy are usually used ones on Amazon for very low price. Vinyl is now the thing but thats expensive and often less than perfect.
Dammit been watching home for about a month. Don't think Sainsbury are the natural bedfellow for them - and move strikes me more of desperation than anything else as they are being decimated by the likes of Aldi.
My thinking suddenly crystalised on why I wanted to buy Home Retail (LON:HOME). Not for the loan book or anything like that. It's because of their distribution network.
They have a very good high street presence. Imagine a scenario where you have logistic fulfillment companies who do the final stage of the purchase process - i.e. unite the customer with their goods. Argos could do this for any number of product providers, using their infrastructure. Look at the success of click and collect from John Lewis that Paul highlighted above.
I've totally given up on getting things delivered at home - i.e. parcels. They try and deliver when you're at work. Then they put a card thru the letterbox, and try and deliver again tomorrow. Same thing happens. Imagine how much money this costs the couriers. Even Amazon now uses their own delivery 'agents' who try and deliver when you're out - but give you no option to reschedule. Useless.
Now imagine all these goods being sent to a local hub - where you can drive to pick up - or walk. So much easier. I think that's where the strength of Argos is. And they are central, not stuck in some industrial estate out of town.
Incidentally I signed up to a Doddle account. Absolutely brilliant. I live in central London and there is a location on my way home. Highly recommended.
Re: NXT I think its a good performance considering the weather and other retailers, god that they did not bring their sales forward like most other retailers, I think below 7000 is a buying opportunity, yes they are not cheap but then they rarely are, disclosure I do have a long holding.
I also think that it has been a pretty creditable performance by Next (LON:NXT) (I also hold).
Now that the share price has dropped below £69.62 there will be a buyer in the market with a large cash pile to spend. They are also the people who know the business better than anybody else and the rationale for the share purchases are set out very clearly.
All we need now is for the weather to start behaving itself again. :-)
I see Next bought back 586,000 shares today at £68.17, so as you say it may be a long wait to pick them up at £60.
Interesting move by Sainsbury's and I can see the logic. The margins outside food must look more attractive given the rise of the discounters and click and collect is the way to go for anyone who isn't at home for the home deliveries. There is a click and collect point just built in my local Sainsbury's car park - extending that to Argos products would be attractive. That store was recently expanded to take more home wares - using the Argos buying team to do the sourcing would work well given their scale.
I can see basic foods being the loss leader or at least break-even products to bring us in to buy the higher margin food ranges and the general merchandise. Good way to take the battle to Amazon given their plans to move into groceries.
Also as was said, Homebase was Sainsbury's before. It's lost it's way in my view vs B&Q - not sure it has the required scale to compete, but maybe an Argos tie-in could help there also.
I know a few people in the industry who will have been busy this morning making some phone calls and dusting off their CV's! It should be an interesting takeover battle ahead.
Not quite sure of how Sainsbury would justify this or make a success of it.
Big retailers diversifying outside of their area of competence has historically been disastrous,
just think of Tesco with Dobbies Garden Centres and Fresh 'n Easy in the US.
Do Sainsbury actually have any particular knowledge or skills to revitalise Home Retail?
There may be a case for extending "click and collect" to include every Sainsbury location, perhaps?
(Addition: But would that, although it may be convenient for supermarket shoppers to pick up purchases, be something that would actually grow the volume of the Argos online business?).
Or perhaps assets to strip out of Home Retail, although would such properties be able to be sold?
Would this be good for Sainsbury? Imo, they would be taking on something with a buying case
put together by their accountants and the city-boys-on-a-fee but they wouldn't be able to manage it.
No wonder their shares are down almost 5% today. The market is telling them the idea is harebrained
and I wonder whether there will actually be a firm offer.
Btw, this is the breakdown of the sales of Argos which perhaps hints that the John Lewis figures Paul refers to above may read through to good online figures from Argos:
http://i.imgur.com/bF2HEsD.jpg
(Although perhaps figures from people such as Dixons Carphone would be a better guide to the possible performance of Argos as this article does indicate from earlier in the year: http://www.thisismoney.co.uk/money/markets/article... ).
Imran (your message below):
Source is: http://ftalphaville.ft.com/marketslive/2016-01-05/
Hi Jane - where is the pie chart of Argos's sales taken from? Is it from their annual report?
Best wishes,
Imran.
Sainburys know Argos very well as they've been putting Argos outlets into their stores, they also used to own Homebase up until c. 2000. In effect they've had a trial run at seeing how Argos would integrate into their business model and like what they've seen. This is not just due diligence it is to coin a phrase M&S due diligence...
I'd imagine Homebase would be flipped to PE but retaining access to them as a collect point
@janebolacha
I think the City boys may have earned their fees with this one. Yes, it could all go horribly wrong as you say, but I don't think Sainsbury's have a choice but to try. They face a fight on two fronts against the Aldi/Lidl discounters and against Amazon when they launch Amazon Fresh.
And of the major supermarkets Sainsbury's seem to be the only ones who are keeping their thinking caps on while the others are in a tailspin so I think they are well placed to manage the execution risk.
You may remember they actually owned (created ) Homebase way back before divesting themselves.
Sainsbury's used to own Homebase, so interesting that they are looking at acquiring.
Wonder if it could lead to more consolidation, Argos concessions in Sainbury's stores with smaller high st presence for Argos. They have already been opening Argos concessions in Homebase stores.
Home Retail (LON:HOME) spike up probably helped by high short interest. Min 8.5%:
http://www.shorttracker.co.uk/company/GB00B19NKB76/all
I'm not keen to let mine go to J Sainsbury (LON:SBRY) at the current price. Would really like Home Retail (LON:HOME) to defend the bid. Sell off Homebase to DIY retailer. Monetise loan book and return cash to shareholders. Focus on driving argos as the go to retailer for same-day click & collect via digital stores and Amazon style lockers.
Well I got this wrong , it was a coin toss between buying Home or Sbry , I played safe and bought the latter 4 weeks ago...doh
Looks a great validation of the Bull's view on Home
Urrgh, tell me about it!
Two days in, and everything that can go wrong has gone wrong for me.
Paul
Likewise, as per Imran........ your opinion would be greatly valued.
Hi Paul
What's your take on the approach made by Sainsbury's for Home Retail: http://www.investegate.co.uk/sainsbury-j--plc/home/statement-re-possible-offer/201601051222528770K/?fe=1&utm_source=FE%20Investegate%20Alerts&utm_medium=Email&utm_content=Announcement%20Alert%20Mail&utm_campaign=Sainsbury(J)%20PLC%20Alert
Best wishes,
Imran.