Small Cap Value Report (6 Jan 2015) - IND, CHH, JSG

Good morning!
Indigovision (LON:IND)
Share price: 357p
No. shares: 7.6m
Market Cap: £27.1m
Trading update - Scottish CCTV company IndigoVision has issued an update this morning for the extended 17-month period to 31 Dec 2014. Sensibly, the year end has been changed from a totally illogical 31 Jul to 31 Dec, a move which was planned well in advance (so not suspicious in any way). The 31 Jul year end was a nightmare, since the company was trying to close deals when its customers were on holiday! Whereas most companies wind down for a 31 Dec year-end, so now IndigoVision has joined them.
I'm pleased with the speed of the announcement today, which indicates good financial controls are in place.
Sales growth - this was last reported (for the 15m to 31 Oct 2014) at +9% to £43.4m. Today the company updates that sales were +10% for the 17m to 31 Dec 2014, so that's moved in the right direction, slightly. The company is now (as previously announced) reporting in US dollars, so sales were $82.5m for the 17-months.
Translated into sterling at today's date, that is £54.1m, which is £0.1m ahead of the original broker forecast for this year (before the profit warning on 11 Nov 2014). Although recent dollar strength has helped push the sterling number up.
Profitability - the company had already warned that this period's profits would fall short, but didn't quantify that in the trading update of 11 Nov 2014.
Today the company says;
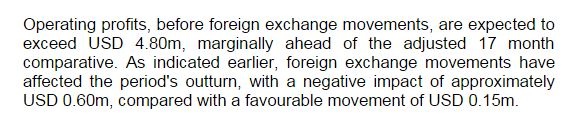
My initial reaction was pleasantly surprised by this. Given that the company had warned on profits a few weeks ago, reporting today that they are slightly ahead of the prior period is not a bad outcome at all. It's not a barn-storming success either, but in the context of a market cap of only £27.1m, these numbers are reasonable.
$4.8m profit for the 17 months works out at £3.15m profit (using exchange rate today of £1=$1.524). That compares with £2.71m reported (also at constant currency) for the 12m ended 31 Jul 2014. So there's been a slowdown in profits in the 5-months to 31 Dec 2014, which looks to have been profitable by about £0.44m - not very good, but not a disaster.
Regional differences - having had a quick chat with the company today, they are frustrated that a sudden & sharp downturn in business in S.America (not helped by the World Cup shutdown), and Asia this autumn turned what would have been an excellent period into a reasonable but not madly inspiring period.
Gross margins - margins are not mentioned in today's update, but there hasn't been an issue here in the past - it fluctuates between 50-60%, depending on the sales mix. The company reported a 57.6% gross profit margin for the year to 31 Jul 2014, so it's an operationally geared business - high gross margins, combined with large, lumpy sales contracts, is a recipe for volatile profits I'm afraid, that's just the nature of the beast.
My opinion - I've checked whether IND has much exposure to the oil & gas sector (which has hit competitor Synectics (LON:SNX) very hard), and the answer is that they don't have over-reliance on it, it's just one sector of several that the company serves.
Overheads - the company is taking a cautious approach to any further increases in overheads.
Sales lumpiness - the company is pushing its mid-market product range, which should help sales become more predictable (i.e. more frequent but lower value sales, hence more predictable). Large one-off projects are now seen as the icing on the cake, rather than being vital to achieving or missing forecasts, as has happened in the past.
Overall - the company is trading well in N.America, and Europe/M.East/Africa. Sales growth of 30% and 19% respectively for the 17m period to 31 Dec 2014 are impressive. That was diluted by weaker performances in Asia towards the end of the year (but still up 11% overall for the 17m). However, it was a 20% drop in Latin American sales which put the dampener on the results for 2014.
The company is pushing hard on lots of fronts, with new products, better sales teams, improved product quality, better marketing, etc. Management sound upbeat, the company's profitable, and has a bullet-proof Balance Sheet, so things could be a lot worse. They also pay nice divis!
If you look at the historic track record, it's actually been quite good. However people perceive IND as a serial disappointer, because it tends to repeatedly look like it's taking off strongly, only to slip back again. Yet these graphs below from Stockopedia are far from shabby for a £27m market cap company (although I would need to double-check the lighter blue, forecast blobs);
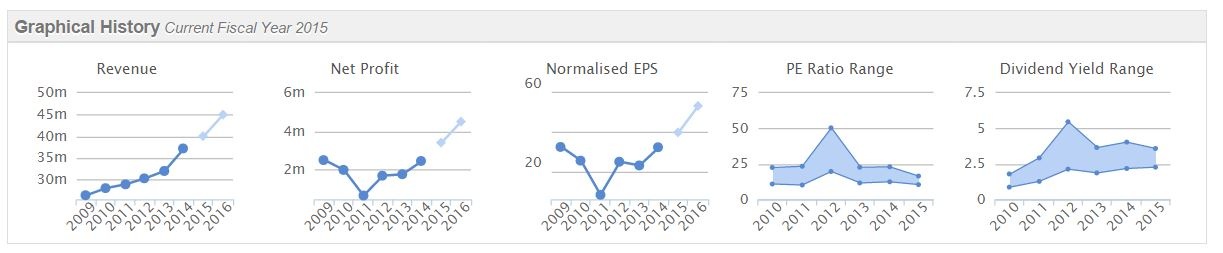
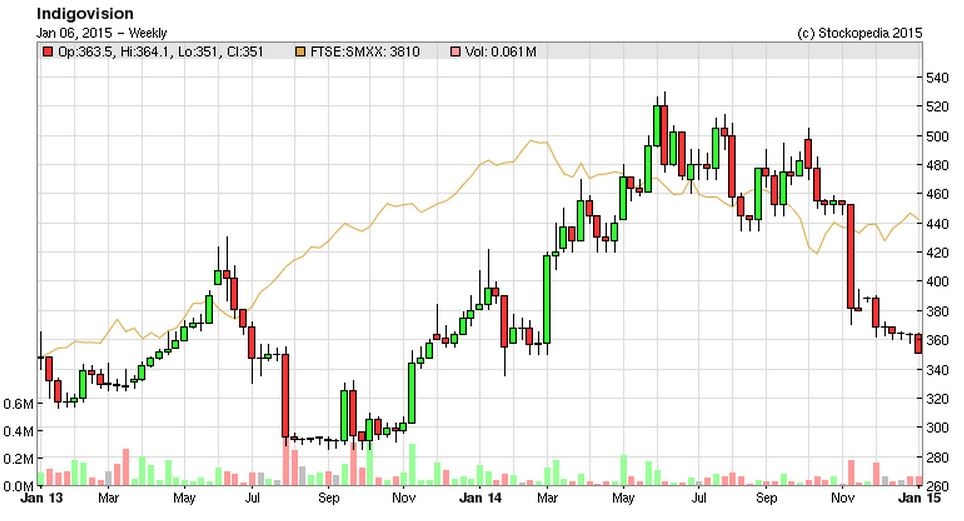
The shares are likely to remain a bit of a rollercoaster, as sales growth ebbs & flows. However, people who had the foresight to buy the dips when everyone else is feeling gloomy, and sell when everyone else is feeling excited, would have done very well out of this share.
I would say we're probably a lot nearer to a buying point, than a selling point, looking at this chart, and taking into account the fundamentals;
Churchill China (LON:CHH)
Share price: 595p
No. shares: 10.9m
Market Cap: £64.9m
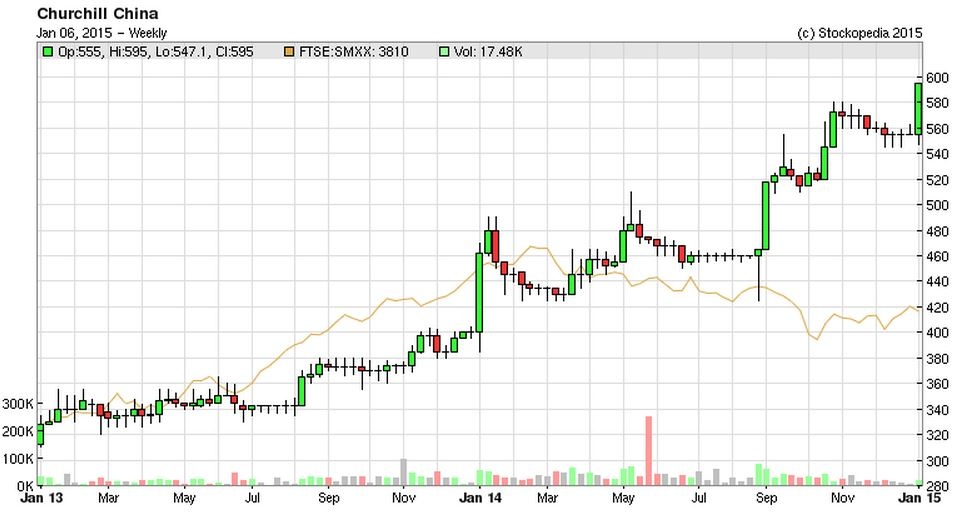
Trading update - an impressive trading update has come out today from this British manufacturer of ceramic crockery, mainly for the hospitality sector. The key bit says;
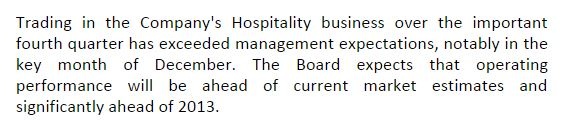
Valuation - let's try to quantify this. The company did 25.0p normalised EPS in 2013. Current broker consensus is for 27.9p this year. So they say "ahead" of 27.9p, and "significantly ahead" of 25.0p. Hmmmm, I'm thinking 30-32p perhaps for 2014 EPS then?
That equates to a PER range of 18.6 to 19.8 times, based on the current share price of 595p. Not exactly a bargain.
I mentioned in my report of 27 Aug 2014 that the broker forecast for 2014 looked too conservative, and that I was expecting to see a modest upward revision to about 30p. Pity I didn't buy any shares, as they have risen 29% since then!
My opinion - nice company, and it's trading well, with that likely to continue. It scores a high 95 on Stockopedia's StockRank system. The Balance Sheet is strong too, and there's a reasonable divi yield. I don't see obvious value at the current price, it looks priced about right, or maybe a touch expensive.
Trouble is, I always say that, and it keeps going up even more! I'm not going to chase it at this valuation, but well done to people who held. Maybe it's better sometimes to just pay a bit more than you're comfortable with initially, and then hold long term as the company grows into the valuation?
Johnson Service (LON:JSG)
Share price: 63.8p
No. shares: 300.0m
Market Cap: £191.4
Trading & strategy update - this textiles hire & dry cleaning group today updates positively;
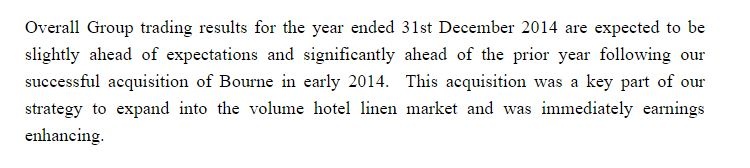
We already knew that results would be significantly ahead of last year, due to the acquisition, so that can be disregarded. So the new news is that they're "slightly ahead of expectations" for calendar 2014.
Valuation - broker consensus is 5.16p EPS, so slightly ahead probably means 5.2 to 5.3p I would guess. At 63.8p that puts the shares on a PER in the range 12.0 to 12.3 - reasonably good value, although there is some net debt too, reported at £29.0m today, so that's 15.2% of the market cap, or 9.7p per share in net debt. When you adjust the PER to a cash/debt neutral level, then it's going to be c.13-14, which is probably about right for a business of this nature.
Strategy - I like this. They are set to close about a third of their shops (on lease expiry), and instead are opening collection/drop-off points in Waitrose & doing more collections from customers, and offices. That should increase margins, and make the business more flexible to economic downturns.
My opinion - it looks a reasonable business, on a sensible valuation, with a good stratregy. It's not cheap in my view, but I could see these shares continuing to be a steady performer over the next few years - the sort of share that could go up maybe 10-20% each of the next 2-3 years perhaps, and pay a 2.5% divi on top, which isn't bad going.
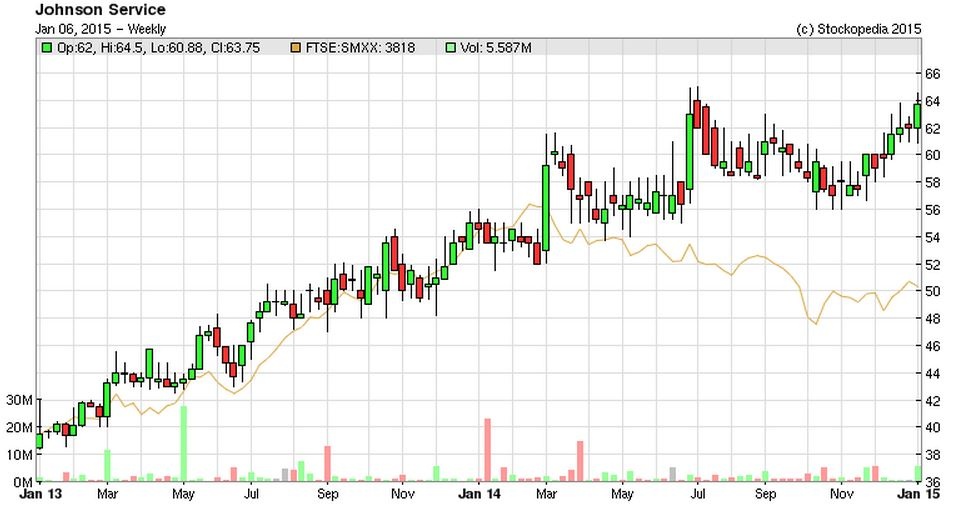
Note from the chart below, how this share has shrugged off the small cap malaise, and has continued gently rising this year.
Regards, Paul.
(of the companies mentioned today, Paul has a long position in IND, and no short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Hi Paul
Great write up as always. I wondered whether you were still going to include the table you were writing up detailing the regional growth figures for Indigovision (LON:IND) in the article above?
Best wishes,
Imran.
Hi Imranawan,
I tried to finish the table tonight, but abandoned it, because the information is not presented consistently from each update. Some give figures, other say "good", etc. Then there are sales shown in different currencies - sterling, dollars, or constant currency. So it got too fiddly & incoherent. Never mind.
Regards, Paul.
Although it's worth pointing out that I did find a better value & higher quality competitor stock and bought that instead, namely Portmeirion (LON:PMP) which has also done very well.
Hello - Paul,
I actually sold a small CHH holding and bought more PMP before the recent rises. In the longer term I think I am more comfortable with PMP's brands and diversication across markets than I am with CHH. Though I've not been back to take a closer look at CHH so that may be a superficial viewpoint.
Your comment about paying a bit more for shares which keep growing is pertinent - but how to do it? I'm not so sure that momentum on it's own is a good indicator as it says nothing about the quality or robustness of the growth in different markets. Actually I'd be looking for companies where the recent and forecast growth is not (yet) fully reflected in the share price momentum? Then perhaps I'd be willing to pay a premium?
really just to say thank you for the insightful articles. I am learning all the time and you are a great source - thank you and please keep it up.
cheers
Mark
Important day for me - one that exemplifies the significant added value of your blog on this site, Paul. I am a one year old PI, starting in January 2014 with some baby steps - and some pretty infantile mistakes. Stockopedia has kept me more or less on the straight and narrow and I decided early on to build separate Value and Momentum portfolios and run them for 12 months (with a couple of solid funds as benchmark). I just about made a profit despite having inevitably high trading costs (my baby steps were fairly baby holdings!) with the Value Portfolio just beating the Momentum Portfolio by a whisker.
But I thought I'd write because for me your analysis of IND was an almost perfect example of not only how to ask the right questions but also how to use Stockopedia charts and data to answer (most of) them and form a point of view.
Then RandomAmbler's comment on Momentum vs Value (or Growth?) hit one of my most vexing nails on the head. For me at least its all about comfort levels and why we're investing at all.
If I've learned anything in 2014 it is that I have to be very clear about what my investing strategy is and stick to it.
I'm going to keep on learning - thanks to you Paul and all your very smart and helpful readers - and hopefully continue to make money.
Thanks again.
This is an interesting comment Paul: "Trouble is, I always say that, and it keeps going up even more! I'm not going to chase it at this valuation, but well done to people who held. Maybe it's better sometimes to just pay a bit more than you're comfortable with initially, and then hold long term as the company grows into the valuation?"
Having read some of Ed's thoughts elsewhere I'm coming round to the idea that momentum is under-estimated by investors as an indicator of potential performance (while growth is over-estimated). This makes me feel a bit more comfortable about buying into a company that has already seen a substantial share price increase so long as all of the other numbers stack up (Zytronic for example).
In fact I'm starting to think that maybe I should be using such relative strength as a filter since this avoids catching a falling knife or trying to time the bottom!
Does this mean relegating P/E as a filter and a means of identifying whether a share is expensive? Probably not but it's no longer a first-line filter for me - more important is the dividend yield since a high P/E (and earnings yield) puts a cap on the maximum dividend yield anyway.
Damian
Hi RandomAmbler,
Fair points, well made. However, the problem with over-paying to begin with for a stock, is that if/when something does go wrong, the drop is considerably larger than for a low rated stock.
Also, surely our aim is to BLASH (buy low and sell high). So we look at the chart, and say "I wish I'd bought it there" - pointing to the low point on the chart. You don't point to the high point on a chart, and say I wish I'd bought it there because it had great momentum!
I think momentum looks great at the tail end of a bull market (which is possibly where we are now, who knows?) but might look disastrous once the trend has turned. I know people say they will be stopped out by then, but stop losses would stop you out repeatedly in the up phase unless you set them so wide that actually they wouldn't protect you very much at all.
It's a tricky one. Overall, I will only pay top whack for a share if I absolutely LOVE every aspect of the business. I liked, but didn't love Churchill China (LON:CHH) so I didn't buy any.
Although it's worth pointing out that I did find a better value & higher quality competitor stock and bought that instead, namely Portmeirion (LON:PMP) which has also done very well.
Regards, Paul.
Hi Paul,
Thanks for the reply. I think that the problem with BLASH is you only know where the 'low' and 'high' points are in retrospect and plenty of shares keep on rising beyond where they seem to be good value.
For example Next (LON:NXT) have been powering upwards for years and have amazing momentum; I wish I had bought years ago! However having looked at the margins on Next Directory sales, and the fact that this segment is now producing as much profit as the retail arm, I decided to make an initial purchase a few weeks ago. Now Next (LON:NXT) aren't cheap but I think that they're priced reasonably given that they're yielding around 4% when you take the frequent special dividends into account.
OTOH I've looked at Crawshaw (LON:CRAW) as well and the momentum there is astronomical - but then so is the value being placed on the company! So much here depends on them executing their expansion flawlessly and I'm just not prepared to pony up for this future promise.
So momentum definitely isn't a magic wand but if you do find a great company which ticks all of the boxes (like Portmerion) then I think that waiting for a possible 'low' point may mean never buying into the shares at all. I suppose that this means I'm looking for an excellent company at a reasonable price, rather than the reverse, and this is a bit of a change for me!
Cheers,
Damian
Hi Paul
Minor point, but I read the Johnson statement slightly differently.
The shops slated for closure are described as "109 branches, the majority of which have leases expiring within the next two years" and they "anticipate that branches will close during the first half of the year."
So,on top of the redundancy payments, I presume that they will have to provide for the unexpired portion of the leases.
My mother's a holder for IHT purposes & quite comfortable with JSG as a "steady,no horrible shocks" type of holding - and we need a few more of these!
Andy
Superb dissection of IND PP, appreciated.
"I would say we're a lot nearer to a buying point, than a selling point, looking at this chart, and taking into account the fundamentals;"
Agreed. Very much so.