Small Cap Value Report (6 Mar 2017) - DVO, UPGS, GAW

Good morning!
News is quiet today so I'll be taking care of things myself here while Paul takes a day off.
Regards
Graham
Devro (LON:DVO)
Share price: 181.4p (-2%)
No. shares: 167m
Market cap: £303m
There are some big differences between the underlying and statutory results today from sausage skin maker Devro.
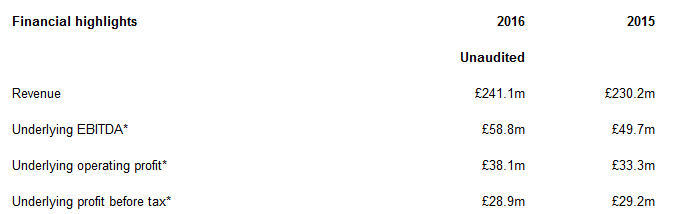
Statutory (or as I like to call it, actual) operating profit comes in at £15.4 million, down from £19.2 million.
Note that constant currency revenues fell this year (by almost 7%), but were more than offset by FX gains.
Dividend: Maintained. Covered by the underlying EPS but not by actual EPS.
Alternative Performance Measures: See explanation below.
Devro is undergoing a major transformation including the construction and start-up of two new plants in China and the US which completed in 2016, a restructuring of operations in Scotland and Australia initiated in 2014 and the Devro 100 programme which will continue until 2018. The incremental costs associated with implementing this transformation are significant, and as a result have been classified as exceptional items.
What to make of this?
Potentially reasonable, except that it's a multi-year programme and so it becomes a bit of a stretch to have a big difference between underlying and reported results over several years.
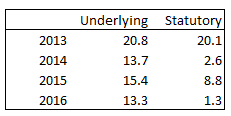
This is the gap between underlying (or "before exceptional items") EPS and actual EPS since 2013:
Net debt has also been rising sharply, up from just £36 million in 2013 to £154 million today.
Using the underlying profit measures, the company thinks it has been earning a return on capital employed over the last two years of c. 11.5%, which is ok if not spectacular.
My opinion
Checking the footnotes, I see that £20 million was spent during the year to establish new manufacturing plants, versus £11 million last year.
While I'm not sure about the other exceptional items, I can see the rationale for excluding these set-up costs from the underlying numbers.
I also see that cash flow was pretty strong (£39 million from operations), although more than a third of this was spent on taxes and interest and the rest was used up in capex, so that the company effectively had to borrow to pay the dividends.
Overall, it's hard for me to get too excited about potentially investing here.
The underlying quality does not seem to be fantastic, the investment programmes are expensive, and the trading environment sounds really tough.
Volumes in Europe were down 7.5% due to "increased competition", down 13% in Russia due to "the extremely competitive nature of the market", down 33% in Latin America, and down 31% in China due to "an oversupply of product at the lower end of the market".
I've previously been a fan of this company but it doesn't sound to me like they have much of a competitive advantage as things stand. Perhaps the new manufacturing plants will change this, but I'd be steering clear for now.
£UPGS (new ticker)
Share price: 155p (+21% against IPO price)
No. shares: 82.2m
Market cap: £127m
Thanks to billytk for requesting this in the comments.
On its website (www.upgs.com), it describes itself as "the leading general merchandising, sourcing and product development house in the Far East".
It looks like an important (if somewhat hidden) piece of the retail supply chain.
From the "global markets" page on the website:
It is our goal to be world-class suppliers to world-class customers. We work with some of the most successful brands, both nationally and internationally.
With over 16 years in business, we have acquired a large and impressive customer base of over 450 retailers and that number continues to grow every year.
We work closely with some of the most popular big name supermarkets and department stores, together with TV shopping channels and selling online via e-commerce.
Retailers shown on this page include Aldi, Amazon, ASDA, House of Fraser, Matalan, Tesco, etc.
UPGS has a portfolio of product brands, according to the Prospectus, being focused on "mass market, value-led consumer goods for the home".
It appears that most of the brands are on license from 3rd parties. For example, UPGS has a licence for the cookware products from Russell Hobbs which runs until 2020.
UK customers were 70% of sales in the most recent financial year.
Sales and "underlying EBITDA" growth are both strong in the short and medium term, achieving £33 million and £4.4 million in each, respectively, in Q1. PBT last year was £6.3 million.
The underlying EBITDA margin was 10% - it's rising, but is unsurprisingly not huge given the sector it's operating in.
Management
The founder remains the CEO, holding 45% of shares at the Prospectus date - projected to reduce to 22.55% on admission. The MD has been at the business since 2005. His stake was set to reduce from 19.6% to 9.8%.
My opinion
I'm inclined to monitor and learn more about this.
For what it's worth, this flotation is not bringing any new money into the company. It is purely to allow the sale of £52.6 million of stock (pre-expenses) by existing shareholders, and provide the other benefits of listing (employee Share Incentive Scheme, etc.)
Those who got in at the IPO price of 128p are already up 21%! But I can see how the valuation could easily make sense, if PBT keeps rising on the current trajectory.
Games Workshop (LON:GAW)
Share price: 905.25p (+2%)
No. shares: 32.1m
Market cap: £291m
This was unusually released just before mid-day:
Games Workshop is pleased to announce that the sales and profit growth, that was discussed in the January 2017 trading update, continues. Income from royalties receivable is also ahead of expectations. In light of the above, profits for 2016/17 are likely to be materially above market expectations.
Sales and profits have further benefitted from the continuing favourable impact of the weaker pound. However, the Board remains aware that there is some uncertainty in the trading periods ahead for the rest of the 2016/17 financial year.
Paul reported on the previous update (also released during the trading day), when Games Workshop reported a "significant increase in sales and profits" for the period from end-November to mid-January.
I see that the broker forecast EPS had nudged up again to 67.7p as of last week.
So that will have to be further revised upwards now.
I never really got into Warhammer - but I appreciated the devotion of those who did.
A little bit of research suggests that GW have created quite a lot of excitement among fans with their latest characters and storyline (pictured below). Some of the latest commentary can be found at this link.
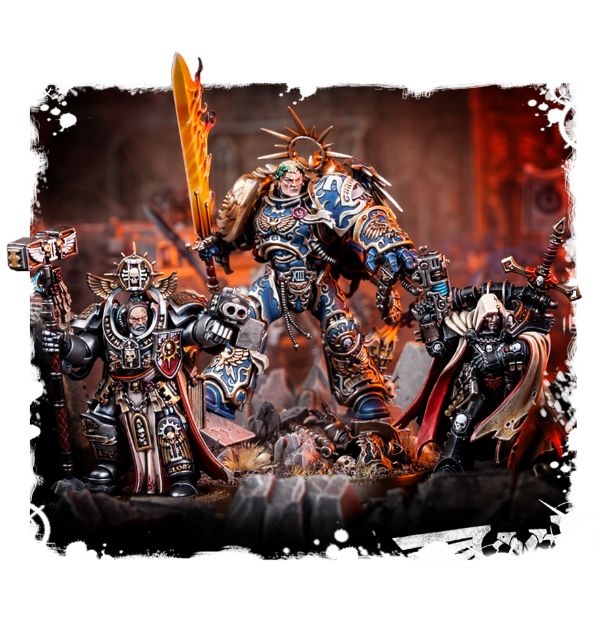
These items can be pre-ordered online for £55. It looks to me as if GW is set up very well for the rest of the year with this kit and the buzz it has generated.
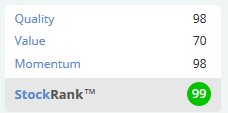
The product cycle will always ebb and flow, but well done to GW for getting things so right recently! And the shares do look good value, with an almost perfect StockRank.
That's it for today, thank you for reading.
Regards
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Thanks Graham.
An observation on Devro (LON:DVO):
"Using the underlying profit measures, the company thinks it has been earning a return on capital employed over the last two years of c. 11.5%, which is ok if not spectacular."
But it seems they are "having their cake and eating it" when it comes to adjusting performance measures.
As you point out, DVO are adding back large exceptional items year on year due pre-operating costs for new manufacturing plants. Management presumably argue that such costs are capital in nature rather than reflective of the underlying operating performance.
Okay, so let's take their point for one moment. If this is the case, those same amounts should be adjusted back into the asset base for the purpose of calculating return on capital employed. As far as I can see, they do not.
So, exclude costs from adjusted EPS because they are capital, but don't adjust the capital base in the ROCE calculation. How convenient! ROCE is therefore overstated in my opinion.
MI
Thanks for the comments on Games Workshop from Graham and others. I have been watching this company for some time but have never quite made the decision to invest because I don't understand why its products are so popular but I guess that is just because I don't share to same interests as wargamers, so perhaps I should ignore my concerns here. I have always admired the company's ROCE and profit margins but the thing which has finally persuaded me to buy is the increasing level of royalties generated by its characters. If the company can cash in on the huge level of interest of fantasy characters as demonstrated in films and computer games this could make a big difference going foward, but regardless of this, the core business seems to be going well. I also like the fact that it is conservatively and transparently, with plenty of information being given to strategy.
GAW - as a one time player of their products I wonder how much long term value they're going to generate.
Hopefully, without being too boring on the details - they've pulled this storyline stunt before in the "Warhammer" Universe - this then led to a revolt amongst the players when they removed the "Warhammer" title and replaced it with "Age of Sigmar". They alienated a huge amount of the player base and many (like me) have never returned.
With their "Return of the Primarchs" storyline in the "40K" universe, which presumably will culminate in another universe shattering outcome, they might sacrifice the goose of ye golden eggs. It's all very well attracting a younger player base, but teenagers generally don't have much money!
Short term looks good, I'd be wary about the longer term. Especially as, contrary to popular opinion on a lot of forums I read, they do face serious competition from companies like Fantasy Flight Games who have a range of Star Wars based games who could well steal a huge amount of players from GAW (whose IP is somewhat limited in marketing potential).
As stated above, I am a disgruntled former customer (who used to spend literally hundreds if not thousands pa on product) of the company so treat my comments accordingly...
Andrea - cheers for bringing up GAW, comment has been added.
Games Workshop (LON:GAW)
Thank you Andrea,
Good news, I've topped up my holding.
Michael
are charts down for anyone else?
There's another positive trading update from GAW if anyone is interested...
Games Workshop is pleased to announce that the sales and profit growth, that was discussed in the January 2017 trading update, continues. Income from royalties receivable is also ahead of expectations. In light of the above, profits for 2016/17 are likely to be materially above market expectations
Thanks for the good news re GAW Andrea. Missed it as it appeared at 11.51. I hold.
Richard
Thanks for the Devro analysis. I'll be staying well clear.
Everyone's going vegetarian, who'd invest in sausages?
Veggie sausages need skin as well!
I think Devro's sausage skins are made from collagen from animals.
Hi Graham, I'd be interested to hear what you make of the takeover of Shawbrook (LON:SHAW). Do you think this might go higher or fall apart? I'd like to think that as they haven't said its a done deal yet there is a slight chance it might go higher. I'm a tiny bit surprised the price hasn't jumped closer to the takeover price being quoted and I'm also surprised the read across to other challenger banks hasn't been bigger e.g. OneSavings Bank (LON:OSB). Perhaps a result of the market having a bit of a flat period after good gains? I wonder what you think?
Interesting that Friday's announcement stated that 'it was not made with the consortium's approval'....could SHAW be trying to flush them out ? What might happen if consortium backed off ?
Hi Graham. If you get chance could you take a look and offer any opinion of new issue £UPGS
Looks like a high growth small cap
Covered it for you Billy, cheers for the suggestion
Thanks for covering £UPGS Graham. I bought a starter position in them in the unconditional period last week for circa 147p after taking a look at the prospectus. My immediate observation / concern was the reason for listing being a selling party which is never the best scenario. I read several misrepresentations of this at the time saying that the company was listing to fund expansion. It just shows how much of a cut and paste job these so called journalist outlets are. They have however just taken on a large warehouse for expansion so perhaps crossed wires.
Management have a big stake in the game here but there is also a decent free float. The 3% and above shareholders have the usual Blackrock and Miton plus there are tie ins for the remaining stake holders. I’d be interested to get further insights but the growth trajectory seem to be in the right direction and if the likes of £G4M and Purplebricks (LON:PURP) can be achieving stratospheric valuations then perhaps....
I’m keen to know more details on their licensing and renewal terms
Divi’s are hinted at for 2017 H2. 50% of post tax profits are muted at for the full year. I’m inclined to carefully monitor any divi announcements from new floats. Thinking of DX (Group) (LON:DX.) Entu (UK) (LON:ENTU) Lakehouse (LON:LAKE) All promised big but floundered. Taken at face value this appears appealing initially