Small Cap Value Report (6 Sep) - CCT, VLK, STAF, CAP, SNTY

Good morning! Very quiet for results today, and the FTSE 100 is set to open roughly flat, at 6,524. Toy company Character (LON:CCT) has issued a trading update this morning. It looks pretty good. They indicate that trading in H2 has been "satisfactory" (they have a 31 August year end), and results will be in line with market expectations. I can't find any current market forecasts, but a little while back they were only for around breakeven, which looks consistent with last year's H2 profit (assuming a similar profit this year), and this year's H1 loss offsetting each other.
Checking our archive here, here is the link for my comments on Character's H1 profit warning on 31 Jan 2013. What is interesting, is that they said then that a strong H2 was anticipated, to reverse the H1 loss, and that is exactly what has since happened. So it appears that this is a company whose outlook statements can be relied upon, in the recent past anyway.
I then reported on their interims on 2 May 2013 here, and wasn't impressed with a very poor performance. However one year's poor results are the following year's soft comparatives, and in today's statement CCT give a positive outlook as follows (my bolding):
Although we are only at the start of the new financial year, we are encouraged to report that the Group's forecasted sales remain on track for the 2013 calendar year, which should lead to a substantially better result for the 2014 financial year.
Remember that they have reasonably good visibility, from trade shows, and forward orders from retailers. So it looks like this could be a good time to buy their shares, providing one accepts the high risk of profit warnings. This is because, being subject to the vagaries of fashion amongst children, their products may or may not appeal to the target market from one year to the next.
At 140p the market cap is £32.3m, and aside from (understandably) two bad years in the aftermath of the credit crunch in 2008 and 2009, either side of that period they have tended to make typically around £6-7m p.a. in profit. So the usual level of profit appears to be c. 20-25p EPS. So if we go for the lower figure, that means they are only on a PER of about 7 times trend, or typical long term EPS.
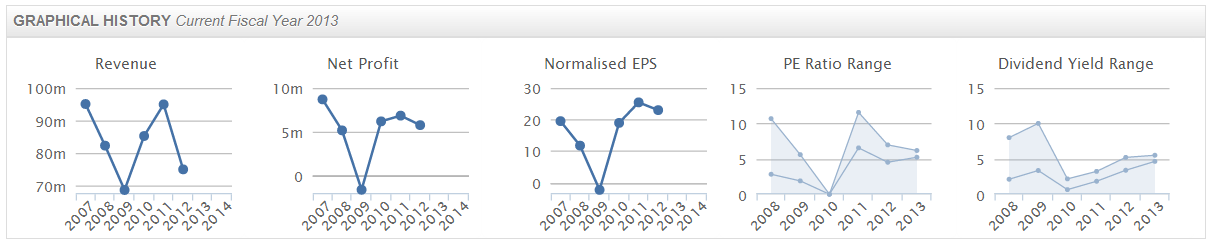
Note the positive trend in dividend yield above, which would be 4.7% if last year's divi is maintained, although given that 2012/13 is going to be a poor year, then I'm not sure whether they will maintain the dividend or not?
The Balance Sheet here is not great, therefore it's marginal for me whether I could invest or not. If I did manage to convince myself the Balance Sheet was acceptable, then the position size in my portfolio would only be small, as to reduce risk, I never take big positions in companies which are reliant on significant levels of Bank debt. Although given that current trading is strong, and the economy improving, that's probably being overly cautious - arguably this is the time to be relaxing concerns about debt somewhat, in a recovery.
There's an excellent article form Allister Heath of CityAM, about soaring Bond yields, which is well worth a read. In my opinion he's probably the best commentator on economic matters, having real insights, and expressing complex subjects in straightforward terms.
I wonder how this will affect equities? Research suggests that rising bond yields in an improving economy are generally consistent with a rising stock market - because although there is a drag on equities from money being withdrawn to invest in bonds that are giving an improved return, at the same time investors become more upbeat about the earnings (and hence dividends) available from equities.
Operational gearing is the key thing to keep in mind with equities - i.e. a typical company with 50% gross margins and a 10% operating profit margin will see its profits rise 50% from just a 10% increase in sales! A lot of people fail to factor in operational gearing, and are hence surprised by how quickly profits rise in a recovering economy. Hence why I'm focussed at the moment on finding companies which are likely to out-perform forecasts, which will turn out to be cheap when people see the higher profits reported in due course. There are still bargains out there, it's just that you have to look harder to find them!
So an apparently high PER may not actually be a high PER at all, if the company is likely to smash forecasts. Broker forecasts tend to lag behind reality both on the upside and the downside, so repeat increases in broker forecasts are a good thing to watch out for. Vislink (LON:VLK) is a good example of this, where I reckon broker consensus is now well behind reality, and the PER of 16 is probably going to turn out to actually have been a PER of about 10 (in my opinion). That makes a massive difference to what the share price should be.
I saw another report (flagged up by another outstanding commentator, Merryn Somerset Webb) which said that the magic number for benchmark Govt bonds is 5%. When rates go above that level, then historically the stock market has performed poorly. We're nowhere near that level yet, but it's something to keep in the back of one's mind in future.
A couple of significant Director deals to report on - firstly, I'm amazed to see that Staffline (LON:STAF) shares are up 4% today, given that they announced their CEO has sold 600,000 shares at 540p. That's a material reduction in his stake, being about 2.4% of the company sold, although he retains 5.8%. The usual "in response to institutional demand" line has been trotted out, which as we all know is nonsense. A sale is a sale, and it's generally bearish, except where unavoidable (e.g. divorce settlement).
That said, I like Staffline a lot, and think the shares will do well long term. Short term though, it's difficult to see a lot of upside, especially after this big Director sale.
Secondly, Directors of Clean Air Power (LON:CAP) have stumped up £103k to buy shares at 9.625p. Fair enough that they were not able to participate in the recent Placing a few days ago, as they were in a close period pending results which have since been issued.
However, the Placing was done at a small premium, and the share price has now risen significantly to 11.88p, so it does raise an eyebrow that Directors are now buying new shares with an instant 23% paper profit. Apparently it did say in the original Placing announcement that Directors could not buy shares due to the close period. So perhaps it also said that they intended buying shares on the same terms once the close period finished? I'll check when time permits.
There's a very bullish-sounding trading statement from Synety (LON:SNTY). However, closer inspection of the last set of figures shows that they are a very long way from having a viable business - turnover is still tiny, and it's loss-making. Although some of the narrative in today's statement has sparked my interest, so might look at this in more detail when time permits?
That's it for today. A very quiet day for announcements. So have a smashing weekend, and see you bright-eyed & bushy-tailed on Monday morning from 8 a.m.!
Cheers, Paul.
(of the companies mentioned today, Paul has long positions in VLK & CAP)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
I think Staffline's director has enough options to replenish his holding. Some were predicated on the firm doubling its EPS, which has happened. Also if the shares sold are whisked away immediately into an institution, perhaps non-institution buyers feel they are, sort of, clutching at air, getting a sense of scarcity.
STAF are still in the screen of screens..
Hi Paul,
W.R.T operational gearing surely selling expenses can sometime be a large proportion of cost (e.g. Sales commissions, freight etc.) & thus variable, but not in gross margins?
Hi jack,
Yes, fair point. There will be some variable costs in admin & distribution costs, so the example I gave was rather extreme in assuming that all costs are entirely fixed! But it was more to illustrate the concept. In practice, operational gearing will be diluted somewhat by variable costs, and of course staff wanting pay rises & bonuses when the company is trading well. But that should still leave behind plenty of operational gearing at the profit level.
It depends on the sector though. Things like software are very highly operationally geared, as the gross margins are effectively 100% on licenses (lower for hardware, implementation & support, etc). Fashion Retailing (my background) tends to be nicely operationally geared, where increases in sales tend to go hand in hand with higher gross margins, and most costs are fixed or semi-fixed.
Cheers, Paul.
Hi Paul,
Can you help me understand the two RNS statements by CAP and CSG please:
CAP: The directors couldn't participate in the recent equity placing until the half year results, but can now purchase the shares at 9.625? Are these new additional shares that they have just issued and then bought themselves? You've just written about this now I see! Thought it didn't quite sound right, be good to hear your comments when you get time to investigate.
CSG: The sale of 1,000,000 ordinary shares of 10p each in the Company, Mr Francis Ives no longer has a notifiable interest in the Company. How are these sold at 10p each when the current price is circa 30p?
Are there are particular books that you can recommend to a complete noob regarding investing in shares? I like your approach to investing with a big emphasise on analysing a company's balance sheet, so anything to help understand company financials would be great.
Thanks again for the great articles you post everyday.
Hi Khalidf
re CSG share sale
It's like saying that a GBP20 note can be bought or sold at say GBP25,
so in the case of CSG, the 10p (nominal value) share can be bought or sold at 30p (market price).
The RNS does not give the price at which they were sold, only that 1,000,000 of shares with a nominal value ( not Market Value) of 10p were sold.
Good morning Paul,
If you have time, are you able to comment on the interims announced today from Gable Holdings Inc (LON:GAH) ? The headline result of 25% increase in pre tax profits is impressive but the increase in the EPS by a much smaller amount, I presume, due to a higher tax charge, is a bit disappointing. The RNS says they are on target to meet "management" expectations for the full year but they might be a long way from the brokers' expectations, which are for 9.7p EPS this year. These results show EPS for the half year of 2.96p.
Regards, Andrew
Andrew
As an investor in Gable I have had a look through the half year results and it appears to me that the two material reasons for the small amount of net profit growth is an increase in claims and expenses associated with insurance activities - this equates to an increase of around £3-4 million.
I remain positive.
Best regards
Ric
Ric,
The growth in PBT for H1 at Gable Holdings Inc (LON:GAH) is 25%, which is great, when compared to H1 in 2012. BUT the growth in profit after tax, which is what the EPS is based on, is only 13%. This is because they have a tax rate of 16.2% now compared to 7.4% for H1 last year. Given that for the full year last year the tax rate was 14.3% I suspect the rate used for H1 last year was either optimistic or just plain wrong. The new auditors have had a big impact on this company which means the results should be more believable. For this reason I'm ignoring the figures for H1 last year and just comparing H1 for 2013 to the full year results for 2012. They have apparently made £3.4m after tax in the first half, compared with £4.9m after tax for the whole of last year. If they can achieve the same results in H2 they will make £6.8m in 2013 which is an increase of 39%. Given their rate of growth they should do even better. A caveat to this though is that interim figures aren't audited so when the auditors take a view on the likely claims payout predictions after the year end they may be less optimistic than the management are.
Regards, Andrew
Hi Andrew,
I don't invest in, or report on financial stocks.
However, I did have a very quick look at the headline figures from Gable & it looks impressive, for the price.
I would question why the profit margin is so high though - is that sustainable, or will competition erode it? Also, are there potential liabilities that could bite back?
Just not my thing. I've never made money on financial stocks, and find the accounts too unreliable & unpredictable, with too many moving parts & subject to often questionable assumptions with geared impact.
Cheers, Paul.