Small Cap Value Report (7 Aug) - FLTA, TAP, PTSG, TCM, UPSG, SGP

Good afternoon!
Today I've covered::
- Filta Group (LON:FLTA)
- Premier Technical Services (LON:PTSG)
- Taptica International (LON:TAP) (added following request)
Cheers
Graham
P.S. It's Paul here - Graham has passed me the baton, and I have added some extra comments on the poor interim results from Telit Communications (LON:TCM) , plus additional comments on Graham's sections below.
Filta Group (LON:FLTA)
- Share price: 134p (+7%)
- No. of shares: 27 million
- Market cap: £36 million
This is a US & UK franchisor of services for restaurants and other food establishments. The main service is FiltaFry (see here) which recycles cooking oil and cleans industrial fryers. There are a bunch of other related services too, some of which are operated directly by the company itself in the UK, rather than by franchisees.
2016 results were hurt by AIM admission costs but otherwise it would have been profitable.
Obviously that makes it a new listing: it has only been listed since November 2016.
I've studied it before and come away with a positive impression: strong growth rates combined with the capital-light franchise model make for a happy combination, in my book.
This trading update (for the six months to June) continues the high growth story:
The Group has experienced revenue growth of some 38% over the same period last year with each of our primary operating segments experiencing double digit growth. We have seen strong performance in both the US and in the UK, with US growth being driven by increasing numbers of franchisees, increased royalties from our existing franchisees and the UK growth being due, principally, to a very strong performance from our owned businesses.
The shares are up today even though the company confirms that H1 growth is merely in line with expectations.
Perhaps the gains are due to the company re-iterating its view that growth is expected "for the foreseeable future", as it takes advantage of cross-selling opportunities to existing customers with more valuable services.
That is a really strong point in the company's favour: once you start selling a restaurant or public canteen services to do with their fryer, it's potentially quite easy to also sell them services to do with refrigeration, for example.
Filta is a Falling Star according to Stockopedia: High Quality, Low Value and Low Momentum:
I acknowledge that value is low here based on current financials but the company should turn consistently profitable when it is used to dealing with the costs of being publicly listed, and does appear to have a really strong growth runway to me - it's providing niche, boring services in an original way, to a fragmented market with predictable long-term demand.
Worth investigating.
Additional comments from Paul: Thanks to Graham for flagging up Filta. I've not looked at it yet, being a recent float. Its business model sounds interesting, and I like the franchise & cross-selling aspects which you flag up, which could drive growth.
I'm inherently very suspicious of all new floats - if the founders are happy to cash out some of their stake, then maybe there's something wrong? New floats often seem to be polished up, heavily promoted, and hence have a glamorous sheen to them initially - which can soon wear off!
So I'll wait until the first set of results come out, to assess it properly, on cold, hard numbers. However, it's certainly going on the watch list, for further research in due course.
Taptica International (LON:TAP)
- Share price: 405p
- No. of shares: 61.5 million
- Market cap: £249 million
More M&A activity from this Israeli mobile advertising firm.
This is a high-flying stock which has shown up on a couple of investor screens due to earnings momentum and a low earnings multiple, and the share price has been storming higher for the past year. Congratulations to anyone who has been holding it!
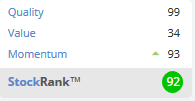
The StockRank remains extremely high even though value is not quite as compelling as it was earlier this year:
I wouldn't expect a company such as this to spill all of its secrets on its website, but it does tell us that it is handling 22 billion requests per day and has data on 220 million users in its database.
Today it announces its second acquisition in two months. The previous one was just $6 million for a Japanese mobile ads company. Today's deal is much more significant at $50 million (though it emphasises that the target has a large positive net working capital balance, i.e. is likely to be more than fully funded in its current state).
The asset being purchased has 180 full time employees working on it and sounds highly relevant. It is a:
"patented auto-optimisation solution for buying effective, programmatic cross-screen video brand advertising."
The idea is to create synergies by integrating this video platform with Taptica's mobile platform, and help to spread Taptica's global presence.
Those synergies look to be completely necessary as the asset being purchased was loss-making at the EBITDA level last year.
$20 million of bank debt will be needed to secure the deal.
My opinion: It's not easy for me to figure out whether Taptica is a good investment. Companies such as these have to be a little bit secretive by their nature. But the case studies on its website are without doubt very impressive: customers claim to get highly effective and focused marketing campaigns, as desired.
Acquisitions make me nervous but again it's possible that they can be executed well. The fact that this new asset was unprofitable last year would again suggest that a bit of caution is required.
Overall, I wouldn't be strongly tempted to invest here as it's still in my "too difficult" basket. Good luck to those who are involved, though!
Additional comments from Paul: the numbers for Taptica look great. So why are the original shareholders selling down? I'm more suspicious of overseas AIM companies, especially where founders are cashing in. That can often be a precursor to bad news.
Note comment no.9 below this article, from Stockopedia member "FREng", who wonders whether new EU rules on data protection might cause problems for Taptica? That's certainly something which investors should be aware of, and carefully investigate.
Premier Technical Services (LON:PTSG)
- Share price: 144p (-4%)
- No. of shares: 104 million
- Market cap: £150 million
Trading Update and Notice of Results
PTSG provides a range of niche building services - safety, electrical, high-level cleaning and training.
Today's update confirms that trading is in line with expectations for the full year.
The Group has previously announced that it was performing well in the first half. This performance has continued, PTSG has noticed an increase in compliance awareness among our 17,000 customers and we have experienced continuing sales growth and strong levels of orders in the year to date.
The expectations referred to above are as recently upgraded for a £20 million acquisition.
Yet again, we find the buy-and-build strategy is in vogue.
Despite raising money in a placing to pay for that acquisition, working capital requirements saw PTSG increasing its banking facilities from £14 million to £20 million.
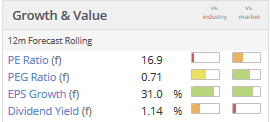
So there is perhaps a little bit of financial strain here. Operationally it remains sound, so investors are sitting pretty. Momentum Rank is fantastic, with a score of 99, and it's hardly a surprise: the shares are nearly 50% above their 200-day Moving Average!
All of the companies I've mentioned today have talked about cross-selling opportunities from their increased range of services. PTSG is no different.
I suppose where I'd be a bit more sceptical of PTSG is that I'm not so sure about the originality of its services as compared to the competition.
Given my scepticism on that crucial front, I'm a bit wary of paying up significant multiples for the shares. So they're overheated now, in my book.
Additional comments from Paul: This is a very good group of niche companies, with excellent operating margins. The CEO is like a machine - stripping out cost, and focusing on operational efficiency in an almost fanatical way.
However, on the downside, I am concerned by slow collection of receivables - debtor days is too high, and I just don't buy the explanation given by management. Also, Bob Morton hold a big stake here, which these days is a negative for me, as his halo is long gone.
The shares have had a great run now, and the price looks up with events, or a bit ahead, perhaps? Mind you, after the Grenfell tragedy, one imagines that PTSG's services might be in more demand? Good thing too, as we cannot allow that kind of thing to happen again in this country.
Telit Communications (LON:TCM)
Share price: 162.25p (down 36.7% today)
No. shares: 129.8m
Market cap: £210.6m
Interim results – for the six months to 30 Jun 2017 are out today.
This company calls itself “a global enabler of the internet of things”. Whilst it operates internationally, I think I’m correct in saying that Telit was originally an Israeli company. Which combined with an AIM listing, is an automatic prompt for me to be on my guard.
I’ve warned readers here many times before (here is my archive on this company). In a nutshell, the problem historically, is that, in my view, the reported profits aren’t real. They were created by capitalising vast amount of costs into intangible assets on the balance sheet. That’s a clever way to create profits in the short term, and enables companies to boast of large (but essentially fictitious) EBITDA profits.
Anyway, these interim results today are really rather poor;
- Revenues – only modest growth of 6.9% to $177.6m
- Gross margin - down a little at 39.2% in H1 2017, vs. 40.1% in H1 2016.
- Adjusted EBITDA - this is a totally meaningless figure for this company, as they capitalise an enormous amount of development costs onto the balance sheet. EBITDA ignores both that capitalised expenditure, and the amortisation of previous such expenditure. So it's a nonsense, fantasy number, best ignored. For what it's worth, adj. EBITDA fell from $21.4m in H1 2016, to $14.7m in H1 2017.
- The company explains that it increased "investment" in 2 recently acquired businesses. This should reduce from H2 2017 onwards. So, if you believe the company, then there could be good upside as profits may rebound in H2 onwards.
- Profit before tax worsened badly, from $4.7m profit in H1 2016, to a $6.7m loss in H1 2017. Clearly a poor result.
So far, so bad! On to the balance sheet, which as mentioned here many times before, I very much dislike.
Placing at 340p per share, raised $49.7m (net of fees. It was $51m gross). This was in May 2017. The participants in that fundraising must be feeling total mugs now - having lost over half their money in under 3 months.
Perhaps that's why Telit has announced today that it's retained FinnCap to act as Nomad & joint broker, alongside Berenberg? Possibly they need a fresh group of contacts to tap for another fundraising? I don't suppose the clients of Berenberg & Cannacord, which pumped in the $51m in May 2017 at more than double the current share price, would particularly welcome another call to gauge their interest in injecting more funds still, if that is required?!
Net debt of $9.3m doesn't look too bad - down from $17.7m at 31 Dec 2016. Until you remind yourself that the company raised $51m from shareholders during that 6 month period. Where has all the money gone? Acquisitions, divis, and working capital absorption. In my experience, a company that claims to be highly profitable, but seems to soak up cash from investors at an alarming rate, is usually an accident in progress, let alone an accident waiting to happen.
Dividends - the interim divi of 2.5 cents last time has been passed this time. So that's another sign of a cash-strapped business. It's a bit daft to raise money from placings, pay some of it out in divis, then face another placing because you're running out of cash! The company says it will consider a final dividend, depending on circumstances.
Full year guidance - this section of the RNS today is very useful, but the key question is whether we can believe it or not? I'm sure the company gave guidance to the mugs who participated in the 340p placing just 3 months ago, and have already lost over half their money. So personally, I'd take it all with a pinch of salt. Anyway, this is what Telit reckons it will do for the full year 2017;
- Revenues of $400-430m, suggesting a good improvement in H2 vs H1.
- Beyond that, it's confident of over 15% revenue growth in 2018.
- The business is naturally H2-weighted, so certification delays for products have worsened the seasonality this year. ".. confident of a strong H2 performance"
My feeling is that the outlook guidance seems pretty good. So if you like this company, and believe management assurances, then maybe this share price plunge today could be a good buying opportunity?
Personally, given the history of very aggressive accounting, I'm not prepared to believe the guidance. If I miss out on a big winner from here, so be it. There are plenty of other good companies to invest in.
Amortisation charge for development spending - has shot up, by 80.7%, to $8.0m in H1 2017. This is the problem with pimping up your accounts, on speed, by capitalising a ton of development costs. It creates nice profits for a few years. However, then the amortisation charge explodes upwards, and wrecks your future years' profits. So previous aggressive capitalisation does come back to bite, longer term, as in this case.
Balance sheet - has certainly improved after the big placing. NAV of $169.9m is best ignored. NTAV is a better measure of reality, and looks OK at $46.1m.
However, there are red flags on this balance sheet, and I don't like the look of it one bit.
Inventories seem to have risen sharply, to $37.9m.
Trade receivables also look too high to me, at $97.3m (well over half H1 revenues - that's too high, and suggests there could be some nasties in there, maybe?).
"Other current assets" of $18.1m - looks odd to me. I hate stray debits on the balance sheet, as they can often be signs of profit being inflated, as happened at Globo.
Note that $17.9m of costs were capitalised into intangible assets in H1 - an enormous number, and another red flag.
Director selling - my attention is drawn to massive Director selling, very recently, in late May 2017, at 340p, just after the Placing. What a marvellous coincidence that the CEO managed to bank £24m in disposal proceeds (apparently to pay off a loan) just before a profit warning & share price crash! Who would have thought it?!
Cashflow statement is just terrible - awful. At best, this company seems to be trading around breakeven, in cash terms. Although maybe an improved H2 performance, and new contracts such as the Tesla Model 3 contract, could improve that?
My opinion - I'm trying very hard to find a form of words that will not result in my being sued.
I'd just say that, for me, as explained above, these accounts have more red flags than a popular beach in a storm, with a rip tide, and the danger of a passing typhoon. Plus the possibility of sharks, and jellyfish.
On the other hand, if you're prepared to believe management assurances, then the business could recover nicely in H2 - which they are pointing towards. The IoT sector seems an exciting growth area to be in.
Therefore, I think opinion is likely to be polarised with this share. I don't like it at all, but there's some good stuff in today's update (on the apparently positive outlook for H2 & beyond), which if it comes to pass, could result in a nice rebound in the shares, who knows?
So it's up to you, dear reader - do you see positives or negatives here, or a mixture of the two? Let's have a heated debate!
A couple of quickies to finish off with, before I explode with anger about Twitter, and Jeremy Corbyn's attitude towards brutal, socialist dictatorships like Cuba, Venezuela, and every other country that has tried out socialism - pretending in that calm, avuncular style that nothing is wrong! Democracy is under threat! Why aren't people concerned? They bloody well should be.
UP Global Sourcing Holdings (LON:UPGS) - here's a potentially interesting company. It was recently featured in a well-known tip sheet. I've subscribed for nearly 20 years, and I think it's a great source of ideas in a bull market. The writer takes a lot of trouble to visit, or at least talk to companies. Also he seems shrewd, and the long-term track record is amazing.
So I have a lot of respect for this publication, although as with everyone (including me), plenty of mistakes are made.
The share price has spiked up today, on the back of an interesting write-up. I like the sound of it, but it's not really for me. The company seems a sourcing conduit, between British retailers, and Chinese factories.
It's worth a look, in my view. In the past though, price spikes on tipsheets could be a sign of a very toppy market. Sometimes 10-20% price spikes can create lovely liquidity to sell into (thank you, several times, Simon Thompson!)
I don't like all that share tipping nonsense. People should do their own research, then have the courage of their own convictions, not follow the utterings of some guru, telling them what to do. You will never get buy or sell tips here! Why the hell would I want to advise or tell people what to do? I cannot think of anything worse. It's actually all about learning from each situation, and becoming better decision-makers. I think we all help each other do that. Hence the value of our wonderful comments section here, with some remarkably brilliant commentators, like Jane (who spotted IQE a long way back), and bestace (who's brilliant, on a daily basis), and many others.
My brief skirmish into fund management, put me off it for life! The clients expect superb, faultless, performance, all the time. Some of them constantly badger you when things aren't working out as planned. Forget it! I don't need their money anyway, as I can make it myself with my own limited little pot of money. For tiny amounts of fees, people expect personal attention. Would they expect that from a lawyer or accountant?
Overall, life is much simpler, if you have: no clients, no employees, and no hassle! I heartily recommend it to everyone, if you can figure out a way to make a living that way, then do it. Also, that gives you the freedom to say what you want. I frequently criticise companies in which I hold shares. So what? If the share price goes up or down, it doesn't matter to me. It's the long term prize that matters, most of the time.
The best way, in my view, is to have few financial needs. If you don't need much money, then you don't need to earn much money. A modest income from doing something you like, such as writing a marvellous blog for the UK's top financial website, is a good place to start!
Other than that, who needs a car? When my lease expires, I'm handing it back. If I need a car, I can rent one from Avis for 4-days, for £79 - an Astra. Perfectly adequate. That's not per day, that's for the full 4 days. A bargain, I reckon!
SuperGroup (LON:SGP) (in which I have a long position - this looks quite good too, topped up today. GARP, I reckon. Although VISA data today sounded negative for clothing retailers. So maybe we need to keep our options open?
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
Hi Paul,
Just a quick one - in telit statement above you say the following....
Note that $17.9m of costs were capitalised into intangible assets in H1 - an enormous number, and another red flag.
Where did you get this figure from?
I am a newbie and still finding my way....thanks for everything.
Kevin
Filta Group (LON:FLTA) breaking out from the first primary base since the IPO.
For those looking to dig into Taptica in more depth - this might help https://www.pulpix.com/insights/blog/what-are-ssp-and-dsp/. There are lots in this space https://www.quora.com/Who-are-the-leading-mobile-SSPs-in-India?share=1, http://investors.matomy.com, https://clickky.biz/publishers/ - I am not sure that GDPR will have much impact other than that it will be the same for everyone. This is quite interesting as well https://adexchanger.com/tv-and-video/end-ssp-era/ - i sent an enquiry to Taptic and signed up to their site and have received no reply.
Telit - the parallels with Globo seem alarming. Has finncap replaced Canaccord ??
I didn't understand the update on SGP. Is there any news?
It looks like it has just broken through it's 200 day MVA...
Two other Israeli companies on AIM are worthy of your investigation.
AFS Amiad Water Systems. No one knows irrigation better than them.
MWE Wireless Edge. No one knows the military importance of antennae better than them.
Stockopedia metrics are excellent for both.
General comment regarding Taptica International (LON:TAP); the Stockopedia data tells us that this is a good business. So, while we might not like the owner's sell down, and while some will be licking their wounds from the problems with other overseas companies some of which may have been based in Israel, I think this is one where you either choose to go on the Stockopedia metrics and remove sentiment from your decision, or stick with your sentiment and gut feel.
I am long on Taptica International (LON:TAP) because I decided to go with Stockopedia metrics on this occasion. (Why I decided to do that this time when on other occasions with other stocks I didn't I cannot adequately explain). I may be proved to be a mug. However, being based in Israel and making what appear to be reasonably valid acquisitions do not represent adequate reasons to reject to them from my perspective.
Agreed with that. I think its fair to query why an overseas company lists overseas, but I think often people place too much emphasis on this. I do query the massive skepticism that appears to exist towards Israeli stocks in the U.K., which I think unduly prejudices a stock like Taptica International (LON:TAP). This simply doesn't exist in the U.S., which is why the majority seek a listing on the NASDAQ. I would not be shocked to see Taptica look into this in the future.
Re Telit, I believe they are originally Italian. They were called Telital. They acquired a Motorola unit in Israel.
http://www.telit.com/about-us/company-facts/#History
hell yea I'm down with this site have a scotty red flag system. it needs to be called "scotty red alert"
hehe, I like the "Scotty Red Alert" flag idea - but that's kind of what these SCVRs are for - if I find dirt that makes me sneeze, then I cough, sneeze & shout from the rooftops. And I'm often right, which is why people read these reports.
Once or twice per annum, I get an email asking, "how do I unsubscribe from your emails". I bite my tongue (whilst thinking to myself, what a THICK ####!), and then calmly point out the unsubscribe link on EVERY email. Jeez.
P.
im talking about putting the scotty red alert on stock reports next to tags such as high flyers, sucker stocks etc.
That got a chuckle this morning :)
i thought companies were obliged to put out a trading statement if profits were going to fall short of expectations ? (or indeed exceed them). in the case of Telit Communications (LON:TCM) for example they put out a statement not so long ago which detailed the increase in revenue for the first 6 months, so we all expected that. but there was no mention of profits being below expectations...which is of course what has happened...i thought they were obliged to state this under LSE rules ?
TAP - another Israeli company that in the end is going to goto the dogs... a big load of crap... even the CFO sold £465k worth this April - he only holds 0.48% of the company and sold half, a big red flag. Another is the increasing debtors and the recent acquisition.... placing time for more mug punters to come and give them money in my honest opinion.
I'll be absolutely honest and say, I'm genuinely not too far away from this assessment of Taptica International (LON:TAP) The company is involved in an area not only difficult to understand technically (fair play if you can comprehend proprietary algorithms, though!) but complicated to predict revenues.
I don't think anyone doubts that mobile advertising is a huge area, and I'm sure nobody believes they are ahead of the curve by identifying this, but I am genuinely worried by a few things, the CFO sale being one, the website being another. The bridging loan also looked very odd to me in today's RNS. I generally don't like acquisitions to aid growth, either, unless the company has significant form in the area.
I wish all the best to holders, and have no plans to open a long or short position.
When something is too good to be true, it usually is.
IG
It does seem that Taptica try to use jargon to baffle rather than educate investors as to what it is they actually do.
However they do have a history of aquisitions aiding growth, their purchase of AreaOne helped them grow profits 8 fold last year & a sale by a single director is more than likely for personal reasons than insider knowledge & the share price has risen by 1/3 since that sale so not a great insider sale if thats what it was.
Hi InvestedGeordie
Following up on your note about the share sale by the CFO of Taptica International (LON:TAP) being one of your concerns. (I hold). And thanks for prompting me to look more deeply (see below).
According to this RNS (22/03/17) the CEO still holds 18.2%
https://www.investegate.co.uk/taptica-int--ltd--tap-/rns/director-pdmr-shareholding/201703220700081460A/
Detail of major share holdings is on page 19 of the 2016 annual report.
http://www.taptica.com/investo...
The report states that as at 7 June 2017 total issues Ord. shares 60.558m and 8.088m held in treasury (13.36%).
CEO hols 18.2%. I interpret (but do not know for certain) that three others close to the company hold 18.3% then a cohabiting couple (disclosed in the notes) hold 10.6% between them. Thus 41.1% between these four people. Then six institutions hold 43.16% between them.
If my interpretation is correct this implies these four people and the six institutions hold 90.26% of issued shares!! Wow .... that has surprised me.
Will I still hold???? time to think more. Comments welcome
Regards
Howard
Hi Howard
Had you seen this http://www.globes.co.il/en/article-taptica-founders-earn-51m-in-aim-offering-1001198754
Hi circuslover
Thanks very much for that link. That offers useful insights.
The article has helped me understand that the four insiders I mentioned are the Angel investor, the CEO, the former COO and her co-habitee. The article states they sold 16.9% of their holdings (26/07/17).
As the June report states between them they held 47.1%, this suggests that instead of 90.26% of shares being held by insiders and institutions, 73.36% are now liquid (if they haven't been hoovered up by the institutions or other big holders).
Looking at the recent share price graph, whereby the 26/07/17 event can be seen in a SP drop, I gain some confidence in that after that the SP has risen steadily.31/07/17 382.5, today 08/08/17 407.4 up 6.5%.
I think I'll hold for a while. But I keep my -2% Alerts primed to trigger.
Many thanks for the link.
Other comments gratefully received.
Regards
Howard
re TCM ...these accounts have more red flags than a popular beach in a storm, with a rip tide, and the danger of a passing tycoon.
Deliberate or not 'tycoon' for typhoon is a typo gem.
Tycoon is just what this company needs, surely? Several tycoons.
"........have more red flags than a popular beach in a storm, with a rip tide, and the danger of a passing tycoon. "
That may well be an intentional slip, either way it's amusing & quite possibly correct.
Hehe, sorry about that - am still away from home, trying to type fast on a tiny laptop, with reading glasses that need replacing, so am afraid there will be more typos than usual at the moment! I normally re-read carefully afterwards, and correct them. As you say, sometimes they can be quite unintentionally amusing - e.g. "moist paperwork", and "passing tycoons"! LOL!!
P.
Can I just ask that people try to always put the company name or £ticker into every comment here. I quite often find it confusing when people don't, as it's not necessarily clear what company they are commenting about! So it really helps, to confirm the company name or ticker in every comment.
Thanks, Paul.
Graham, for me the growth for #PTSG will be strong and will come (sadly) from Fire Safety & Cladding contracts post Grenfell. Looking at the "News" section on their website PTSG’s specialist rope access team is being awarded a steady stream of cladding testing & fire safety contracts for thousands of high-rise buildings. http://www.ptsg.co.uk/news/
Premier Technical Services (LON:PTSG) remind me of Lakehouse (LON:LAKE) , in that they are growing by acquisition and are less a business than a conglomerate of separate ventures. They may be a little more specialised, and a bit higher margin, but there are marked similarities.
Beginner - #PTSG I think you need to look a bit deeper. Another contract awarded today & currently up +8%. Nothing like #LAKE IMO. A much bigger Moat as they are specialists in their field. A very "hot" field at the moment! DYOR.
Yes, very different in many ways, and I can definitely see the price increasing from here. But it still seems a little overpriced for a small scale contractor (PER = 17). One poorly performing acquisition or one contract failure, and this could stumble in a big way. And stumbling is to be avoided at all costs if you are working at heights!
I do hold PTSG so maybe I am in denial, but I believe that Graham's observation that there is no "originality" in its business overlooks what makes them a bit special. Their specialisation is in working at high levels, so cleaning and maintaining very tall buildings and bringing this knowledge to safety inspection and insurance support.
Steeplejacking obviously has a long history but maintaining - for example - tall glass-fronted office blocks is a whole different thing and PTSG is bringing its weight to consolidating a fragmented industry that is charged with higher standards than ever and more challenging spaces.
Anyway, that's the bull case for the business model as I see it and I would love to hear where I am misleading myself.
I wonder whether Taptica International (LON:TAP) may be affected negatively by the EU General Data Protection Regulation (GDPR) that comes into force next year (and that is mirrored by the UK data protection bill that the Government published today).
Internet marketing depends heavily on databases of personal information, most of which will have been collected without fully informed consent. The max fines under GDPR are $10m or 4% of global t/o, whichever is greater, so it's a material consideration.
Consider FREng that Europe represents less than 30% of Taptica International (LON:TAP) sales and the recent acquisitions dilute that still further. So the GDPR is not likely to have a major impact. The market reaction to this news is therefore pretty sanguine.
Graham
Good point about the low percentage of Taptica International (LON:TAP) sales being in Europe, though AFAIK, GDPR covers all processing of the personal data of EU citizens, so the impact may be greater than the sales percentage.
One of the more reliable poster's on advfn (nurdin) has posted an email reply from Taptica when queried on the potential impact of the EU regulation:
"Many thanks for your email to Taptica. They have asked me to respond to your query regarding the impact of the European regulation.
We are still examining and evaluating the finer details of the bill but on first reading, the bill will not have an impact on Taptica as the Company uses annonimised data rather than personalised data such as name, address etc.
Hope this answers your query."
If that's correct then Taptica are largely isolated from the impact of GDPR - the aim is to prevent personal data being collected and used without consent. As long as the data can't be traced to an individual then the impact is largely benign. However, this has been known about for a year, so it's a bit surprising they don't already known what the impact is on their business.
timarr
I'm not a shareholder in Taptica International (LON:TAP) and I haven't studied their business in detail, but that seems bonkers.
It is perfectly reasonable if all they do is statistical analysis of the data they hold. But if they use it in any way to help companies to target advertising to individuals, or to assess the impact of advertising campaigns on individuals, then they are processing personally identifiable information.
GDPR specifically defines IP addresses, for example, as personal information.
If they are never processing tdata hat is personally identifiable, then where is the revenue growth coming from?
Interesting ...
http://www.taptica.com/privacy/
Pseudonymous personal data under GDPR is not excluded - it just makes it less risky to hold. However, as long as the personal data - in this case the Device Id - isn't shared and they don't hold any other personally identifiable information then they're pretty safe from most aspects. However, a Device Id is still considered personally identifiable information and pseudonymisation doesn't change that - so consent is needed and they'll need to re-establish it on the basis of GDPR.
So, in short, on the basis of the above link I think they're wrong: GDPR will have some impact. On the other hand, as long as they're careful I wouldn't think it would be a major problem because the data isn't used and isn't usable to actually identify people.
Of course, the link may not be representative or may be out of date ...
timarr
So glad I obeyed my stop loss (and gut feeling) on TCM a while ago, results today look appalling... and share price -35% is therefore unsurprising
Hello Graham,
I look forward to your thoughts on Imaginatik (LON:IMTK).
I met the then CEO (Canadian I think from memory) some years ago and felt then that it was a business run for the benefit of the directors and would have been better as a private company.
I have seen nothing since to alter that view. I welcome alternative opinions.
Very best wishes,
Steve
A Paul favourite Best Of The Best (LON:BOTB) has dropped quite a bit over recent weeks from 400p to 290p today. I can't see any news that might explain the fall and the trading is quite low volume, so I assume it is part of the fun of illiquid small caps. Anyway I thought I'd flag to readers as in my opinion this is a good summer buying opportunity. I picked some up last week at 320p after waiting very patiently since January to buy some at a reasonable price.
Paraic,
Previously I have held Best Of The Best (LON:BOTB), but I sold after the last set of results, as the revenue growth disappointed me - I think this was around 400p.
Since then, the site has discounted ALL tickets by 50%, instead of a few different cars every week. Does this suggest they were seeing stagnation and needed to make changes to drive growth?
Maybe, but what is impressive is the increase in website traffic up from 0.35m in May to 1.35m in June to just over 1m in July (according to similarweb). The discounting doesn't concern me as the the most popular tickets were always the discounted ones anyway, so I don't expect margins to be effected too much by this.
However, with the massive spread, I'll be waiting for this to bottom out before buying in. With no upcoming catalyst till around January results this could continue to fall as the valuation still looks high to me.
Thanks,
Joe
DYOR (no position)
Thanks. I'm keen on the shares because:
- In an interview with Paul Scott (on his Quality Small Caps website) the CEO said they were looking at options for overseas expansion
- It has given out generous dividends in the past
- Stable business, easy to understand, with no debt
- Any VAT rebate (mentioned in recent RNS') would be a nice bonus
- They were planning to dramatically increase marketing spend this financial year which would hopefully translate into higher revenue growth
I take your point about slowing revenue growth but for me that was mitigated by the above points. It'll be interesting to see the impact of discounted tickets on sales and profits.
I would be wary of using similarweb. I've tried to do so in the past to my detriment.
There have been quite a few studies by reputable organisations to test the accuracy of similarweb et al. Here's one that I just found:
https://www.screamingfrog.co.uk/how-accurate-are-website-traffic-estimators/
It's relatively long, but if you skip to the Results section you should get an overview of what I am referring to.
The only way you can be sure Similarweb data is correct is if a search is marked "verified."
No position in £BOTB
Paraic84 re Best Of The Best (LON:BOTB) not quite 290, 307 according to IG but if you bought at 290 you got a good deal! I do wonder if people will be less likely to enter draws to win cars in a downturn, or more likely... do they have any Tesla Model 3's to win?
I'm interested on reading about Telit's huge fall and whether it can recover - Paul's written some great stuff on it before.
Hi runthejoules,
Paul here! I also noticed that Telit Communications (LON:TCM) has plummeted today. So am glad I sounded warnings about it here in the past.
Graham's writing today's main report. But either him or me will cover Telit - I've got some spare time today, so have emailed Graham to say that I'm happy to write an additional section on it. So one way or another, we'll get round to covering it, later today! (possibly this evening)
Cheers, Paul.
Hi Paul,
Just read back there through some your observations on Telit - Great commentary and thanks.
Wondering, for us who count reasonably well but have little idea on company accounts - Is there any way the Stockopedia numbers can be used to identify potential trouble in shares like this.
I don't know - Is free cash flow of 0.04 compared to cash flow of 0.4 bad.
Generally just wondering if there's any kind of high level (Stockpedia picutre) red flag type of check for those of us uneducated in accounting. Asking really because generally it looks like a decent share - Based on the other Stockopedia numbers.
Thanks in advance for any kind of pointer.
Hi Matylda,
Good idea. I'm seeing Ed & the Stockopedia team fairly soon, for a meeting, so we can have a discussion about maybe creating a Scotty red flag system? It seems to me there are some very obvious warning signs with dodgy companies - primarily excessive debtors, and excessive capitalisation of costs into intangible assets.
I would add to that negative NTAV, and excessive gearing.
Plus certain entire sectors (e.g. junior resources, which are for gamblers only), contracting companies, overseas+AIM, etc.
When/if we ever have time, would be quite fun to construct some simple rules on that front.
The other thing is to remember that in a bull market, people ignore a lot of warning signs. So I think a successful strategy might be multi-layered, and would allow through some speculative stuff in a bull market, but then slam the door shut quickly once the market turns bearish.
All food for though, so thanks!
Regards, Paul.
Maybe it could be added as a short screen?
Hi Paul,
I think this is a brilliant idea, which could be really quick to implement into beta. I feel in the market we're in, it would be incredibly useful, and could be a great tool for users to run against their own Stocko portfolios.
Thanks,
IG
Hi InvestedGeordie,
"I think this is a brilliant idea, which could be really quick to implement into beta."
Yes I agree completely - I am a marvellous ideas machine, but I tend to duck below the parapet when it comes to actually doing some work LOL!!! Cheese!
PP.
Hi Paul,
Another vote for the Scotty red flags. But I'm of the view that the only thing to relax on in a bull market is valuation. Keep the quality measures intact. If people want to ignore red flags, then that's their choice. The system should still hoist them.
Shouldn't they be called "Scotty dogs"?
Shouldn't they be called "Scotty dogs"?
I like it!
PP.
add short interest as I increasingly find open interest as a good leading indicator of trouble ahead. Telit Communications (LON:TCM) has had open interest increase from 3% in April 2017 to almost 12% as last week.
http://shorttracker.co.uk/comp...
The big increase in trade receivables shown in March may also have been a warning fo troubel ahead
Technically the price action turned bearish after the high in May of 380p which was a revisit of 2015's high and a double top. . Telit Communications (LON:TCM) went on to lose the 200DMA at the start of July while the ominously named death cross (where the 50DMA drop below the 200DMA) occurred last Friday
Like the marine analogy especially given I was surfing with my nephew this afternoon and teaching him about the various flags...red meaning make another plan for the day besides getting in the water. I like this space and this technology but there are a lot of flies in this ointment I'd consider a position nearer 100p and given the volume profile and price history, 80p may not be out of the question. May never see those levels but they will go on an alert for review and action
Your forensics on Telit Communications (LON:TCM) put me right off this name over the past couple of years despite my keen interest in this space and M2M. On a lighter note, I always thought Oozi Cats should have been a character in Top Cat not the CEO of a "high flying" tech company. Nice job again Mr Scott.
Much appreciated Paul - Look forward to what you and the guys come up with - The Short interest mentioned by someone seems a decent idea although I suspect this would be a manual job rather than something available via an automated feed.
Hi Graham, I am quite interested in Taptica which appears to be in a good area and would be very interested to have your views. I know it crossed your path quite recently for the first time.
Regards, Peter
Hi Peter, thanks for bringing that to my attention. I realise that quite a few readers are interested in it so I've added a few comments to the report. Cheers!
Graham
Thanks for that Graham. If I meet them or get any better insight I will give you feedback. I remain a slightly nervous investor.