Small Cap Value Report (7 Jun 2016) - SRT, VP., BLV, VNET

Good morning!
A shortish report today, as we have British Gas coming round to fit a "Hive" wireless controller for the boiler, and a washing machine repairman also visiting. Plus an investor lunch to get ready for.
In case you missed it, I had a 15-minute chat with Simon Tucker, the CEO of Software Radio Technology (LON:SRT) (in which I hold a long position) last night, asking him a few questions on their results, published yesterday. The link to the audio is here.
I know from the email list that quite a lot of PR companies & brokers read these reports. So just to flag up that if I write something positive about a company here, then (time permitting) I'd probably be interested in recording a 10-15 minute chat with the CEO or FD. Therefore do feel welcome to get in touch with me, to arrange, if that situation arises.
These interviews are a great way to communicate with c.1,000-3,000 private investors, via me. The feedback is really positive from investors, who seem to find these interviews helpful, and I enjoy doing them, so all good. I don't usually charge a fee to the company or the listeners, and there are no ads.
A reminder, it's the Q1 trading update for Boohoo.Com (LON:BOO) tomorrow morning. I know a lot of readers hold (as do I).
VP (LON:VP.)
Share price: 710p (unchanged today)
No. shares: 40.2m
Market cap: £285.4m
Results y/e 31 Mar 2016 - another good set of figures from this group of niche hire businesses. A few key points:
Revenue only up 2%, to £208.7m
14% increase in basic earnings per share, pre-amortisation, to 62.21 pence (PER of 11.4)
Net debt up by almost £20m, to £86.1m - due to expansion of hire fleet, and 2 small acquisitions.
Operating profit margin looks strong, at 15.3%, and finance costs are modest.
ROCE is reported as 16.3%, which is a good return.
Divis up 14% to 18.85p (interim + final) - yield of 2.7%
Outlook comments sound positive:
Vp has, in the year under review, reported good progress, with further improvement in profit margins and returns, delivered from a relatively modest growth in revenues. This trend is expected to continue as the varying demands of supportive infrastructure, housebuilding and construction markets play against a challenged oil and gas sector.
The new financial year has started well and we look forward to another year of progression for Vp and our shareholders.
Balance sheet - overall this looks OK to me. It's an equipment hire group, so fixed assets are large, and part-funded by debt.
Net assets was £121.4m, less intangibles of £46.4m, gives NTAV of £75.0m.
I like to look at loan to value with hire companies. So in this case, fixed assets are £167.2m, and net debt is £86.1m. So that gives a loan to value of 0.51. In other words, the hire fleet is funded half by bank debt, and half by equity. That's about the right level, in my view.
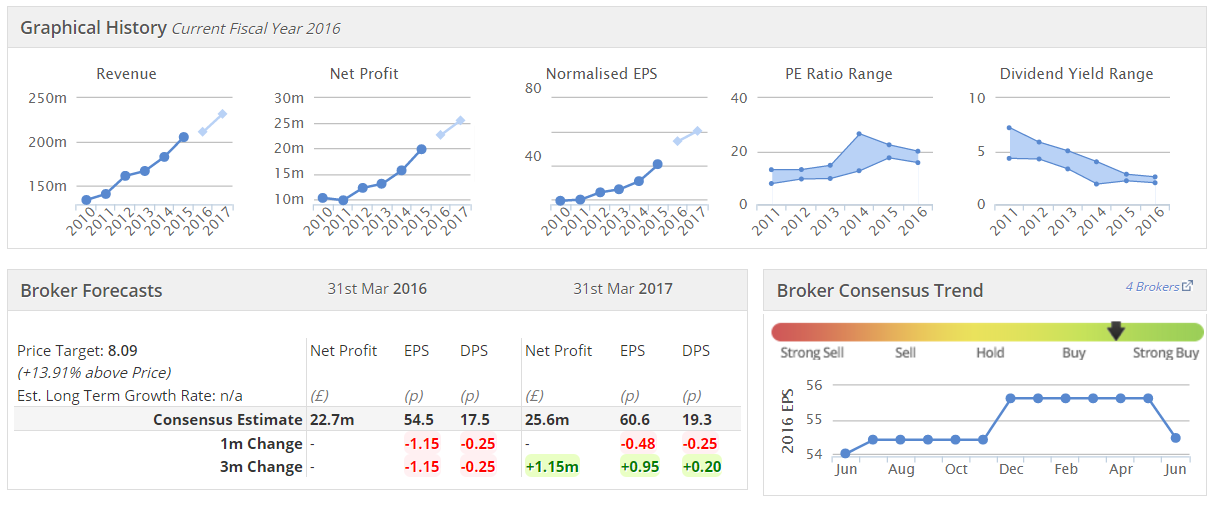
My opinion - I like it. This seems a good quality, well-managed business, whose shares seem priced reasonably. It's showing a very nice progression in key metrics:
Belvoir Lettings (LON:BLV)
Share price: 124p (up 6% today)
No. shares: 31.4m
Market cap: £38.9m
Proposed placing & acquisition - it's getting busy for deals at the moment, in small caps. Cantors has executed what I consider a good Placing here, judging it on these key factors:
- Most importantly, the price discount was modest, at only 4.3% (Placing done at 112p, compared with 117p last night)
- There is little dilution to existing holders, at only 2.2m new shares
- The purpose of the funds is positive - to part-fund a sensible-looking acquisition.
My only reservations are that:
- Bank debt is funding £6m of the initial £8m consideration - this perhaps is a bit too much debt?
- At 8 times EBITDA, the acquisition doesn't exactly look a particular bargain.
- The earn-out heavily incentivises management to make a frantic dash for profits growth in the next 2 years, which may lead to some corners being cut, perhaps?
- Increased bank debt might put the very generous dividend yield at risk, possibly?
My opinion - I like this company, as explained in my report here on 4 Apr 2016.
This looks an interesting deal, to scale up the business a fair bit.
Vianet (LON:VNET) - just a brief comment on its results for y/e 31 Mar 2016.
Overall, the figures look robust. The problem is that the core (beer flow monitoring) business is still declining, in terms of number of installations. The growth part of the business (vending) is probably too small to move the dial much, although number of installations has risen an impressive amount.
The balance sheet looks much improved, following the sale of the fuel business.
Dividend maintained at 5.7p, so a decent yield, shored up by a stronger cash position.
Overall, I feel the limited growth potential makes this share of limited attraction. Although long term holders have enjoyed a flow of nice divis.
That's me done for today!
The washing machine has just been repaired, and Hive is installed, so a very productive morning for me, writing this report and supervising various workmen! We even had the Jehovah's Witnesses call round too!!!
See you tomorrow.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
Boohoo trading update:
Highlights for the three months ended 31 May 2016
· Revenue up 41% (42% CER)
· Strong UK performance supported by third party sales
· Retail gross margin 57.6%, down 300 bps on prior year, driven by planned investments in price and customer proposition
· Marketing expenditure reduced as a percentage of sales, offsetting retail margin decline
· Overall gross margin 56%
· 4.2 million active customers, up 30% on prior year
· £61m cash on balance sheet
I think Boohoo.Com (LON:BOO) is about where it will be in 3 to 5 years not tomorrow after a trading update and the management seem to know what they are doing and know their market and how to execute. I am reminded of Paul's comments about £ASOS being expensive at 27p all they way up to 7,000p. I am not sure what Boohoo.Com (LON:BOO) 's addressable market (sales) is but it must be in the billions and last reported turnover was £200m so it is a relative minnow. I am certainly prepared to wait this one out and see where the mkt takes it.
As for Questor's opinion, if it was that easy all we would have to do is spend a couple of quid each week on the Telegraph and sit back watch the profits roll in - oh that it was so easy.
Proactis Proactis Holdings (LON:PHD) announced a partnership agreement with P&O Ferries today which seems to have been well received by the market, shares up 7% or so.
With regards to Boohoo Boohoo.Com (LON:BOO), the Questor column in the Telegraph tipped it as "avoid" back in January http://www.telegraph.co.uk/finance/markets/questor/12098144/Questor-share-tip-Beware-the-siren-call-of-Boohoos-sales-figures.html It'll be interesting to see how it plays out over the next year or two given the differing opinions on this one.
[I have a small long position in Proactis, I have no position in Boohoo]
Since January Boohoo.Com (LON:BOO) has gone up about 50%.
Having read Questor's insight into Boohoo, I doubt they'd be a fan of Amazon (AMZN) either.
Yes Boohoo.Com (LON:BOO) share price maybe getting a bit ahead of itself, we will see what the update brings, looking for about 28% increase in EPS for this year, compared to ASOS (LON:ASC), who are nearest rival, they still look reasonable value and they do have a lot of cash. I'm a holder by the way. Ken you want to look at the high flyers screen.
Ah, such cool headed logic Ken. While I still don't get on well with charts per se, i do find the momentum rank here on Stockopedia very useful. Even if value looks super expensive, momentum can take a share price a long way - it's the getting out at the right time bit that I struggle with.
I've no position in Boohoo.Com (LON:BOO) as it's always seemed too expensive but fair play to those who caught the momentum on the way up, so far.
Boohoo
I am writing this in the evening prior to the trading update. I have been looking at some of your long positions Paul and just cant see why you are holding them, but then I am no wizard with accounts having had the simple philosophy of " how much gross" what's left as net and how much cash have we got. Finally how long will the cash last if everything goes wrong. Looking at BOOHOO everything seems good except the share price and IMHO the figures will have to be spectacular tomorrow for the price to hold up. Not long to go to find out.
Don't put your fingers in the Hive Paul you may get stung.
Roy
Thanks Paul
Paul
Great write up (as always) and just to comment that Hive is great. Make sure that you have the app on your phone, and you can do clever things like turn the heating on before you get home
Nico
James
Many thanks. I was checking RNS. Was surprised Stockopedia did not have an entry in the Event section of portfolio list.
Roy
iomart (LON:IOM) results are out today, look quite disappointing to me only up 14% EPS but there are a lot of adjustments, was expecting +64% nEPS on Stockopedia but the market seems to like them, +2.7%, so what am I missing?
Hi Paul
Re Q1 trading update. Where has this been quoted only there is nothing that I could find on Stocko (under Events except 24 June Annual Meeting) or Company website?
Roy
Roy,
It's on the company website under the financial calendar:
http://www.boohooplc.com/investor-relations/financ...
James
Hi Randv,
Re Boohoo.Com (LON:BOO) Q1 update, scheduled for tomorrow morning.
I got an email from one of the company's advisers today, alerting me to it, so thought I would pass it on to readers here.
I think the email might have been from the email alert service on their website. It's always worth signing up for those, for companies of interest, I find, as its easy to miss things otherwise.
Regards, Paul.
Just tell them that you have been "disfellowshipped":
http://www.jwfacts.com/watchtower/disfellowship-sh...
They'll run away so quickly they'll leave skidmarks on your doorstep. :-)
Hi Paul assume you approve of £IGR's refinancing just anounced? Market reaction is certainly positive.
Hi FREng
I hold VP (LON:VP.) and like its business modell, as they put it:
"Vp is a specialist rental business
Our objective is to deliver sustainable, quality returns on behalf of our shareholders by providing products and services to a diverse range of end markets including rail, transmission, water, civil engineering, construction, house building, oil and gas. The Group comprises six specialist market leading divisions with operations in the UK and overseas."
On cashflow, the hire business model is a bit odd in the sense that as the business expands in the good times it consumes cash as the hire fleet expands as it is only part funded, when Mgt see the future more darkly they take the foot off the CAPex throttle and the resulting defleeting throws off cash . YE 2013 the net book value of Plant was £99m, 2014 it rose to £113m and last year it was £132m. What I like at VP is the family business attitude that means mgt are very conservative in setting residuals and estimated operational lives for assets that they are in most cases the market leader in managing/owning.
Where hire companies fall apart is being overly aggressive in growing the business by underestimating plant costs to support unsustainable hire rates , the track record of VP is very clear and creditable in this regard imho
Thanks, rhombold, that makes more sense of the figures.
Post script on Belvoir Lettings (LON:BLV). Don't forget a dividend yield of near 6%
Re. Belvoir Lettings (LON:BLV) I analysed the bones of this acquisition this morning and liked it. Took a holding first thing.
My understanding is that it is the Total Consideration (£22m) that is 8x EBITDA. Actually they are putting £11.5m up front and the rest has a 2 yr earn-out period. EBITDA comes to 22/8= 2.75m
So depending on how you see it, at best the EBITDA multiple based on £11.5m comes to 11.5/ 2.75 = 4.2. This multiple is a lot more attractive.
How long can VP (LON:VP.) continue with increasingly negative free cash flow before it needs to raise more equity?