Small Cap Value Report (7 Sep 2015) - BRY, AVAP

Good morning!
It's a public holiday in the USA today apparently, so their market will not open. This is likely to mean a quieter day here in the UK.
Brady (LON:BRY)
Share price: 98.5p
No. shares: 83.3m
Market cap: £82.1m
Interim results to 30 Jun 2015 - this software company has a tendency to give an upbeat commentary with poor figures, and that's certainly the case today. Really upbeat narrative, but the figures are not very good at all.
Revenue fell nearly 10% in H1 to £14.1m, and recorded a pre-tax loss of £389k (vs. £1.4m profit in H1 of 2014). The company blames reduced turnover on forex movements, and "the timing of licence sales".
The narrative says that these results are "in line with market expectations for the full year", which will require a dramatically better H2 performance, since the market is expecting a full year profit of £4.7m, meaning that H2 will need to deliver over £5m in profit, which looks a tall order to me. Although the company says;
Anticipated strong performance for H2 2015 with visibility on 80% of revenues for the full year.
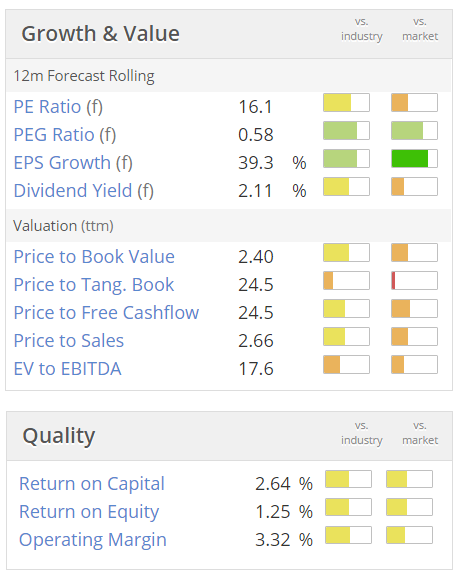
Valuation - the StockRank is 76 - so upper medium.
It's looking fully valued on most metrics below;
Balance sheet - reasonably good. The net cash of £6.2m is mostly money received up-front from customers, as is often the case with software companies.
Note there is a pension deficit of £2.4m, which has risen from £0.9m a year earlier.
My opinion - there's lots of positive-sounding stuff in the narrative, about new contracts, etc., but the H1 figures look disappointing. So personally I would be very cautious about wanting to buy shares at an £82.1m market cap, when it has just reported a loss for H1.
Companies which need to strongly out-perform in H2 to hit their full year forecasts very often struggle to do so. Therefore I suspect there is an elevated risk of a profit warning here if they don't manage to deliver the anticipated strong H2.I'll check out the full year figures when they are published in the Spring of 2016, but for me anyway, risk:reward doesn't look attractive right now.
Another issue to consider is that Brady has a strong focus on energy & commodity markets. So they could at some point possibly suffer fall-out from the chaos in that sector. Maybe that is the underlying reason for poor H1 numbers?
Acquisition - in a separate RNS today, Brady says it has acquired a product called "ScrapRunner", which is software for the recycling sector.
Whilst small, this looks a cracking deal. The price being paid is $2m, and ScrapRunner has (unaudited) 2014 figures of $2m revenue, and $694k profit before tax. 62% of revenues are recurring. So bolting on this cheap acquisition should be nicely earnings enhancing for Brady, assuming that this level of profit is sustainable.
Avation (LON:AVAP)
Share price: 120p
No. shares: 55.2m
Market cap: £66.2m
(at the time of writing, I hold a long position in this share)
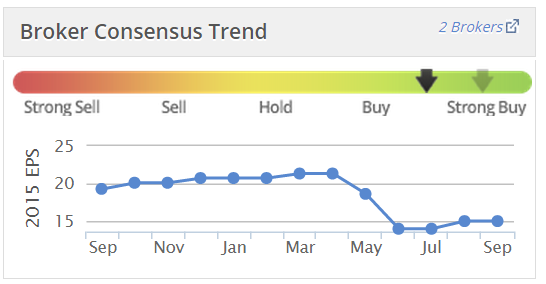
Results y/e 30 Jun 2015 - I can't fathom why it is that the stock market doesn't seem to like this aircraft leasing company. Although Stockopedia's neat little graphic on broker consensus shows that earnings forecasts were marked down significantly in May & Jun 2015:
The company reports in US$, so it has today announced basic EPS of 24.1c, or 26.3c if you only look at continuing operations (which is the figure I prefer to use for valuation). Converting into sterling at $1.526, that equates to 17.2p EPS from continuing ops. That means the PER is only 7.0, which looks strikingly good value. Although at a time of near-zero base rates, I would expect leasing companies to be doing well, so a low PER is probably justified. Maybe not this low though?
It looks like a beat against expectations, as Stockopedia has 23c as the current broker consensus for y/e 30 Jun 2015. I'm surprised that the share price has dropped slightly this morning, given that it looks like an earnings beat.
Loss on disposal of aircraft - last year benefited from a $3.3m profit on disposal of aircraft (a good sign, as it implies that the depreciation policy is conservative), which became a $0.7m loss this time. So a $4m negative impact there, which explains why operating profit was similar to last year ($33.6m this time, versus $33.9m last time).
Interest cost - being a leasing company, there's obviously a lot of debt, hence a big net interest charge of $18.1m (up from $16.6m last year). A couple of points on this. Firstly, the net interest charge is almost twice covered by operating profit. That looks good to me - it says that the company is making a decent profit margin over its cost of funds.
The weighted average cost of funds is 5.1%, so this implies that the interest cost would have to rise to almost 10% before profits were wiped out. If you check the last Annual Report, the company locks in interest rates for periods that match the aircraft leases, which should de-risk things considerably, and seems an intelligent strategy.
Secondly, there has been a bit of a drag on interest costs this time because Avation raised $100m in a bond issue in May 2015. Those funds have not yet been deployed, so there's a short term impact from costs not having any related revenue yet. That isn't a worry, as it will be fixed once new aircraft are bought & leased out to airlines.
Taxation - note that the tax rate is low because the company is based in Singapore, so enjoys a 10% tax rate, from memory.
Dividends - there's a chunky increase in the payout, up 49% to 3c for the year, so about 2p, for a yield of 1.7%. Not madly exciting, but at least the trajectory is sharply upwards. Avation is growing rapidly, so I wouldn't expect big divis at this stage, hopefully that will come a few years down the line when growth tails off.
Balance sheet - net assets are $128.2m, with only $2.4m of goodwill to write off, so net tangible assets drops out at $125.8m, or £82.4m. Note that the market cap is less than NTAV, at £66.2m, which seems a harsh valuation. I would have thought the shares should be valued at least at NTAV, of 149p per share, with possibly a premium justified, given that the company is decently profitable?
As you would expect, the balance sheet is dominated by enormous fixed assets (the planes), and enormous debt. Avation makes its money by charging airlines more than its own cost of funds. Providing the depreciation policy is correct, and book values of the planes are realistic compared with disposal value, then everything should be fine.
My opinion - airline leasing companies get into trouble in recessions, when their customers can go bust, and planes bounce back onto the leasing company, which then can't find a new lessee. If that happens at the same time as the bank pulling in their loans, then it's curtains.
From several chats with the CFO of Avation (who turns up at nearly all investor events!), management are experienced in the sector, seem to have anticipated and structured the company to manage the sector risks, and the Chairman in particular has a large personal shareholding of 18.5%.
So I'm a little baffled as to why the stock market has rated this company well below NTAV, and on a PER of only 7. I would have thought there's good upside on this price. You do wonder though if the market knows something we don't? Could there be problems lurking, or maybe there are some particularly lucrative leases which won't be renewed? (I do recall mention being made of some Australian leases of old planes, which were very profitable, but may be coming to an end because of the commodities situation).
Management have to manage risk as their primary objective here. So far anyway, they seem to be doing a good job of that. So I quite like this share at the current 120p share price, and see some upside on that potentially.
The company is expanding quite rapidly, with 10 more planes coming on stream in the current financial year.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Here's a report from Beaufort Securities on AVAP:
http://www.beaufortsecurities.com/img/pdfs/research/avation100915.pdf
It's a bit sloppy in the notes on page 4, where they seem to be laying stress on "Asia"
as a market when it's Asia-Pacific and principally Australia where the greatest amount
of business in that region actually is. Apart from that, they summarise the
investment case fairly well, imo.
Re. Avation (LON:AVAP). I have been a holder of this stock since Oct last after reading Mark Slater's piece in This is Money:
http://www.thisismoney.co.uk/money/investing/artic...
He pointed out many of the attractions that Paul and others have discussed here, and in addition talked about the stock being a takeover candidate.
The sp has done its gyrations since and has landed more or less at the price I paid. The investment case is as strong as it was then, so I will continue to hold for the medium term.
Regards, Ram
Ramridge,
He pointed out many of the attractions that Paul and others have discussed here, and in addition talked about the stock being a takeover candidate.
Of all the things going for Avation any potential takeover is way down the list of reasons that I hold. IMO I think this is being a bit overplayed, particularly of late as a result of the Avolon takeover.
Avolon was only IPO'ed last December and was already a much bigger player than Avation with about 250 aircraft and now with a $2.6bn market cap, so about 10x bigger all round. Avation is a real tiddler in terms of leasing companies and it's difficult to see why one of the bigger players who have ready access to capital and aircraft would take it out at this point. That's not to say it would not look a bit tastier once it has fully deployed the proceeds of the bond in a couple of years time. Having said that I'd take 200p now ;-)
All the best, Si
Simoan - Re. Avation (LON:AVAP) The aircraft / airline sector is not my patch but going by Mark Slater's view in October last, AVAP needs to scale up to at least 100 planes before it can be seriously considered as a takeover candidate.
Well, the number of aircraft it owned last year were 25, and in the latest interim report in June 2015, the fleet is said to number 29. Hardly a racy growth rate to a 100. So yes I agree with you that today the company's takeover potential is remote to say the least.
ps. A bit of trivia. Reading the interim results, it mentions several times "the number of aircraft". I thought it was a typo and that it should read "the number of aircrafts". However after googling, it appears that both forms are correct. The plural of aircraft can be aircraft or aircrafts. One to add to my list of useless knowledge.
I don't know whether it holds back investment in Avation (which I hold) but I have wondered about the relationship with its 96.6%owned but separately quoted subsidiary Capital Lease Aviation.
CLA appears to be continuing its own parallel plans for leasing and, peculiarly, has a Stockrank of 87 against its parents 34.
Does anyone understand what role this company plays in the group, why it maintains a separate quote and why all business does not run through the favourable tax regime of the parents Singapore residence. From a governance point of view I also get a bit concerned about how expenses get shared in these instances.
A lack of exposure to PI's isn't a problem AVAP has as they present at every show and seminar going.
"A lack of exposure to PI's isn't a problem AVAP has as they present at every show and seminar going."
………
Isn't that a red flag?
I've yet to do proper research but Avation sounds like it could be another Fairpoint where a company has changed the focus of its business and the investment community is yet to catch up.
My own reservation in investing in a company like this is that it has high net debt (for the reasons Paul explains) so I wonder if that results in depressed valuations for the sector? Interesting to see that it seems to be priced below other similar companies though.
Hi Paul
Did you finish that book and is it worth buying?
Cheers
Re AVAP, Im as surprised as you are Paul at the market valuation.
Additionally, the report says that they already have customers for 8 out of the 10 aircraft to be bou8ght this next year. So they are not going to be sticking around.
Brian, where did your friend get that from?
The Stockopedia figures show:
Price to Book Value 0.86
Price to Tang. Book 0.88
PS: Brian, sorry, I now see you were referring to Avolon.
Wow, a 70% premium, even better.
Jane,
I assume Brian was referring the the PTTBof Avolon being at a premium, not AVAP. From memory the recent bid for Avolon assumed a PTTB of ~1.5.
I have been building a bit of a holding over the past week or so and like you have found no nasties whilst doing my research. I agree the price weakness is down to misconception and general lack of interest with bored PI's dumping the shares in the recent market turmoil as it's been on low volume. Like Paul, I have no idea why the share price at such a discount to book and can easily see it back at 150p in the next twelve months.
Si
Jane, I had also thought the Avolon premium to NAV wasn't so high, but then it was pointed out to me by another AVAP holder that the premium to NAV was closer to 70%.
Avation (LON:AVAP) I do not have easily accessible data for US companies but using Google Finance the following similar companies sport P/E's as below:
AerCap Holdings N.V.(NYSE:AER) P/E 7.0
Fly Leasing Ltd(ADR)(NYSE:FLY) P/E n/a
Air Lease Corp(NYSE:AL) P/E 14.6
Aircastle Limited(NYSE:AYR) P/E 9.4
So AVAP are in the 'ballpark'. However if anyone could dig out the P/NTAV's of the above that may prove useful
Paul, thank you for your write-up on AVAP.
The exposure to the commodities business is from the very start of the business when they took on leases for small Fokker aircraft operated by SkyWest and serving mining routes in Western Australia. The business has now grown so much in other directions that the WA business now represents only a very minor part of revenues.
AVAP's main customer in Australia is Virgin Australia, mainly for their routes on the Eastern seaboard, in NSW, Victoria, Queensland and South Australia, using ATR72 aircraft.
AVAP is expanding fast into an international lessor, now with Thomas Cook, Flybe, Air France and Air India Regional as clients. increasingly leasing Airbus planes rather than the ATR72.
I've really spent ages going into this company and have asked quite a few questions of both the Chairman and the CFO. They seem to be very open and I have found no skeletons. To me, it seems like one of those companies simply overlooked, perhaps with a legacy perception (just as it stuck in your mind about the WA/commodities exposure) that is out of date and which the market will wake up to.
An SP some 12% below Tangible Nett Book Value gives an additional safety margin, imo. Avolon, a bigger aircraft lessor based in Ireland, has just been taken over at about 25% above TNBV and aircraft lessors probably do have attractions as fairly secure good-yield investments in this era of yields elsewhere that are close to zero, for pension and insurance funds and the like.
All IMHO, DYOR.
Best wishes,
Jane.
Tracsis (LON:TRCS) have announced a small acquisition today, which made me take a look at them. They are in the (currently) sexy business of data analytics for the transport and smart cities sector and profitable, with a reasonable free cash flow. I liked what I saw and bought some.
Hi Paul
I'd be interested to get your thoughts about Avation (LON:AVAP) who published results this morning.
Best wishes,
Imran.
Morning Imran!
I'm working on Avation (LON:AVAP) right now, so that will be up shortly.
Regards, Paul.
Thanks Paul. I think its a real marmite stock, especially amongst the private investor community. I first came across them at Mello 2014 in Derby last year. The share price performance since then has been disappointing, but I think the growth should come through over the next year. As always I look forward to getting your take on the results.
Best wishes,
Imran.