Small Cap Value Report (8 Dec 2015) - ZYT, VLK, UTW, PLUS

Good morning!
In case you missed it, I did a report yesterday evening, the link is here.
There seem to be some tremendously volatile price movements going on at the moment. I see that Plus500 (LON:PLUS) has had a huge bounce, and amazingly it rose to higher than the 400p failed cash bid.
On the downside, I see that controversial company Utilitywise (LON:UTW) has really fallen out of bed, and fallen from 200p to 120p. Thank goodness I got cold feet a day or two after results, and ditched mine. It's tempting to catch the falling knife, but that's not worked out well recently, as I can attest, with £DX. having failed to bounce significantly since its disastrous profit warning.
So very much a time for caution. I'm going to review all my positions tonight, and chuck out anything that I don't have proper conviction over, apart from short term trades, which are a different kettle of fish.
Companies that are delivering good trading results are going to new highs though, so it seems to be becoming a highly polarised market, where the wobbly stuff is thrown away (good shorting opportunities should therefore abound), and the decent stuff keeps going up. So very tricky for us as investors to handle. Arguably we need to be reckless with good companies (running them to over-valuations, which is what's working best at the moment), and ruthless with bad companies, chucking them out even if they appear cheap.
Zytronic (LON:ZYT)
Share price: 397p (up 0.8% today)
No. shares: 15.3m
Market cap: £60.7m
(at the time of writing, I hold a long position in this share)
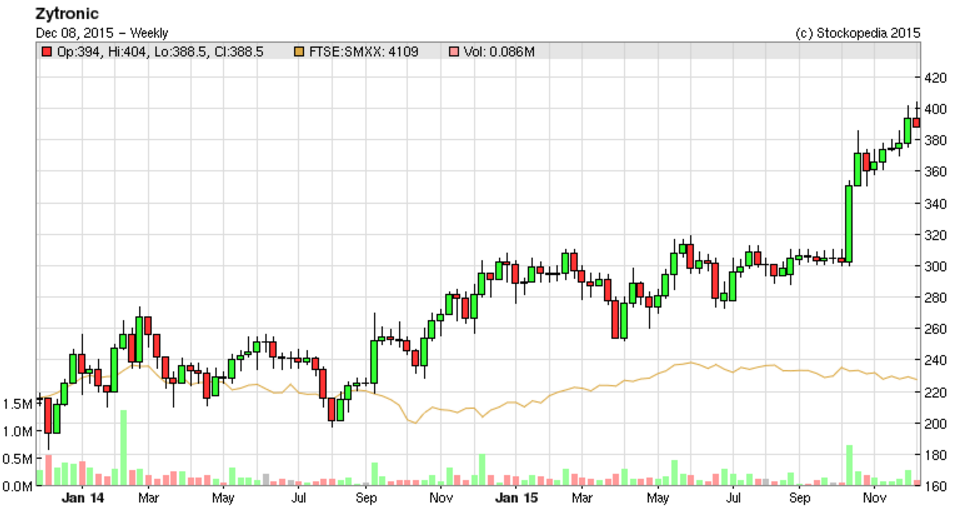
Results y/e 30 Sep 2015 - excellent results today from this bespoke touch screen manufacturer. The share price is only up slightly today because the market had already factored in strong results, since the company put out a "materially ahead of market expectations" trading update on 15 Oct 2015, which I reported on here.
What's particularly interesting, is that you could have grabbed two thirds of the move from 300p to 397p by buying on the day of that trading update. It just shows, that often it's the early bird which catches the worms.
I've noticed this happening with some other shares too - i.e. the initial move up on the day of an out-perform trading update can very often be the precursor to a bigger move up. That makes sense really - private investors can swoop immediately, and grab the worms, whereas Institutions have to sit patiently and accumulate shares in the market over a long period. Also, Instis might take a little while to have meetings to get purchases discussed & agreed, whereas again PIs have the advantage in that we can buy on the opening bell for our own portfolios.
Key figures from the Zytronic results for y/e 30 Sep 2015 are;
- Sales up 13% to £21.3m (in line with the 15 Oct trading update)
- Gross margin particularly strong, rising from 36.6% to 41.9%
- Profit before tax up 39% to £4.5m
- Diluted EPS up 24.6% to 24.3p (giving a PER of 16.3)
- The year's divis are up 20% to 12.0p (giving a yield of 3.0%)
- Net cash on the balance sheet rose to £9.8m, or 64p per share, clearly material to the valuation.
Also, these are some of the cleanest figures you'll see - no adjustments, or other silliness, just real profits that turn into cash. This matters because it gives confidence in applying a multiple to earnings, to value the company conservatively. Whereas, with some other companies, you can end up over-valuing the shares, if you put a multiple onto artificially inflated earnings figures.
Note that the % rise in EPS is lower than the % rise in profits because the tax charge has normalised this year - last year it was unusually low, due to releasing previous year's over-provisions - itself a good sign, in that the accounting is clearly being done conservatively.
Cashflow - looks absolutely clean to me. Note that only £388k was capitalised into intangible assets, which is close to the amortisation charge of £336k, so there is only minimal overall effect on profits.
Balance sheet - absolutely lovely. As already mentioned, the company has £9.8m in cash. There is a mortgage of £1.3m, but I tend to ignore this, as it's property asset backed.
Note also that debtors, inventories, and trade creditors are all modest - demonstrating good financial controls.
Outlook - sounds fine to me;
The year has started positively with maintained momentum and a continued drive to develop product functionality and expand the global sales footprint. We continue the focus on increasing shareholder value and shall update shareholders on progress and material developments during the course of the coming year.
I'm not sure what the focus on shareholder value means? Perhaps we might get a special divi at some point?
Valuation - I think you can safely take off the 64p per share net cash, as effectively being surplus capital. That takes the EV to 333p. At that level the PER would be only 13.7, which strikes me as a bargain in the current market.
My opinion - this is one of my favourite Value/GARP companies. It has high quality scores, a bulletproof balance sheet, a decent & growing divi yield, is on a reasonable/cheap valuation, has excellent management, growing markets, the list of positives ticks nearly all the boxes for things I like to see at a company.
As we know, the downside risk is that gaps can appear in the order book, as visibility is limited. That's a risk that shareholders just have to live with. It also provides excellent occasional buying opportunities when the price does plummet on profit warnings, but that's pretty rare in fairness.
Stockopedia likes it too, the StockRank is 96.
I've only looked at the (now) historic figures above too. Broker forecast is quite modest, but the upside case is that the larger touch screens the company is concentrating on could become much more popular, leading to earnings rising more rapidly than brokers currently anticipate.
Overall then, I am very pleased with progress, and will continue to hold for the foreseeable future. The shares look excellent value, for a smaller growth company that is firing on all cylinders, in my view.
I've not gone through all the narrative yet, but being very happy with the numbers, I often park the more detailed reading until the weekend.
Vislink (LON:VLK)
Share price: 28.35p (down 2.2% today)
No. shares: 122.6m
Market cap: £34.8m
Trading update - there's quite a bit of information in this update, and it's open to interpretation. The way I read it, the company seems to be saying that it could struggle to close some sales deals by the 31 Dec year end. A range of £54-58m is given for anticipated turnover for calendar 2015.
That constitutes a profit warning in my book, as brokers consensus is currently for £60.3m turnover, and £6.05m profit - although Vislink is prone to accounting adjustments, so whether that profit figure can be relied upon is questionable.
The bank facility has been increased from £10m to £15m, which the company blames on working capital requirements which should unwind in 2016. A small bolt-on acquisition is at the "advanced discussions" stage.
Positive noises are made about new product launches, and cost savings made which will benefit 2016 and beyond.
My opinion - I think they've done a great job in disguising a profit warning as positive potential for next year!
For me this share is uninvestable under the current leadership, due to excessive board room greed, with ridiculous remuneration for the Chairman in particular, and the last straw being the ill-considered "Value Creation Plan", which has coincided with remarkable value destruction in the share price, as shareholders voted with their feet, and sold out.
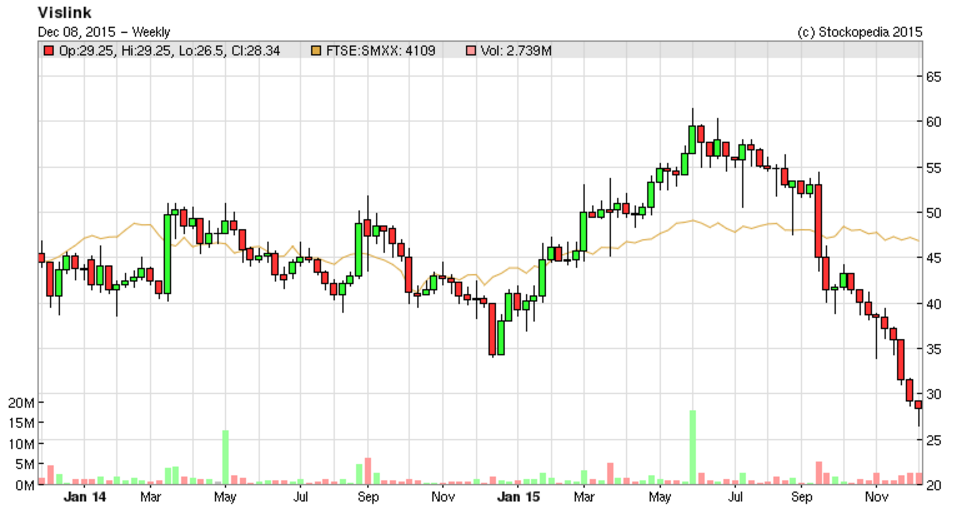
It sounds as if the core business isn't trading very well either. Although people who want to look for positives can find plenty of upbeat messages in today's update.
The Chairman has a track record of repeated wheeler-dealing, almost an addiction to making acquisitions. The trouble with this, is that it strips the balance sheet bare - you end up with mounting intangibles (often of little to no real value), and rising bank debt.
I don't like this type of growth by acquisition financial engineering, as it usually goes badly wrong in the end. The contrast between Zytronic & Vislink couldn't be more stark - the former has solid, modestly remunerated management, who get on with the job & deliver excellent results, with real profits & cashflow. The latter are always doing deals, and trying to concoct artificial, but probably only temporary shareholder value, in order to trigger massive personal gain from convoluted bonus/options schemes.
It's very clear to me which one is attractive, and which one is best deflected with a bargepole.
That's probably all I'll have time for today, as hospital visiting beckons for this afternoon & evening.
I see that Ensor Holdings (LON:ESR) has dropped a lot on publication of interim results, so if I get a chance might circle back to that one.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
Hi Paul,
You have commented on TET before. Recent results look solid, but there still seems to be a £20million cap ex plus contingencies for a new headquarters on the cards. Can't decide whether this is a good or a bad thing.
Slight previous year weakness cleared up and a potential craft beer market in the US looks promising.
apad
The spread is usually wider in early trading. I think its quite hard to judge which way the market will go on announcements, I'm often surprised on good results that the share goes down, even if it is better than expected.
"I've not gone through all the narrative yet, but being very happy with the numbers, I often park the more detailed reading until the weekend."
Music to this accountant's ears. Forget the fancy visuals, colourful graphs and verbose hyperbole. Let me see the numbers.
Paul,
My reading of the Vislink trading update at 7pm this morning was exactly as yours i.e. a profits warning in my view. I have not held the shares since some time in 2013 when I made a reasonable return on them exiting on a trailing stop loss; never really tempted back. Since that time I have kept a passing eye on them but for me they are on my bargepole list.
Paul
I have held shares in VLK for a long time (since the Silvermines days) and the share price is now below what it was 16 years ago. I have been trying to speak to the FD since last week and was promised a call this afternoon. All I got was a call from his secretary to ask if I had seen the trading update and did that address the reasons I was trying to speak to the FD - the answer was that it did not and that I was very concerned by the fall in price since the announcement of the value creation plan (that had not been put before shareholders). I said that I would still like the FD to call me, but am far from optimistic that this will happen.
.
I ditched Vislink after the announcement of the laughably titled "Value Creation Plan" and following talking to an old friend who knew Hawkins from his Anite days. We had quite a significant holding - now they are firmly on my bargepole list.
Overly greedy management are now one of my key reasons not to buy / to sell - VLK, EGS, MSI are recent cases.
One issue that's rarely mentioned - employees at a company understand austerity when it's seen to be fair. But seeing management gorging themselves is a sure fire way to a disgruntled workforce - which will perform under par.
Garbetkld
I think your points are very fair.
I have no issue with share option type arrangements as long as they are targeted at and incentivise the right people - namely those who can grow the business and create significant value.
I had an investment in Anite but am not sure whether it was when Hawkins was there. It was a disaster when a falling share price meant that more and more shares had to be set aside for deferred consideration on acquisition earn out's. A vicious circle ensued that decimated the share price and left the company on the verge of bankruptcy.
Graham
Paul, any chance of looking at Servoca (LON:SVCA) interims please.
Hi Paul.
Hope the patient (your mum?) is on the mend.
Regarding buying on the opening bell on the day of an upbeat trading statement, I was led to believe that the market makers often cynically raise the offer price to take advantage of the small investor, pre 9am?
BW
Hi hedley05,
Yes, the market makers do hike the price on positive news, so you might well have to pay more than the previous night's close. However, my point is that when REALLY good news comes out, then often people's anchoring to the previous night's close will mean they miss a bigger opportunity.
So people might baulk at paying 10% more on the open. However, that could turn out to be a real bargain, if the news justifies say a 30% rise in share price. This happened with accesso Technology (LON:ACSO) for example, where I happily paid 600p per share on the day of the Merlin announcement, as I could see that it was a complete game-changer. The price has since risen to 830p.
The vital thing of course is to be well prepared, and knowledgeable about a company ALREADY, so that you can react to significant newsflow quickly, and screen out spurious or rampy newsflow (which you often get from micro caps where they are desperate to pump the share price up in order to get a Placing away).
As with almost everything in life, good results come from thorough preparation!
Regards, Paul.
The vital thing of course is to be well prepared, and knowledgeable about a company ALREADY, so that you can react to significant newsflow quickly
I think this is the key. As an example, having done research on Walker Greenbank I dumped the shares first thing yesterday morning as I knew how close their Standfast & Barracks factory was to the River Lune in Lancaster! It's a good company, but it's on a reasonably rich rating, and there was just too much uncertainty of the effect on profits caused by the awful flooding in that part of the world for my liking.
Just to add my best wishes for your Mum's speedy return to good health, Paul.
Take care, Si
Hi Si,
I disagree with your point about selling a share because you are worried that its factory might flood. Companies have comprehensive insurance, including business interruption, and often natural disasters can turn out to be very lucrative in the overall result.
Look at ASOS - if you had sold on their first factory fire, then you would have missed out on one of the stock market's biggest ever gainers. They also seemed to shrug off the second fire more recently. It's a good way to get rid of dead stock actually.
Look at Pure Wafer (LON:PUR) - their factory burned down, and the insurance claim has ended up giving shareholders a roughly 5-bagger on the pre-fire value of the shares.
So, providing a company has good insurance, then natural (or man-made) disasters can bizarrely turn out to present you with spectacular buying opportunities. Of course if they forget to post the cheque for the insurance premium, then they're skewered.
Regards, Paul.
HI Paul,
FWIW I completely agree with your points! However, WGB was at best a weak hold for me on a forward P/E of 18. Standfast & Barracks is a massive factory that accounts for all of the companies fabric printing for both the in-house brands as well as the higher margin contract manufacturing. Operationally it was the main growth driver in the Manufacturing side and I can imagine it will not be up and running again anytime soon. I think a warehouse fire is entirely different to a factory full of state-of-the-art digital printing machines.
To be honest the share price has not sold off that much and so most people are taking your approach. My approach is that you don't have to hold any share when uncertainty increases and I will probably buy back in once the situation becomes clearer which could be at a much lower price.
All the best, Si
The market makers' job is to set the opening spread around the price where they estimate the market will balance. There'd be a stampede on the mispriced side after every significant announcement if they didn't adjust for news... Yes they'll make some money on their overnight stock on positive days, but then they lose on bad news, when (cynically?) no investor will buy at the pre-news price.
Thanks for historical ZYT posts Paul, I bought at 339 (probably higher than some of you) in mid-October and am happy with the rise to-date. I think you are right about the "pre-cursor of a bigger move" idea, I bought Telford Homes just over a week ago after their latest update, the price ticks up a few pence every couple of days, currently up almost 5% since I bought... although housing shares generally seem to be positive after recent news comments.
(Positive comment in Investors Chronicle update too)