Small Cap Value Report (8 Jan 2014) - TRCS, THAL, MTC, IGP, DOTD, IDOX, DIA

Good morning! Tracsis (LON:TRCS) is a growth company that has been mentioned here quite a few times. It offers a range of specialised products to the rail sector, including scheduling software and remote monitoring equipment (to identify faults and wear on things like overhead gantries & points, before they fail). I have previously felt that the valuation got a bit ahead of itself last year, but it is now looking as if the company is growing nicely into the valuation.
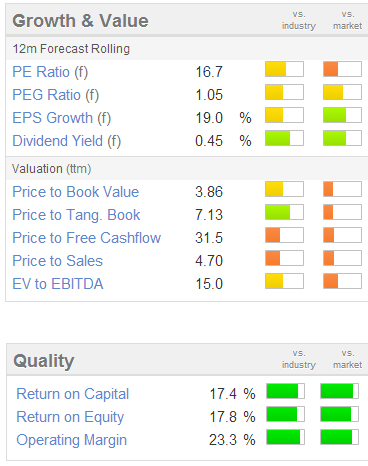
The latest share price of 198p (market cap of £51m) represents a forward PER of 16.7 times, using Stockopedia's usual blend of forecasts, which eliminates differences in year-end dates, making all companies comparable. That's not cheap, but the market likes growth stocks, and tends to put them on higher ratings, and Tracsis has had a very good track record of growth and sensible acquisitions in recent years.
It also has a solid Balance Sheet with net cash. So I like the company, and rate management highly. I also like the way management are very accessible to shareholders, which is important for smaller Listed companies in my view.
Note the strong return on capital & equity bars on right (green is good, red is bad). Being a growth company, the dividend is small.
That said, it's still a small company, with the inherent risk of lumpiness in contracts on the hardware side of the business. Combined with quite a high valuation that makes it a little too high risk for my personal investing taste, but each to their own, and I can certainly see the attraction to more risk tolerant investors than me.
Today brings good news of a significant £2.2m order from an existing client, for remote monitoring equipment. This is an initial order in a five-year framework agreement, so that augurs well for the future. The key sentences say;
An order of this magnitude provides the Group with additional confidence in meeting current market expectations...
Given the magnitude of this order, we believe Tracsis is well placed to win further contracts of this nature both within the UK and overseas.
That sounds pretty bullish to me, so I wouldn't be surprised to see these shares take another leg up.
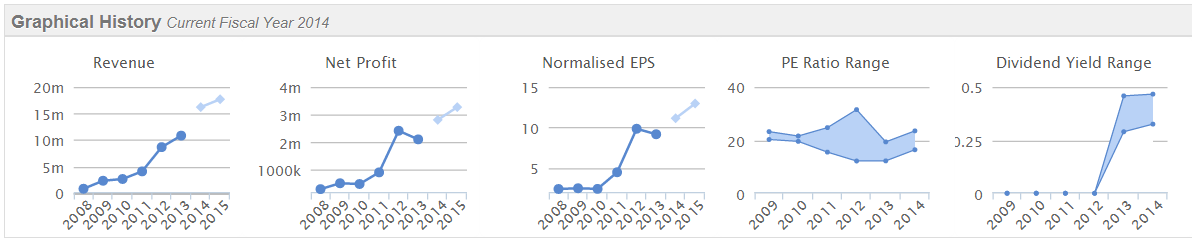
The good track record of Tracsis is demonstrated well by the Stockopedia graphical history below (I'm a big fan of these graphs, as so much can be gleaned in just a few seconds, thinking about what they tell you):
There's a profit beat from Thalassa Hldg (LON:THAL) this morning. These shares have been a remarkable performer, rising almost 6-fold in the last year, from about 50p to 288p. It offers services to the oil & gas sector, which seems to be things like doing seismic surveys, etc.
Their trading update covering the year ended 31 Dec 2013 says that turnover will be in line, operating profit will be 10% ahead, and EPS will be more than 20% ahead of market expectations. I like the way they have quantified their profit beat, which is very good practice, and allows investors to make better informed decisions. Whereas if they had just said "significantly exceed market expectations", then the market might have gone crazy and assumed profits might beat forecasts by say 50%. Communication is so important, and the golden rule is the more specific, the better. So this statement passes the clarity test with flying colours.
Here is Thalassa's spectacular two year share price chart:
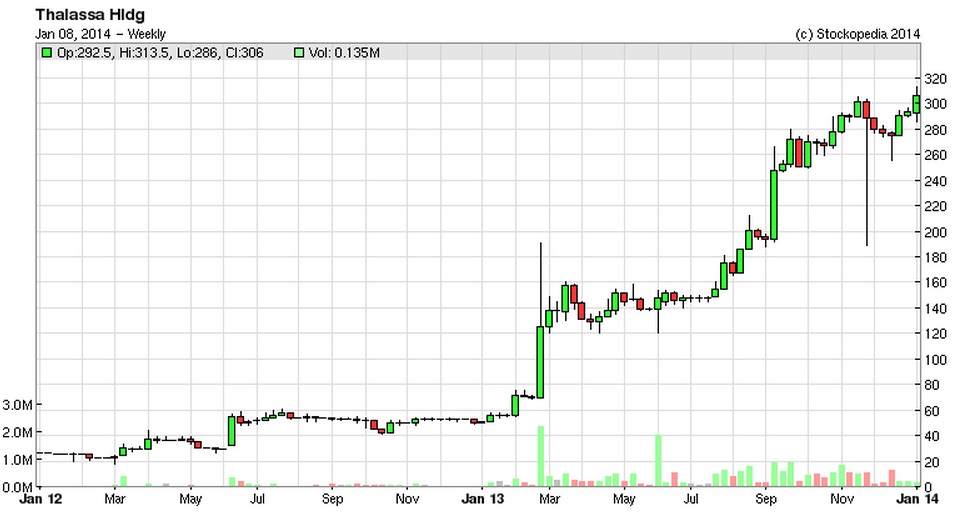
The market likes this announcement from Thalassa, as you would expect, with the price up about 10% to 315p at the time of writing. With just under 24m shares in issue (net of shares held in Treasury) that equates to a market cap of £75.6m. That looks pretty racy on the historic figures, but it's all about growth. So looking at forecasts, and remember to convert their reported US$ figures into sterling, the calendar 2013 EPS broker consensus forecast is shown as about 11.5p, so they are 20% ahead, which means they'e achieved about 13.8p in 2013.
So at 315p per share, the PER is a lofty 22.8. You would need to feel pretty confident that more strong growth was in the pipeline to be comfortable with that valuation. There's no dividend either. Although there does seem to be plenty of cash, especially after an £18.1m Placing in Oct 2013. So that could well be the key to the valuation - i.e. investors are factoring in the cash balance, and the upside from it being invested in growth. That makes sense, as the Placing proceeds would not have made much (if any) impact on the 2013 results, but if invested wisely should generate higher earnings in 2014 and beyond.
A little while ago I reported on how John Lee, the FT writer and believed to be Britain's first ISA millionaire, gave a fantastic talk at a Mello investor evening late last year. John's talk was absolutely full of investing wisdom, and I bought a copy of his book, "How to make a million - slowly" at that event, although must confess I've been so busy that haven't started reading it yet.
With that in mind, I spotted an article here on Stockopedia, written by a friend of mine, Boros10 who it turms out is also an ISA millionaire. He's not only a very shrewd investor, but also one of the nicest people I know, and he has explained in meticulous detail how he actually built up his ISA to over £1m in this article.
It's an absolute must-read, with some very important conclusions drawn. In particular he dodged the credit crunch completely by going into cash in March 2008, and his portfolio actually went up that year! This confirms my inkling that the most successful investors I know are people who see trouble ahead and cash-out before the proverbial hits the fan. Not just with the market as a whole, but with individual companies too (a point also covered in this article). Other conclusions are that great progress can be made from compounding, and from keeping losers small, but letting the winners run. Anyway don't let me ruin it for you, as the article from Boros10 explains his approach & his lessons learned far better. It really is essential reading in my view.
There's a profit warning from Mothercare (LON:MTC) this morning. Can't say I'm surprised, as its UK business has been struggling for some time, and the growth from overseas was holding it up. However, my view is that if a business can't make money in its home market, then something is badly wrong.
Their shares have crashed by about 30% this morning to 295p, which values it at about £261m, down from last night's £373m market cap. The 12 weeks to 4 Jan 2014 saw deteriorating trends across the board, with UK LFL sales worsening to -4%. For the full 40 weeks of the year to date, UK LFL sales were -2.3%. That's really bad news, as the problem is that costs are rising, and mainly fixed, so if your sales are falling (and usually that goes in conjunction with lower margins as prices are dropped to clear slow-moving stock), then the operational gearing which we discussed yesterday goes into reverse, and can decimate profits.
The problem here is that there weren't really any profits to start with, and the market cap was hanging on hopes for a recovery which isn't now happening. Therefore in my view things are not looking good for Mothercare. It only made £8.3m underlying profit on £749.4m sales last year (to 30 Mar 2013), so will certainly be loss-making this year, possibly quite badly.
The balance sheet is weak, with negative net tangible assets of £7.7m, since it has net debt and a pension deficit, hence in my view it's difficult to see any reason at all to hold these shares at the current valuation, even after this morning's fall. It could even make a candidate for a short position?
Today's statement concludes;
As a result of lower UK sales and margin and the International currency impact, full year profits are likely to be below the current range of market expectations. We continue to focus on delivering a turnaround in the UK and exploiting the global growth opportunities for Mothercare.
I am surprised they are still talking about profit, as looking at the last 2 sets of results (interims & prelims) it's difficult not to conclude that this year will actually be loss-making, not profitable. I don't see how they could turn a profit this year, given that they were only just above breakeven last year, and LFL sales are down again this year.
International has been impacted by adverse currency movements, and deteriorating underlying sales, but is still growing. Overall, not good, and personally I would definitely not be long of Mothercare.
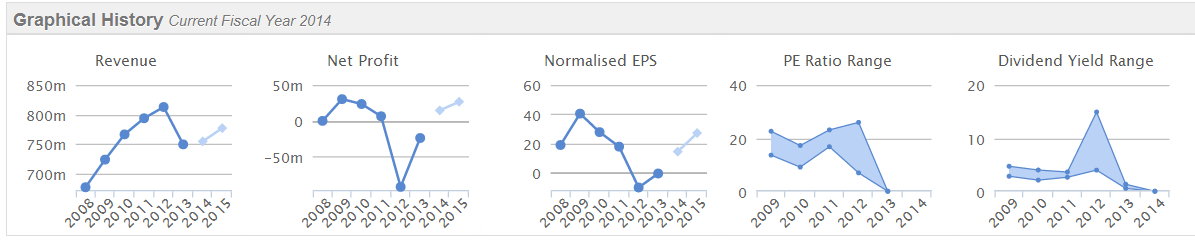
If I'm right that they are now loss-making, then the light blue forecasts on the charts below could lurch down into losses, and create a very ugly trend:
The bullish view on Mothercare is that their heavy losses in the UK will gradually be sorted out, as they close loss-making stores, which is what a lot of the exceptional costs were last year. That's a fair point, but it can be very expensive to get out of loss-making shops (French Connection are facing the same issue). Meanwhile Mothercare's international operations are pretty successful, making good profits. So it's not dissimilar situation to FCCN, where parts of the business are decently profitable, but there is then a large negative value to the problem parts of the business. With International growth now also slowing, then the bull story is much weaker at MTC than it was.
As a general point, prompted by Mothercare, it's worth bearing in mind that because we are currently in an optimistic market that is pricing-in improvements in trading from growth for most companies, then the slightest disappointment will lead to big markdowns in share price. So rather than getting carried away with the excitement of a bull market, I see this as a market that is increasingly becoming littered with banana skins - take one false step and you're flat on your back! Also remember that the mathematics of it mean that a 30% loss on a share requires a 43% gain to recoup your loss. That rapidly becomes more extreme, so a 50% loss requires a 100% gain to get back to even money.
So to my mind, it's a case of being very wary about paying up for a richly valued stock - one really does need to do the research thoroughly, and be as sure as possible that you've got it right. It's only a matter of time before some of the really bonkers valuations out there take a big tumble, so chasing the momentum on wildly over-priced stocks is a very dangerous game to play, as shareholders in Perform (LON:PER) recently discovered.
Intercede (LON:IGP) has issued a bullish-sounding trading update, saying that revenues for the first nine months (it's a 31 Mar year end) have exceeded those achieved last year. So last year they did £6.7m turnover, and made a small loss. So they're on track to do say £9m turnover this year. The market cap is about £75m! Blimey, that's one helluva big valuation, so the market is pricing in a lot of growth & future profits.
There's a good trading update from dotDigital (LON:DOTD), the email marketing software company. I saw management present last year, when the shares were about 15p, and thought it looked interesting, but couldn't quite get comfortable enough to buy. Pity, as they've doubled in price since then, and now sit at just over 30p, so a market cap of about £85m. That might look expensive, but they are growing strongly, and are forecast to make 1.05p EPS this year (ending 30 Jun 2014) and 1.6p the following year, so PERs of about 29 and 18.7 respectively. That's too rich for me, despite the in line with expectations statement today.
I've had a quick skim over the results for the year ended 31 Oct 2013 from Idox (LON:IDOX), and have to say they're not as bad as I expected. Profit before tax (on continuing operations) was slightly down at £7.5m, although they also highlight adjusted profit tax which is much higher at £13.3m (down 10% on the prior year).
The main adjustment is £5.4m in relation to amortisation of intangibles, so this is usually a way of stuffing costs onto the Balance Sheet, as lots of software companies do. However, on closer inspection of the cashflow statement, they only capitalised £1.7m of development costs in the year, so I would be comfortable with adding back amortisation and deducting capitalised development spending, to arrive at £11.2m which is a reasonably conservative way of looking at adjusted profit after expensing all development spend in the year.
The main problem with Idox is its Balance Sheet, which fails my tests. So I would not normally consider this share investable, as it has negative net assets of £24.8m, and too much debt for my liking. That makes it too high risk for me personally. I am tempted to ignore my own rules sometimes, as a lot of highly indebted companies with weak Balance Sheets have made excellent speculations/investments in the last year. On balance though I like to be able to sleep at night, knowing that there is no chance of any 100% losses in my portfolio, so will pass on this one. It is quite tempting to have a small punt on it though.
Dialight (LON:DIA) has warned on profits again. This is another example of a formerly trendy growth stock that has hit the buffers, with disastrous consequences for shareholders. Their shares have halved in just four months from the peak in Sep 2013. On 12 Sep 2013 I commented on Dialight;
"I see that Dialight (LON:DIA) has warned on profits, with the shares down 16% to 1150p. They say that contract delays mean that profits are likely to be "broadly in line with the prior year". It did 41.3p EPS last year, so that means the shares are still far from cheap on a PER of 27.8. That's a seriously racy price for a company that is not showing any profit growth against last year - I'm surprised the shares haven't fallen considerably more, so are not of any interest to me."
That has proven correct, with a disappointing update today indicating underlying profit before tax will be not less than £14.5m for calendar 2013. That looks to be well short of the £18.7m forecast that I've found, although you can never be sure that you're comparing apples with apples with profit figures, but usually most broker notes report underlying profit figures too.
So I think that means they're very roughly heading for about 30p EPS in 2013, well down on the 41.3p last year. Not good. On the other hand, the outlook statement sounds quite positive, saying;
With the Industrial Lighting market remaining buoyant and Dialight continuing to hold its market leading positions, the Board remains confident of delivering renewed profitable growth in 2014 and beyond.
So if you think this is just a glitch, then these shares might be coming into range where they're worth considering. Having said that, even down 201p to 641p today (a fall of 24%), they are still on a PER of 21 times my estimate of 2013 earnings. So it's not exactly a bargain even now, in fact it still looks expensive, if my number-crunching is correct.
Bit of a marathon report today, but there was a lot to cover.
See you from 8 a.m. tomorrow morning.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Okay,Roger,I get that software companies have to be valued at some multiple of revenues,rather than tangible assets,because the intangibles really do have some run-down-value.Where the Micawber in me wakes up and raises a red flag is when those companies go cash-flow negative and start to accumulate debt. .
Hiya All,
Nice little piece from Dillistone (LON:DSG) this morning FYI....
Please find a brief announcement made by Dillistone this morning in respect of their launch of the recently acquired Evolve product into the Australian market and a link to an interview with the CEO on the development - http://www.brrmedia.co.uk/event/119683/jason-starr-group-chief-executive. Importantly, the cost of launching and selling into this market is minimal given the existing infrastructure in place, therefore, the additional income generated will be very high margin revenue.
Best,
Sully.
Roger. IDOX has 69m of intangibles. Take that away from the equity value of 44m gives you a company with negative net assets. Whether you should subtract all intangibles or none is a matter of opinion or judgement.
Re IDOX, you can't value software companies as if they were manufacturing or property companies. They simply don't have any tangible assets and no trade buyer would look at the company in that way.
Paul, Don't really understand your comments on Idox. You say "not as bad as I expected" which is surely damning them with faint praise when they beat analysts forecasts handsomely. As for saying it has negative net assets, that's surely simply wrong, unless you are calculating it in a different way to normal. The figure on the balance sheet is a positive £44,686,000. Of course we could argue about the value of capitalised software development, but apart from cash and trade receivables, what other assets do you think a software company has? And have you ignored the deferred revenue from liabilities which is even less real? Without explanation to tell people it has negative net assets is going to lead them to jump to erroneous conclusions.
Thanks Paul for the useful clarification.
The FD of Tracsis is only in his mid 30s and is on a base salary of £80K - so I agree with Paul - not a hanging offence for him not to own some shares. Conversely though it does irritate me when you see a small cap PLC where the FD is taking out £3-400K and never invests - quite a common phenomenon!
Paul - excellent write up as always. I see that Stockopedia has a forward looking PE for Dialight of 15. Do you not think this is a useful consideration? Regards.
Hi DLG12,
I see that Stockopedia has a forward looking PE for Dialight of 15. Do you not think this is a useful consideration?
Care is needed here - remember that all the Stockopedia ratios are based on the previous day's closing prices. So if a stock has moved a lot in price today, then you need to manually adjust the market cap, and all other ratios.
Also if the price has moved a lot in one day, then that will nearly always be because some news has been issued which has changed the present and/or future profitability of the company. Therefore broker forecasts will need to be adjusted too.
So on major price moves, everything has to either be recalculated manually, or just wait overnight for the Stockopedia figures to be updated, and usually a few days more for revised broker forecasts to feed through.
I usually show my workings in my reports when I'm trying to manually calculate a bang up-to-date valuation of a share after some significant news.
Cheers, Paul.
Paul - just to observe that the Stockopedia fprward PE has now been adjusted to 13.9, so whilst not cheap it does seem to be at a reasonable level?
With Dialight it seems that the profit warning is related to £3million contracts which will fall into 2014 i.e. delays rather than shortfall? There is also an issue with the public sector contract delays and budget tightening is the USA. It seems to be a large fall today based on the fact that these orders will fall into 2014 rather than 2013. I cannot hit the buy button however!
Hi Paul
Re: Dialight (LON:DIA) Do you have an embargo on reporting about the advise you give to Titan on buying shares as well as selling them as was the case with £VLX? I'm genuinely curious. All your reports are very well received and balanced and I look forward to reading your analysis on Dialight (LON:DIA) if you have time. Cheers
Puzzled here - didn't think you were allowed to hold cash for long periods in a shares ISA.Anyone know a link to the rules ?
Alan
As far as I was able to ascertain when I questioned my ISA provider several years ago, you are not "supposed" to hold cash for long, but there are no specific, quantitative rules about it, and it is left to the discretion of the manager. I guess it would be considered too draconian on the part of the government to insist that ISA holders had to suffer a loss because they were not allowed to go liquid when market forces dictated.
I've never had any problem holding cash on my ISA, though my provider, like most, disincentivizes you from holding too much cash for too long by paying virtually no interest on your cash balance.
I also seem to remember that if you did earn more than a very nominal amount of interest you would have to pay income tax on it, since it would fall outside the scope of the ISA regulations.
Ultimately then, you'd best speak to your particular provider.
Kevan
Thanks,Kevan.That has cleared up some questions that I had such as how you were supposed to start a shares ISA if not with cash,and what might happen if you fell ill before having the chance to invest it.
Paul
Interesting comments on Tracsis - they keep securing new rolling contracts that bodes well so can see potential growth but still have some hesitation - did buy on earlier good news update but sold when they seemed stuck around 200p - perhaps too prematurely!
Interested to know if you have had a look at IDOX results - I know you have some reservations about such software companies with high Intangibles on balance sheet but for all of lower profit, seems recnet selling overdone and outlook comments do appear to be indicating return to growth in 2014. Also, do you have a capital limit size for Small Stocks - does Dialight fall outside this range? Interested in any comments on them following recent fall in price and latest trading update, Is this an example of a growth stock where growth stops (perhaps only in short-term) and price slashed accordingly? Still seen as strong buy with covering brokers so could this be a buying opportunity? At about 640p today close to 52 week low of 619p and where high has been over 1400p.
regards
Peter
I'd also like to hear more about Dialight when convenient Paul.
Many thanks for the constant stream of highly valuable and insightful comment.
Paul, any comments on PURI today?
Paul thanks for another excellent write up. And also thanks for the recommendation for the Boros10 article which I found outstanding!
Hi Paul,
Have been receiving your daily reports for some time now and find them invaluable; please keep up the good work.
I also follow you on Twitter.
Any comment this morning on the Xpansys update?
It seems that their net cash is now more than their market cap!
Regards,
Denisthamenis
Hi Paul, good to see a splendid write up of Thalassa thank you. This is another holding which I bought last year for growth and being re assured by your good self that prospects still look positive.
Cheers from Lightningtiger
Hi Paul,
Are you looking to cover Dialight (LON:DIA) in todays report? It looks to have been of interest to you over the last year but was on too high a value. SP drop of 25% today off the back of the TS and hitting a new 52 week low. Cash halved but with no debt and profit of £14.5m+ to be expected this year I've personally bought a small holding this morning and will do some more research before deciding whether to go in with a more sizeable investment here.
Hi. Would be interested to hear your thoughts on Dialight also. Thanks.
Paul,
Thanks for the write-ups.
Looking at Tracsis, I am slightly bothered by the very low shareholdings of the CFO - only 4000 shares -and this has not moved for the last 1year. This is in contrast to the large holding of the CEO (who appears to be the only insider with a significant sharehold). I am relatively inexperienced in looking at companies' annual reports, but this does not feel right to me. Any thoughts? Thanks!
Hi Danyou,
It's fairly normal for the CFO of a small company to only have a small shareholding. Remember that CFOs are just hired hands really - they're not usually independently wealthy, and salaries are enough to live reasonably comfortably, but not have much surplus income, especially if supporting a family, as is usually the case.
So the CFO of Tracsis only having 4,000 shares is not something that would worry me at all.
Of far more importance is the CEO having a decent slug of shares. It's a worry when they don't, as you want to see them with plenty of skin in the game, which in this case the CEO of Tracsis does, so his interests are aligned with shareholders.
Cheers, Paul.