Small Cap Value Report (8 May 2017) - ECK, Alfa, PFD, NUM

Good morning and welcome back!
Eckoh (LON:ECK)
Share price:44p (+8%)
No. shares: 244.3m
Market cap: £107m
There is some great coverage by Paul in the archives, if you want to read back through the recent history of this company, which provides call centre solutions and secure payment technologies for businesses.
In summary: it was highly rated, but had a problem in a non-core division, which set back expected growth for the year ending March 2017.
Since then (last September), it has been on a gradual recovery track, and today's update has further soothed investor worries:
The Board of the Company confirms that trading for the year ended 31 March 2017 was comfortably in line with market expectations, with revenue and margin growing by over 20% for the fourth year in succession. The Company continues to make good progress in the UK, and the Group's operations in the United States have produced a record year in terms of revenues and order book; as a consequence US-derived revenues will again represent a growing proportion of total Group revenues.
"Comfortably in line" presumably means at the upper end of the range of expectations (otherwise wouldn't it just be "in line"?)
Net cash is ahead of expectations.
In a further piece of news, the non-Exec Chairman is stepping down, in what appears to be an orderly transition.
My opinion
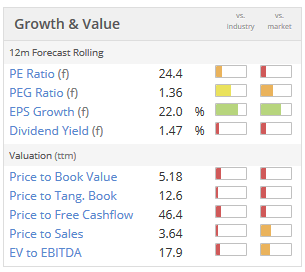
The Stockopedia Risk Rating is "Adventurous", which sounds about right.
On the one hand, you have a good history of profitability, you have a balance sheet moving back into net cash, and a company which owns its IP and seems to have plenty of expertise in its sector.
But there are some companies which are better suited for minority, external investors than others and this looks like one of those where perhaps the position of employees is a bit stronger than the position of external shareholders. I say that since it appears that a good deal of Eckoh's services rely to a greater or lesser extent on the skills of its own expert consultants.
So as always it's a balancing act. The stock does pay a dividend and business is growing. So do your own research and make up your own mind, it might be worth a look:
Alfa Financial Software (New flotation)
This company is seeking to list on the Main Market of the LSE, and I mention it in passing for two reasons.
Firstly, if you're interested in the sector, it sounds worthwhile: the company provides a platform ("Alfa Systems") which automates and improves processes for asset finance companies. Sample clients mentioned in this announcement are Bank of America, Barclays, Mercedes-Benz and Nordea.
The key argument for its future potential might be as follows:
The Directors believe this market is underserved due to a lack of purpose built modern solutions, with many asset finance companies currently relying on legacy systems or non-specialist ERP systems.
In the proposed IPO, the Chairman and CEO will be selling shares and targeting an initial 25% free float, and have a 365-day lock-up on remaining holdings. That is a reasonable length to me.
If you check the financial summary, it looks rather unusual as revenues increased 36% in 2016, but PBT actually fell slightly due to a very large item called "pre-IPO share based payments". Assuming that share based payments on this scale will not be be repeated (which I don't know for sure), the underlying growth trend is excellent, as adjusted EBIT rose from £22.5 million in 2015 up to £32.8 million.
So it looks like an interesting IPO but the second reason I mention it is just to offer a note of caution in relation to the market generally. Obviously we've been enjoying all-time highs in the major Indexes but in a global setting we've also seen a lot of companies coming to the market this year.
This article from March has evidence that "the number of flotations worldwide has surged to levels not seen since before the credit crunch".
While the London IPO market might not be surging to the same extent as New York, it nearly always says something to me about valuations when I see companies listing in their droves. A lot of it is sector-specific. For example, at the moment, software companies seem to be very enthusiastic about coming to market (e.g. $SNAP). This of course has implications for the software companies which are already listed too.
Premier Foods (LON:PFD)
Share price:43.75p (+1.7%)
No. shares: 832.4m
Market cap: £364m
Premier Foods Renews Relationship with Mondelez
Good news at Premier:
Premier Foods today announces it has signed 'Heads of Terms' for a strategic global partnership with Mondel?z International to renew the Company's long-standing licence to produce and market Cadbury branded cake and ambient dessert products. Once finalised, the new licence will run until 2022, with an option for the Company to extend this to 2025, subject to meeting certain performance criteria.
Under the proposals, Premier will possibly be able to make cakes under any Cadbury brand (Flake, Crunchie, etc).
It's good news and Premier shares are up nearly 10% since I last covered them in January.
News has been light since then. The only thing I'd mention is that agreed payments to the pension schemes were reduced out to 2023 (see here), in an update which reminded us that the present value of future payments to these schemes is £300 million - £320 million.
Net financial debt was last reported at c. £550 million, while the value of the Group pension deficit is the difference between two large numbers (assets and liabilities) each in excess of £5 billion.
So I doubt very much that today's update, positive though it may be, is important enough to change the overall outlook here.
I think the road back to a reasonable balance sheet will be a long one, so it's not something that would fit into my investment strategy. But it's not currently distressed and could eventually prove to be a huge winner, if it navigates through these challenges.
Numis (LON:NUM)
Share price: 278.5p (unch.)
No. shares: 113.3m
Market cap: £316m
Relevant to some of my prior comments in this article, Numis reports seeing "a scarcity of primary equity issuance in the UK market as a whole", in the six months to March 2017.
For the market as a whole, the value of secondary trading on the London Stock Exchange has shown an improvement on the comparable six month period. However, equity issuance across the market has not experienced any appreciable upturn, with equity funds raised on AIM and the Main Market combined totalling £13.6bn, down 1% versus the comparable prior period.
Despite these uninspiring macro conditions, and a 38% fall in its first-half PBT to £10.5 million, Numis reckons that it delivered a "creditable performance", considering that the comparable period was a record for the firm.
It goes to show that all-time highs in the stock market don't always translate to easy money for the brokers.
Outlook
The co-Chief Executives have "confidence that the business will have a satisfactory outcome for the full year":
Our second half has started very well with the completion of 10 fund raises generating fees of over £10m. Equities revenues continue to run at the high levels seen in the first half.
So it doesn't sound as if shareholders have any particular reason to panic.
In December, I suggested that this stock probably deserved a higher rating despite the lack of visibility in this industry. It has indeed risen since then, despite the weaker six months just recorded.
Profits are always going to be volatile, so investors need to try not to over-react to news every six months.
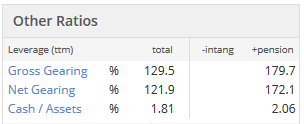
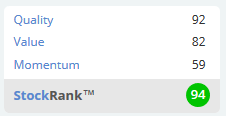
The StockRank is still excellent and I still consider this to be a good, investable company:
That’s it from me today. Paul is scheduled to be back tomorrow.
Thanks for reading!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
Hi Graham Re. Alfa Financial Software Holdings (LON:ALFA)
In case it escaped your notice, Alfa Financials IPO'ed on Friday 26th May. The shares closed 30% above the placing price. They seem to have been chased hard on the first dealing day.
I looked over the admission document earlier today and the company seemed to be way overvalued.
Would be very interested in your views.
Thanks, Ram
declaration: no long or short position.
Good bid for Waterman (LON:WTM) this morning. Decent results from £G4M and Treatt (LON:TET).
Yes but Treatt (LON:TET) shares are down 2.5% even though they are ahead of forecasts. £G4M I'm a bit concerned about them spending £5m on a building in York.
I was a little worried about the £G4M £5M costs for office space too, however this partially offsets my worries:
I keep selling winners much too soon. I must learn to live with worries like the ones you mention.
Yes me to. I was going to top up G4M but saw the new building that rather put me off, I will be interested in Paul's opinion on that use of money. My concern is high cost in York at what could be near the peak of property prices.
Yes but Treatt (LON:TET) shares are down 2.5% even though they are ahead of forecasts.
Sorry that might at least partly be down to me. Good results (as expected) but I found them a little underwhelming given the current rating and didn't like the amount of capex lined up going forward in both the UK and US. The UK site move also adds risk IMHO - do these things ever go smoothly? I've sold out for now but will keep it on my watchlist should the valuation start to look more attractive. All the best to others though!
All the best, Si
Si, I take it that you are not a John Lee style investor then?
:-)
FREng
Si, I take it that you are not a John Lee style investor then?
I don't mean to sound dumb but I don't know much about John Lee other than he is a successful long-term investor. Good for him. I don't follow other people and live and die by my own decisions and I am happy with my results over a number of years.Could they be better... undoubtedly yes!, but I've found over the years that following other people's style is not much use to me. I am not a trader by nature, but when I believe something to be overpriced I now sell rather than hold on.
On any valuation metric I use Treatt (LON:TET) is looking expensive, nice company though it is. I didn't think the forward looking comments were especially positive, the 7% increase in dividend was pretty mean, the poor H1 cashflow and increase in debt is a little disconcerting but should hopefully unwind in H2, and the expense and uncertainty of the site move was just too much for me. One day I will get the hang of being a momentum jockey... :)
All the best, Si
In 2005 for AIM 520 new companies were launched, it's peak year
in 2016 for AIM by comparison, 64 new companies were launched
AIM peaked in 2007 with total 1694 companies trading on it
AIM in 2016 had 982 companies trading.
Graham
I note your comments in the context of the Alpha IPO re: markets and wariness of a rush of stocks. But this contrasts with the Numis which talks about the paucity of stuff coming to the market impacting their figures.
Maybe there was a distinction I was missing?
Hi Trident, the distinction is between the US/global markets and the UK. Global markets saw a rush of IPO action in the first part of this year but it didn't happen in the UK.
On the Alfa intention to float subject, Numis who have pointed out a lack of IPO's in today's results are acting as Joint Global Co-ordinators, Joint Sponsors and Joint Bookrunners along with Barclays Bank so some work for them there.
Graham, thanks for the heads up about Alfa. Looks like a potentially good growth stock worthy of further research.
I bought into PFD a few years ago but no longer a holder. I was attracted by the perceived premium brands, the strategy of downsizing and disposing of non-core business and the change of management, who I thought would shake the company up and trigger a re-rating. It has not happened. I frequently see expensive advertising on TV for, for example, Mr Kipling cakes, but when I do my shopping they are often on special offer at similar price as supermarket own brands. Margins are paper thin. There is no realistic prospect of a dividend any time soon. I think the most likely way a return will come from PFD is if there is a bid, but I can't see what any bidder is going to want. And then there is the pension contributions which whatever has been agreed will take priority on cash generation. If the company can persuade the public that its brands really do deserve a premium price, and they can get their margins up, there may be hope, but I would want to see clear evidence of this before investing again.
Very interesting report, thanks Graham!
It's results from Gear4Music tomorrow comma so I'll be attending the analyst presentation in London and reporting back here probably late morning full stop
So my report tomorrow will be mainly written in the afternoon, just to flag that up to you and everyone else.
I really enjoyed Ed's webinar last week comma and the new stock classifications are very thought-provoking exclamation mark
Sorry this message is a bit haywire, I'm using a new Android phone comma as my iPhone died after going through a spin cycle in the washing machine full stop don't ask exclamation mark
Regards, Paul
reminds me of my dad dictating a letter to his secretary full stop paragraph Ram
A bit off topic, but as I am filling my isa I have opened a spreadbet account for trading outside the ISA wrapper. I hadnt counted on the trades going through at the published bid-offer, whereas the purchase price of the actual shares in a share dealing account is often well within the spread. I guess this is offset by the lack of capital gains tax for spreadbets. Any comments/ advice gratefully received. I hold mainly small caps, on average for 6 months.
Hi Hedley05,
You asked;
"I hadnt counted on the trades going through at the published bid-offer, whereas the purchase price of the actual shares in a share dealing account is often well within the spread."
The way to solve this problem is to phone up your spread betting company, and ask them to "work an order" for you - i.e. to see if they can deal inside the spread.
I find that Spreadex are excellent on small caps (I put most of our family business through them), and are happy to work orders for you, to get improved prices.
An alternative method is to use an intermediary broker, which is what I do. So my broker is paid a share of the commissions & funding by Spreadex, but he buys (or sells) the physical stock in the market, at an improved price, then he passes the stock over to Spreadex or IG.
So I get the benefit of improved pricing, within a tax-free spread bet account. The funding cost is about 4% p.a., but if you make a say 50-100% profit on a share, then the funding cost becomes largely irrelevant, and the tax saving is considerably larger than the funding cost.
Another big benefit of having an intermediary broker, is that it stops me doing anything stupid or reckless in my spread bet accounts. So I actually got my broker to disable my online dealing through Spreadex. That way I can't put daft Index trades, or any other foolish impulse trades through, which has been a big leak in my past performance.
So I thoroughly recommend having online dealing disabled for you, if (like me) you sometimes get a rush of blood to the head, and have a wild punt on something where you have no expertise or edge.
It's worth ringing up Spreadex and asking to discuss this with someone. If your account is a reasonable size, then they might well allocate you an account manager, who will act like your broker, and get to know the things you like, and can help you get keener prices.
Regards, Paul.
Thanks Paul,
Appreciate the reply. I am dealing with Spreadex already so good to hear that advice.
BW
Hederz
Hi Graham,
Thanks as always for your great reports. One question, though - if Premier Foods has 832.4 million shares valued at 43.7p each, how can its market cap be only 107M? Something I'm missing?
B2V
Hi B2V, that was an error, apologies. Thanks for pointing it out!
Hi Graham - Re. Alfa Financial Software
It looks as if you had sight of their admission document. Please could you let me have a link if it is publicly available.
Also it is worth pointing out that first dealing date is "in June" as today's announcement said.
Hi Ram, I only used today's RNS to get those Alfa figures. Scroll down through it and you will see the financial summary.
Regards
Graham
Hi Graham,
not sure if you cover some of the smaller financial companies. If you do, could you take a look at Numis (LON:NUM). Their RNS on HY results is mixed.
Hi troytea, I've covered Numis before and I do follow the financial sector, so am glad to cover it for you. See above.
Regards
Graham
Hi Graham, any chance you could look a Quantum Pharma (LON:QP.) Results were out last week , tanked since IPO but they've replaced the board raised some fresh capital recently and look like a possible recovery stock now??
Hi GJR, I'm not very strong on pharmaceuticals and don't think I can add any value on that today, thanks for the suggestion though!
Graham