Small Cap Value Report (8 Oct 2015) - NXR, ABDP, FLYB, DTG

Good morning!
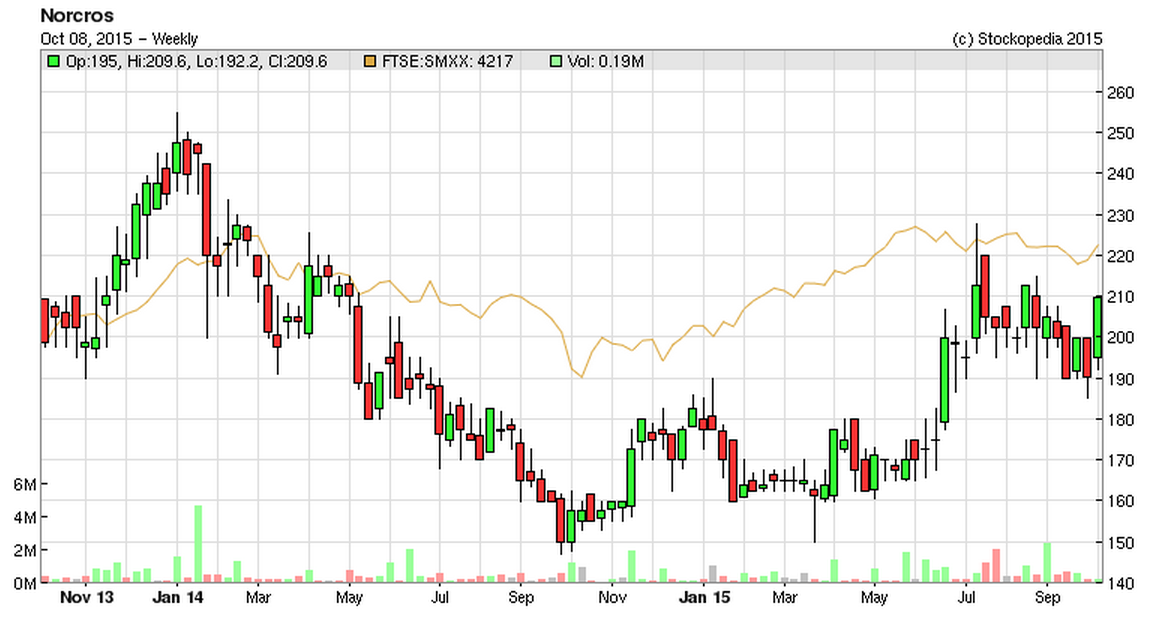
Norcros (LON:NXR)
Share price: 209.6p (up 0.8% today)
No. shares: 61.0m
Market cap: £127.9m
(at the time of writing, I hold a long position in this share)
H1 trading update - this group describes itself as, "the market leading supplier of innovative branded showers, taps, bathroom accessories, tiles and adhesives" - how refreshing to read a simple, plain English description of what the company does (a rarity today!).
The key part confirms that H1 is in line;
Group underlying operating profit1 in the first half is expected to be in line with the Board's expectations.
Other points;
- H1 sales £118.7m (up 9.3% vs LY, up 12.0% on constant currency basis)
- Encouragingly, 6.5% of that 12.0% is LFL organic growth
- Balance of 5.5% non-organic growth came from Croydex acquisition
- UK LFL growth +1.8%, S.Africa +16.9%
- UK retail sector "remains challenging"
- UK trade sector "good year on year growth" - new house building helped
- Croydex performing in line with expectations
- Net debt £29.5m (2014: £20.0m)
- Cash outflow of £20.1m for Croydex acquisition in the period
Outlook comments -
All of our businesses continue to perform well notwithstanding the mixed market conditions and the recent weakening of the Rand. The improved manufacturing efficiencies in Johnson Tiles UK have been sustained and we have made good progress in integrating the Croydex business into the Group. The Board remains confident that the Group will continue to make progress in line with market expectations for the year to 31 March 2016.
That all sounds pretty good to me.
Valuation - since the company is trading in line, these valuation figures should be accurate;
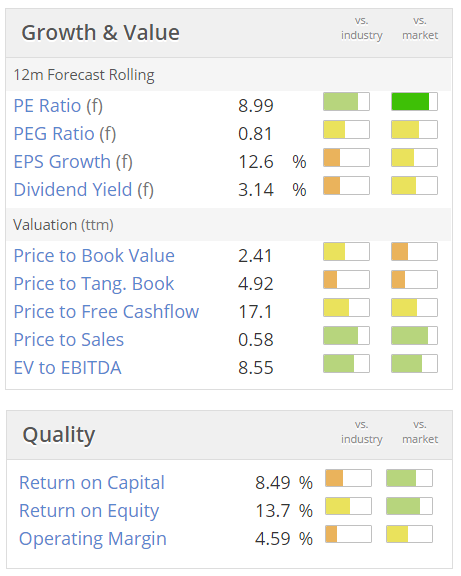
Bear in mind there is a large pension scheme here, which is a negative, so valuation needs to factor that in.
Stockopedia likes it, with a StockRank of 93.
My opinion - I like it - this is a long-term holding of mine, and it's strikingly cheap compared with practically everything similar out there.
I particularly like that S.Africa is powering ahead, shrugging off currency issues. The company is making very sensible acquisitions, with the intention of growing the business substantially. As long as they don't take on too much debt, then that's a good strategy in my view. Debt is under control at the moment, and remember that there is also freehold property on the balance sheet, so personally I tend to offset freeholds against debt, when valuing companies.
I think fair value here is about 300p, but am not holding my breath over when we are likely to get there! It's a boring share, but it pays nice divis, and at some point should re-rate nicely. That could happen very quickly (e.g. on a takeover approach), so I'd rather be in it, than sitting on the sidelines and miss any potential big move.
I'm still getting used to the new figures, post 10 for 1 consolidation. Still, you only have to move the decimal point one space to the left, to go back to "old money"! I think it was a sensible move to do the share consolidation - although it shouldn't make any difference, it now looks a more sensible share, whereas a 20p share looks a bit mickey mouse, particularly for institutional shareholders. Also, the price being quoted in 0.25p increments was clunky when it was 20p - each increment was quite wide, at 1.25% of the price. Whereas now it's c. 209p, and the price is moving in 1p increments, that's a much better 0.5% per price increment.
With a low valuation, and some good points in today's in line statement, I'd guess that the price is probably more likely to go up, than down.
Ab Dynamics (LON:ABDP)
Share price: 259p (up 7.2% today)
No. shares: 17.3m
Market cap: £44.9m
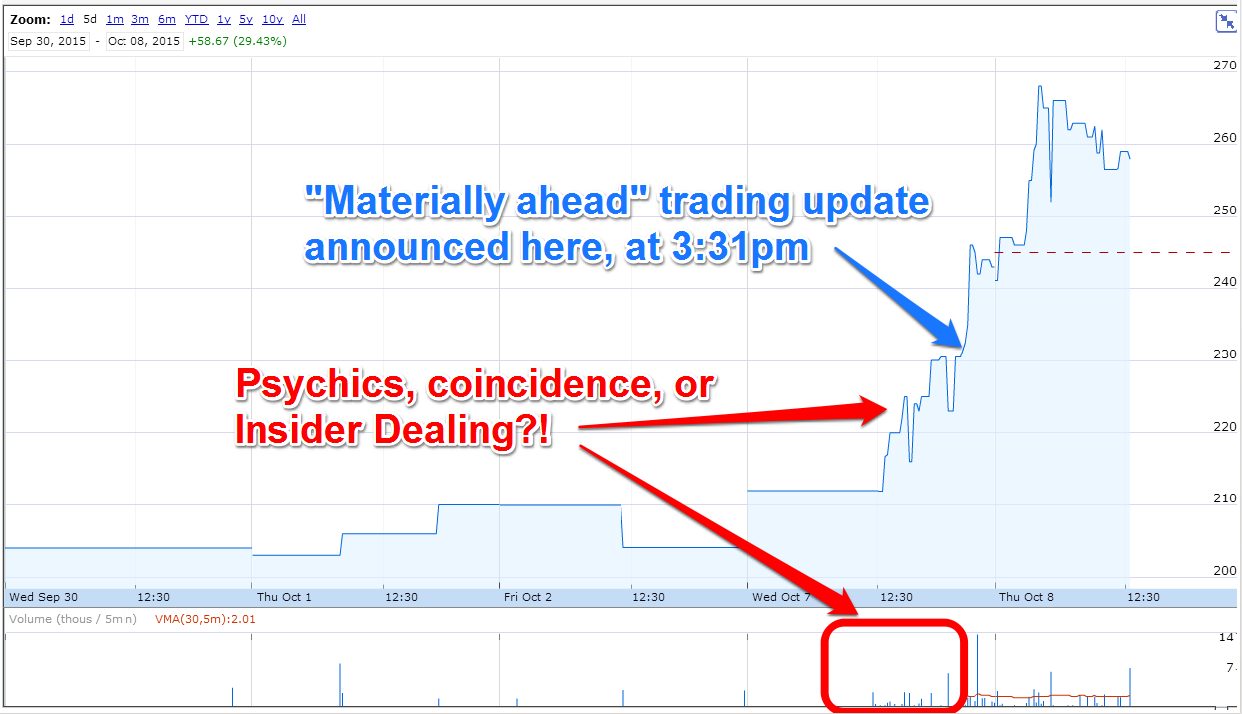
Trading update - this company issued a terrific update yesterday, but during market hours! At 3:31pm to be precise. What on earth are they thinking of? It caused chaos, and is horribly unfair to investors who are not glued to their screens all day. This is why all results & trading updates should be put out at 7am, or after the market has closed, but NEVER during market hours.
I'm going to ask the NOMAD, Cairn Financial, why they allowed this to happen, as it's very bad in my view. I've put a call in to them, and am awaiting a response.
There's also the matter of a flurry of trades before the announcement - so these people are either psychics, or it's a complete coincidence, or they're insider dealing. I accept that some people might have seen the price moving, and bought in reaction to that, but this certainly needs investigating. Someone was aggressively buying just before this announcement came out, and that's not on.
If you have concerns about this type of thing, then the relevant email address is:
|
EDIT: NB - There may actually be a valid explanation for what happened here. A source (NOT Cairn Financial, who haven't returned my call yet) has advised me that apparently a broker sent a share tip to its clients, which triggered the flurry of small buys.
ABDP was then apparently advised by the LSE, to issue their trading update immediately, instead of the scheduled time of 7am the next day.
I've not verified the broker tip, but this explanation certainly sounds plausible. The important thing is that the company will usually put out trading statements at 7am, and this was a one-off caused by the share price spiking up.
So perhaps we do not need to trouble the FCA after all?
EDIT2: A friend who is a client of the Share Centre has just contacted me to say that there was indeed a tip from the broker before the RNS, and that they bought some stock on the basis of that tip, before the RNS, but completely unaware that there was going to be an RNS.
Therefore, this is now case closed - not guilty! It was indeed a pure coincidence, and not psychic activity, nor insider dealing.
The announcement itself says;
The Group has performed well in 2015 and the Board expects to report revenues and profits materially ahead of market forecasts.
The company's year end is 31 Aug 2015.
Surprisingly, the company also says that it has turned down a mooted £2.3m Govt grant, as the "additional requirements are over burdensome". So it sounds like some civil servants have been busy doing what they do best - creating red tape! What a situation - whenever Govts meddle in business, they usually see to do more harm than good.
The company says it has sufficient funds, without the grant, to meet "increasing global demand", including financing its new building.
Outlook comments sound positive;
"The Group has performed well in the period with continued growth in revenues and profits and we have a strong order book that takes us into the new-year with confidence. Construction of the new facility should start in Q1 2016 with completion expected by the Q2 2017 bringing the increase in capacity necessary to meet the growing demand for our products"
My opinion - One broker expected 14.5p EPS for 2015, so "materially ahead" means at least 10% above. So 16p+, for a PER of 16.2. That rating looks justified in my view, as further earnings growth seems likely, given the doubling of capacity in the pipeline, and strong demand.
Clearly this company is on a roll, and looks worthy of further research.
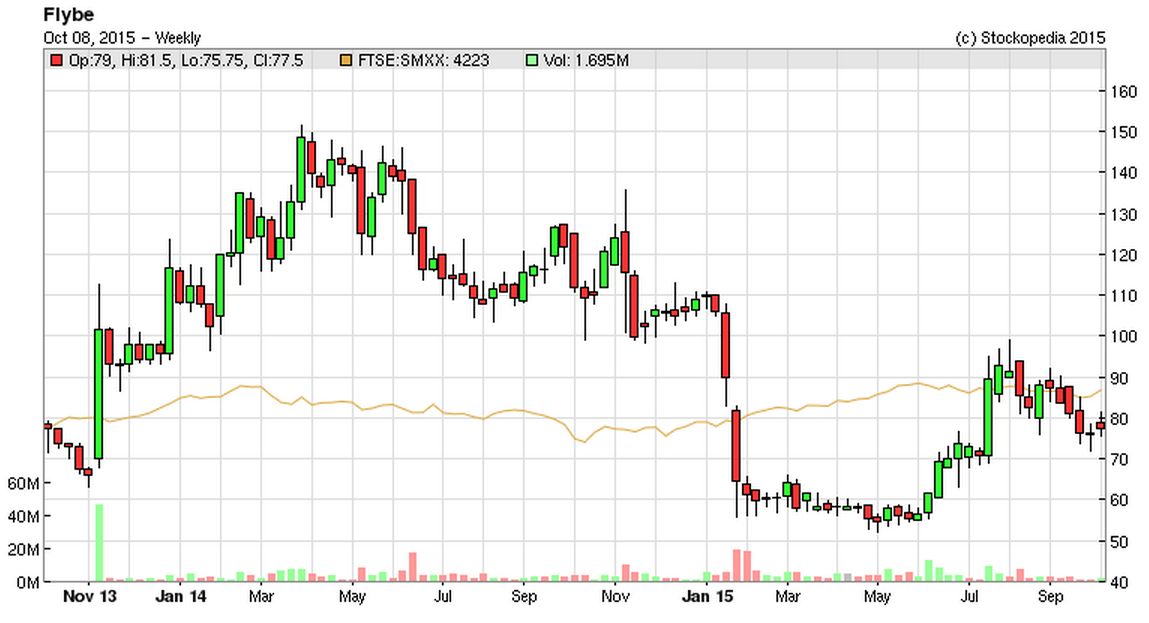
Flybe (LON:FLYB)
Share price: 77.4p
No. shares: 216.7m
Market cap: £167.7m
(as the time of writing, I hold a long position in this share)
Surplus planes update - one more down, six to go! Another of the surplus E195 planes has been found a role, connecting Exeter & Norwich airports with five destinations in mainland Europe, starting in Mar 2016.
Of the original fleet of fourteen legacy E195s, five were handed back to lessors, two have been based at Cardiff Airport under a long-term agreement signed in March 2015 with the airport operators, Cardiff Airport Limited. The agreement with RCA provides resolution for the eighth aircraft. Flybe is still in active discussions with other parties to redeploy the remaining six E195s and announcements will be made as appropriate.
No financial details are given, so one has to assume that using the aircraft on these routes should at least be less of a financial burden than paying the lease rentals, and it remaining idle. Although there's no guarantee that will be the case - if the new routes fail to generate passengers, then the losses could be even worse.
My opinion - I remain a holder here. The company's very strong balance sheet has enabled it to survive, and gradually resolve many legacy issues. It will be interesting to see what emerges in a couple of years' time. In my opinion, there is more upside potential, than downside risk, at the current price.
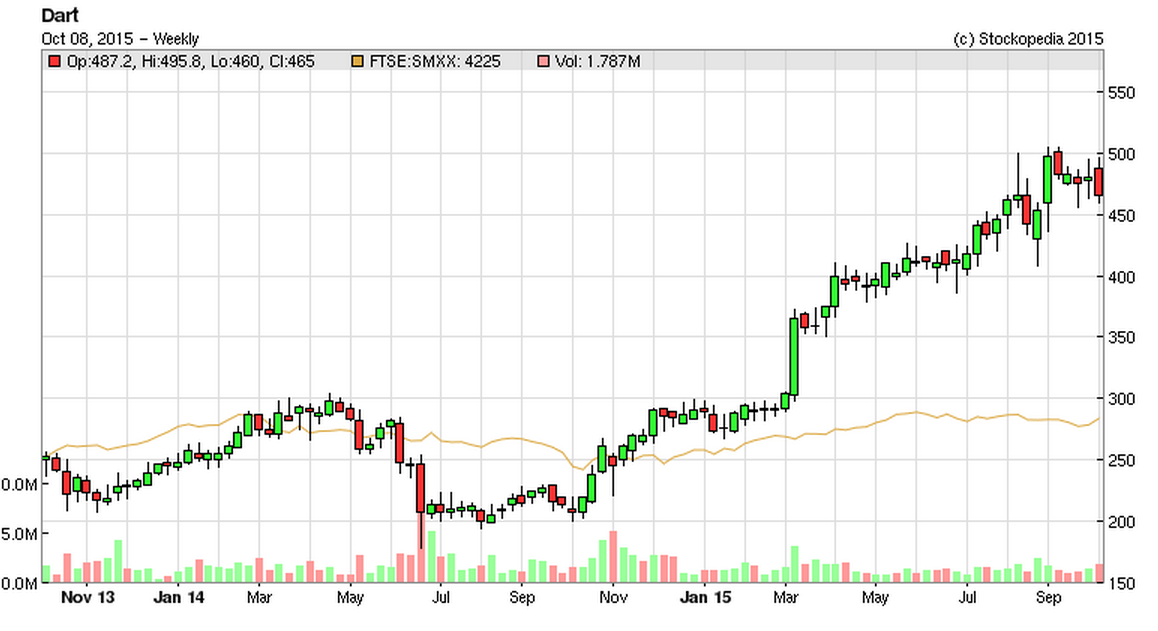
Dart (LON:DTG)
Share price: 469p (up 0.8% today)
No. shares: 147.6m
Market cap: £692.2m
(at the time of writing, I hold a long position in this share)
Trading update - there's a really strong trading update today - my attention was drawn to it by a reader in the comments section, many thanks (as this would normally be too big for me to report on here).
The key sentence says this;
With winter 15/16 Leisure Travel bookings for both package holiday and flight-only products continuing to perform in line with expectations and notwithstanding the important post-Christmas booking period that is still to come, it is now apparent that Group performance for the full year ending 31 March 2016 will materially exceed current market expectations.
Also, H1 profits are strongly up ("at least 60% ahead" of prior year, implying £143m+ H1 profits this time), with the caveat that losses over the H2 winter season will also be larger than last time.
Valuation - EPS expectations are currently at 40.6p EPS for this year, so we can add at least 10% to that, suggesting 45p+. That puts the shares on a PER of just over 10 - not bad.
My opinion - the market seems to be pricing in expectations of higher fuel prices, a large element of airline costs, which is probably why these shares have stopped rising, and if anything now seem to be drifting down.
So the big question is whether we should be regarding this year as a bit of a one-off good year, and therefore factor in a fall in future earnings for valuation purposes?
That's a matter for market sentiment to resolve, but for me, the recent dip in price, combined with a rip-roaring trading update today, has tempted me to pick up a small opening position here, more as a short-medium term trade, than an investment. The bumper interim figures might well spur another wave of optimism perhaps, when they get published in late Nov?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Paul, You maybe interesting in this video of interview with ABDP MD: https://www.youtube.com/watch?v=gaZ2XfnWlns&feature=youtu.be
Hi Paul -
RE. Norcros (LON:NXR) I have looked at the numbers and quite like this stock. The only thing that sticks out to me is the large pension deficit which might be the reason for the low valuation. The deficit stands at £42m which is 81% of Net Assets. The recovery plan agreed with the trustees of £2m pa + CPI is much lower than the norm (around 10% p.a. = £4m). However on the positive side, interest rates are on the way up, so the scheme liabilities will come down hopefully by more than changes in the scheme assets.
I bought a holding this morning.
Regards, Ram
Paul ADBP also have at least £7m net cash which is not far off 20% of the mcap meaning the rating is even lower
Paul & indeed All,
Can anyone advise on good sources of corporate news (particularly for small caps)? For example, French Connection is rocketing (er, from a much reduced base) and I cannot seem to find any news which suggests why that might be.
ADBP - which broker - what did the tip say .... "Weve heard on the grapevine that results are going to be ahead and the grant has been refused cos they are making enough money anyway" .. ??
All the more reason for them to come clean and upfront and say exactly what they tipped and how !!
Interesting to look at the sector with building materials required for house building, which Norcros comes into. Whilst there must be some taps and showers in a house, as well as tiles, there is certainly a lot more bricks. MBH seems to be doing well since they are into bricks. Certainly a good sector to consider. there is also Marshalls (MSLH) , a good "ruler" stock into stone slabs and landscaping.
ABDP - I've just written to the Chairman & FD about yesterday's announcement. And emailed you, Paul.
We hold.
Paul - what do you think about the Dart DTG trading statement that came out this morning. I'm a long term holder and it has moved up a lot recently. However I am surprised that the market hasn't taken it higher today as the closing outlook statement finishes " it is now apparent that Group performance for the full year ending 31 March 2016 will materially exceed current market expectations." You cant ask for more than that..
Hi Chipspa,
I hadn't got round to looking at Dart (LON:DTG) yet. Airlines are a bit under a cloud at the moment, as the market seems to be pricing in higher oil prices. Let's hope airlines have hedged their fuel cost for many years to come at cheap rates, during this period of cheap oil.
That's probably the reason why a muted response to DTG positive trading update - the market looks forward, and might see this as a boom period with profits that could fall back somewhat as fuel becomes more expensive in future.
Regards, Paul.
Airlines should not hedge "for many years to come"! It's a recipe for bankruptcy: unless all your competitors have the same hedge, any error will be enough to destroy you because they will be able to sell their tickets so much cheaper than you. With a duration of "many years" a modest error would obliterate a multiple of typical airline margins. All they need to hedge really is tickets they've already sold -- for unsold seats they can pass through oil price changes to customers as most tickets are dynamically priced anyway (or max up to their main competitors' hedges' duration).
Besides, who knows if oil is currently "cheap"?
(Disclosure: short oil.)
Hi cig,
Normally I would agree with you about airlines being wise NOT to hedge their fuel too far forwards.
However, as we are currently in a situation where the oil price has dipped below the cost of production of some oil, then people in the sector tell me it's only a matter of time before supply contracts, demand rises, and the oil price goes back up again.
Therefore to my mind, this is exactly the sort of time when a bold move on hedging would make sense. But I also take on board your point, that a safety first approach would be to keep in line with the hedging arrangements of the competition, thus avoiding backruptcy as your first priority.
Regards, Paul.
I agree with your friends, but I probably disagree with the timing: I see something like 3-5 years before demand catches up with supply. So somewhere below say $30 within a couple of years. Then a phase where everybody gets convinced that $30 (or wherever the bottom is) oil is here to stay. And then up. (Basically I think we're in the "bull trap" phase in the classic bubble cycle chart.)
In any case, a bold move in oil hedging by an airline will either bankrupt it, or will be so successful as to turn the bloody planes into a distraction. So if an airline management is tempted, they should quit and move to an actual hedge fund, rather than turn their airline into a clunky one.
DTG
TIME FOR AN UPDATE?
the bumper interim figures might well spur another wave of optimism perhaps, when they get published in late Nov? - See more at: http://www.stockopedia.com/content/small-cap-value-report-8-oct-2015-nxr-abdp-flyb-dtg-107763/#sthash.j2ddZX0a.dpuf
Good luck with this one guys but personally I still really think the BoD of Norcros are overpaid for a company of their size. I held for a while but sold out primarily on this basis.
Refreshing? Frightfully old fashioned, more like. "A leading provider of lavacrum solutions" would have been far more appropriate for 2015. Must do better.
:-)
Gostevie
Think Paul's fair value of 30p is the "old money" price pre the 10 for 1 consolidation so will be 300p now.
Thanks dmjram.
I agree with you comments about Norcros Paul and have had a substantial holding for some time now. All of my portfolio can loosely be described as boring and that’s fine by me. Experience has taught me that all the jam tomorrow stuff turns to toast!
I don’t think there will be any great excitement that will lead to a 10% or so increase in the next couple of weeks but I reckon there should be a steady trickle upwards over the coming months; boring is good!
Paul, do you mean fair value is 300p, not 30p? Perhaps I've misunderstood.
CliveBorg,
Many thanks for pointing out my error, have corrected.
Told you I hadn't got used to the new money on Norcros (LON:NXR) !!
Regards, Paul.